by Brandi Marcene | Jan 16, 2026 | Definitions
Iowa locals are feeling the pinch from the rising costs, growing credit card balances, and medical bills that pile up faster than a monthly income.
According to recent data, the consumer price index rose again, with prices climbing both month-over-month and year-over-year, highlighting how inflation continues to strain household budgets. The Consumer Price Index Rises 0.3% In September and Hits 3.0% Annually.
Personal loans, student debt, and daily expenses are stressing household budgets, leaving many struggling to stay afloat. As per a survey, an average household carries an average total debt of $46,130, including credit of about $30,420, student loans, credit cards, and other debt.
This guide breaks down the top programs, how they operate, and which providers are most trusted in Iowa for 2026.
How Does Iowa Debt Relief Work for Residents?
Iowa residents can access programs tailored to different financial situations, just as residents in Arizona and Alabama, with most focusing on unsecured debt such as credit cards, medical bills, personal loans, and lines of credit.
Generally, the Iowa debt relief program aims to:
- Reduce what you owe through negotiation
What Debt Relief Programs Are Available for Iowa Residents?
Iowa locals have multiple debt relief options, depending on the debt type, amount, and personal financial stability. Each of the programs serves a different need and comes up with unique benefits and tradeoffs. Here’s a clear breakdown:
-
- What they do: Negotiate directly with customers to reduce the total amount owed.
- Who they’re for: Individuals with high unsecured debt who can’t repay the entire balance.
- How they work: Clients usually fund a specific account, and the settlement company negotiates with creditors. Fees are usually performance-based, which means they’re charged only after a successful settlement.
- Nonprofit Credit Counseling & Debt Management Plans (DMPs)
- What they do: Consolidate debt numbers into one manageable payment and often reduce interest rates.
- Who they’re for: Households having a stable income who want a structured repayment support without ever reducing balances.
- How they work: Clients get financial counseling, budgeting guidance, and may be enrolled in a DMP. Nonprofit fees are typically low, and the primary focus is on education and long-term financial health.
- Hybrid or National Programs
- What they do: Combine negotiation, counseling, and account management.
- Who they’re for: Locals in rural areas or those who are in need of services that aren’t locally available.
- How they work: Such programs offer a flexible solution that includes settlement, repayment plans, or a mix of both. They often scale nationwide, providing a broader support infrastructure.
Iowa Debt Relief Providers Worth Comparing
| Company |
Best For |
Minimum Debt |
Fees |
Availability in Iowa |
| New Era Debt Solutions |
Personalized debt settlement |
$10,000+ unsecured debt |
Performance-based |
Nationwide (Iowa included) |
| National Debt Relief |
High unsecured debt balances |
$7,500+ unsecured debt |
Performance-based |
Nationwide |
| Accredited Debt Relief |
Multiple unsecured debt types |
$10,000+ unsecured debt |
Performance-based |
Nationwide |
| Freedom Debt Relief |
Large, established settlement programs |
$7,500+ unsecured debt |
Performance-based |
Nationwide |
| Century Support Services |
Iowa-focused negotiation support |
Varies by case |
Performance-based |
Serves Iowa residents |
| APFSC (Nonprofit) |
Credit counseling & DMPs |
No strict minimum |
Low nonprofit fees |
Available in Iowa |
| InCharge (Nonprofit) |
Budgeting & debt management |
No strict minimum |
Low nonprofit fees |
Available in Iowa |
New Era Debt Solutions is seen as a leading option for Iowa debt relief, especially for residents seeking a hands-on, negotiation-focused approach. With more than two decades of experience in debt settlement, New Era focuses on reducing unsecured debt balances by negotiating directly with creditors to accept less than the full amount owed.

![]()
Is This Debt Relief Option Right for You?
Not every debt solution works for every situation. A free consultation can help determine whether New Era’s debt settlement approach aligns with your financial goals.
See If You’re Eligible
Ideal For
Iowa residents who are carrying more than $10,000 in unsecured debt and who want individual negotiation rather than a rigid, standard program.
How It Works
After a free financial evaluation, New Era designs a customized settlement strategy based on the client’s debt profile and cash flow. Clients fund a dedicated account over time, and negotiations begin once ample funds are available.
What Makes It Unique
New Era has built up a solid reputation; they have received great customer feedback and are recognized by the Better Business Bureau as a reputable debt relief company in Iowa.
![]()
Know How New Era’s Program Works?
If you’re exploring New Era’s debt settlement approach, which aligns with your financial situation, this in-depth review explains typical timelines, real-world outcomes, and key considerations to understand before enrolling.
See If You’re Eligible
National Debt Relief
National Debt Relief is one of the largest debt settlement providers in the country and serves many Iowa residents with significant unsecured debt balances.

Best For
Iowa residents with $7,500 or more in unsecured debt, including credit cards, medical bills, and personal loans.
How It Functions
Following a no-cost evaluation, National Debt Relief devises a structured payment plan and begins communicating with creditors on the client’s behalf.
How It Distinguishes Itself
Its scale, established systems, and large customer support infrastructure provide reassurance to clients who prefer a nationally recognized name when looking for national debt relief in Iowa.
Accredited Debt Relief
Accredited Debt Relief focuses on settlement-based solutions for clients when dealing with a range of unsecured debt types.

Best For
Iowa residents are managing multiple unsecured accounts, such as credit cards, personal loans, and revolving credit lines.
How It Works
The process begins with an in-depth consultation and financial review, followed by the creation of a customized settlement plan.
Why It Stands Out
Accredited Debt Relief’s commitment to transparency and consumer-focused practices makes it a reassuring option for individuals seeking clarity as they navigate Iowa debt relief programs.
Explore more about Accredited Debt Relief here.
Freedom Debt Relief
Freedom Debt Relief is one of the most well-known debt settlement companies in the United States and maintains a strong presence in Iowa debt relief searches. It’s structured for individuals dealing with large debt loads.

Best For
Iowans living with high unsecured debt balances who are searching for a trustworthy partner with a good track record.
How It Works
Once the complimentary evaluation is complete, clients are then assigned a certified debt consultant who can negotiate directly with creditors to secure reduced payoff amounts.
Why It Stands Out
Its nationwide footprint, extensive experience, and structured negotiation process make Freedom Debt Relief a common consideration within Iowa debt relief programs.
Century Support Services
Century Support Services offers debt settlement assistance with a focus on negotiation strategy and client education. While national in scope, it serves Iowa locals looking for the right balance between structure and flexibility.

Best For
Iowa residents seeking settlement support with ongoing guidance throughout the negotiation process.
How It Works
After evaluating the client’s unsecured debt, Century develops a settlement roadmap and negotiates with creditors as funds become available in the program account.
Why It Stands Out
The century’s emphasis on education and clear expectations helps clients better understand the mechanics of debt settlement while working toward resolution.
To better understand how leading providers stack up, explore our ranking of debt settlement companies based on customer feedback and industry credibility.
Frequently Asked Questions About Iowa Debt Relief
What does Iowa debt relief really consist of?
Iowa debt relief refers to a range of structured programs designed to help residents manage or resolve unsecured debt, such as credit card, medical bill, and personal loan debt.
Are debt relief programs in Iowa safe to use?
Legitimate Iowa debt relief programs operate in accordance with state and federal regulations, use transparent pricing, and clearly disclose fees. Most reputable providers charge performance-based or nonprofit fees only after progress is made.
What amount of debt is required to qualify for an Iowa debt relief program?
Most settlement-based Iowa debt relief programs require at least $7,500–$10,000 in unsecured debt to qualify. Nonprofit credit counseling and debt management plans often accept lower balances, especially for households with stable income seeking structured repayment rather than balance reduction.
Would debt relief in Iowa negatively affect my credit?
Some Iowa debt relief options, particularly settlement programs, may temporarily impact credit scores. However, many residents pursue relief to avoid defaults, collections, or legal action, which can cause more severe long-term damage.
Can I access national debt relief programs while living in Iowa?
Yes, many nationally recognized debt relief companies legally serve Iowa residents. These programs provide access to large support teams and multiple relief options.
by Alex Demolitor | Jan 13, 2026 | Definitions
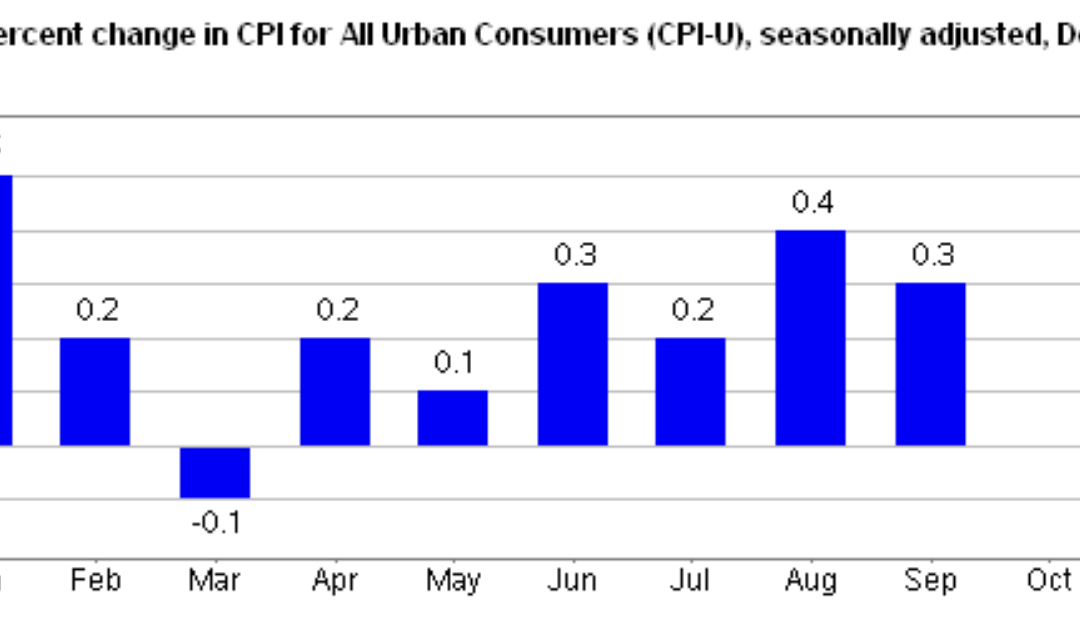
The December 2025 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.3% this month, up from the 0.2% average over the last two months. These data were released at 8:30 am EST on January 13, 2026, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 2.7%, matching the recent two-month average.
Today’s core results also missed economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents December’s figures, while the right column represents forecasters’ expectations. As you can see, the red metrics highlight how core inflation was weaker than anticipated.

With Fed Chairman Jerome Powell still leading the FOMC until his term ends later this year, he reiterated in December that he’s in no hurry to cut rates. And with investors pricing in little to no chance of a rate cut in January, Bloomberg reported on Jan. 9 that “Bond traders maintained an outlook for two rate cuts overall in 2026, with the first seen by mid-year.”
As a result, disappointing economic data will likely be required for accelerated easing over the next few months.

Food Prices
The food index rose by 0.7% MoM in December, and five of the six major grocery indices increased this month.
- Cereals and bakery products (+0.6%)
- Meats, poultry, fish, and eggs (-0.2%)
- Dairy and related products (+0.9%)
- Fruits and vegetables (+0.5%)
- Nonalcoholic beverages (+0.4%)
- Other food at home (+1.6%)
The food away from home index also jumped by 0.7%, as restaurant inflation kept pace with grocery prices in December.
Energy Prices
The energy index increased by 0.3% MoM in December, with gasoline prices down by 0.5%, electricity down by 0.1%, and natural gas rising by 4.4%.
Core CPI
The December core CPI rose by 2.6% Y-o-Y, matching the average figure from the previous two months. As a reminder, the October CPI report was cancelled due to the government shutdown, so the metrics don’t have comparable MoM data from November.
- Shelter index: (+0.4%)
- Rent index: (+0.3%)
- Owners’ equivalent rent: (+0.3%)
- Motor vehicle insurance: (NA)
- Medical care services: (+0.4%)
- Physician services: (+0.3%)
- Hospital services: (+1.0%)
- Airline fares: (5.2%)

Seasonally Unadjusted CPI
Before seasonal adjustments, the CPI-U for December 2025 increased by 2.7% Y-o-Y to an index level of 324.054. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
Let the Good Times Roll
With solid economic data pointing to steady economic activity, the FOMC can continue its wait-and-see approach and not rush further rate cuts.
For example, the BLS released its Employment Situation report on Jan. 9. The U.S. economy added 50,000 net new jobs, and the unemployment rate declined to 4.4%. Furthermore, average hourly earnings (a proxy for wage inflation) increased from 3.6% Y-o-Y in November to 3.8% Y-o-Y in December. Consequently, the labor market remains on solid footing for the time being.

As further evidence, the BLS released its Job Openings and Labor Turnover Summary (JOLTS) on Jan. 7. And with more than seven million job openings still available, the metric (the blue line below) has stabilized near its pre-pandemic baseline. Likewise, layoffs and discharges (the green line below) also remain in a healthy range and highlight how most employers continue to retain staff.

Finally, the Atlanta Fed updated its Q4 GDPNow model on Jan. 9. And while the results can be skewed by fluctuating imports and exports, and the data is lagged, the latest reading pegs growth at 5.1% (the green line below). If realized, the results would be well above 2% trend growth and economists’ consensus estimates (the blue line below).

Add it all up, and the recent data is strong enough to suppress any rate-cut calls, and the FOMC should continue to preach the same message until weaker data forces its hand.
Turning to the financial markets, gold had a tremendous 2025, and the fundamentals support more strength in 2026.

To explain, the orange line above tracks the 5-year rolling percentage change in the gold price, while the blue line above tracks the 5-year rolling percentage change in global military spending. As you can see, the yellow metal lives up to its safe-haven reputation when the geopolitical outlook becomes more treacherous.
To that point, U.S. President Donald Trump has advocated for a 50% increase in the U.S. military budget, in what he called “very troubled and dangerous times.” As a result, the spending trend should continue, and the developments are bullish for gold.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
Furthermore, if you’re looking to diversify your portfolio or strategically exit a business, there are several strategies to help realize the best valuation. Our extensive guides for company owners in Illinois, Michigan, and Ohio provide insights into compliance issues, tax plans, demand assessments, and much more.
In addition, please consult our list of debt management firms for other financial services in your area.
by Alex Demolitor | Dec 18, 2025 | Definitions
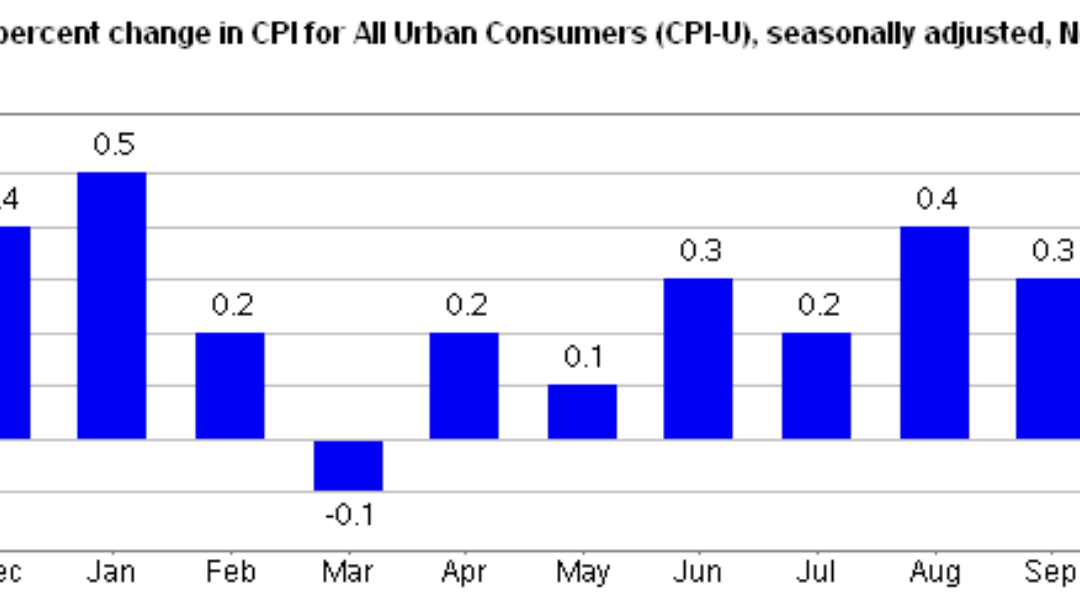
The November 2025 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.2% over the last two months, down from 0.3% in September. These data were released at 8:30 am EST on December 18, 2025, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 2.7%, down from 3.0% in September. As a reminder, the October CPI report was cancelled due to the government shutdown, so there are no comparable figures on a MoM basis.
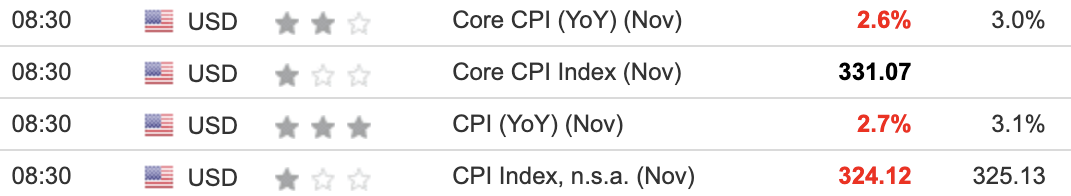
Today’s results also missed economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents November’s figures, while the right column represents forecasters’ expectations. As you can see, the red metrics highlight how inflation was subdued relative to forecasts.
After cutting interest rates for the second consecutive meeting, Fed Chairman Jerome Powell emphasized on Dec. 10 that “Monetary policy is not on a preset course, and we will make our decisions on a meeting-by-meeting basis.”
“Everyone around the table at the FOMC agrees that inflation is too high and we want it to come down, and agrees that the labor market has softened and that there is further risk…. I’ve said before a couple times, we’re well positioned to wait to see how the economy evolves. We’ll just have to see.”
As such, with the FOMC confronting uncertainty on both sides of its dual mandate, further labor market weakness is likely necessary for more easing in the months ahead.
Food Prices
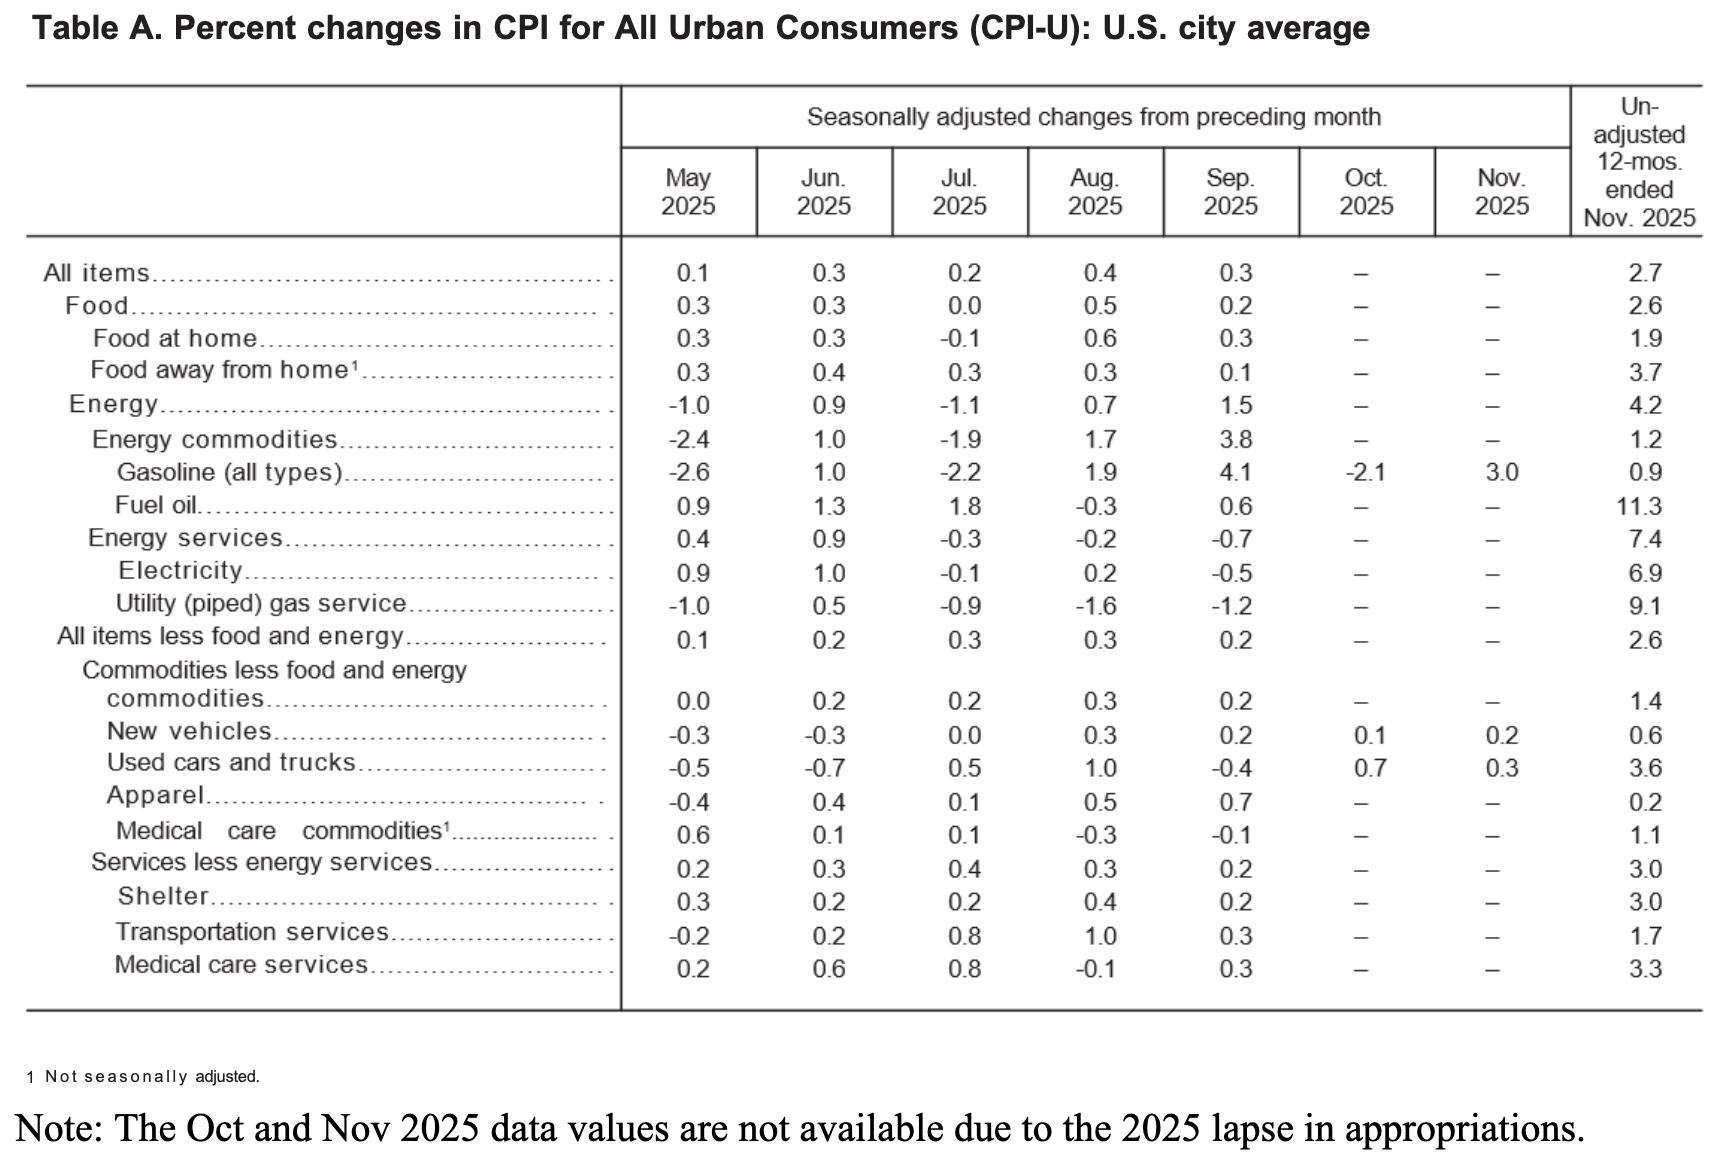
The food index rose by 2.6% Y-o-Y in November. Again, the monthly changes are neglected due to the missing October report, so the figures below are relative to November 2024.
- Cereals and bakery products (+1.9%)
- Meats, poultry, fish, and eggs (+4.7%)
- Dairy and related products (-1.6%)
- Fruits and vegetables (+0.1%)
- Nonalcoholic beverages (+4.3%)
- Other food at home (+1.3%)
The food away from home index was up by 3.7%, as restaurant inflation continues to outpace grocery prices.
Energy Prices
The energy index rose by 4.2% Y-o-Y in November, with gasoline prices up by 0.9%, electricity by 6.9%, and natural gas by 9.1%.
Core CPI
The November core CPI rose by 2.6% Y-o-Y, down from 3.0% in September. Below is an itemized breakdown of the main Y-o-Y price fluctuations seen in the core CPI reading:
- Shelter index: (+3.0%)
- Rent index: (+3.0%)
- Owners’ equivalent rent: (+3.4%)
- Motor vehicle insurance: (NA)
- Medical care services: (+3.3%)
- Physician services: (+1.7%)
- Hospital services: (+5.7%)
- Airline fares: (-5.4%)
Seasonally Unadjusted CPI
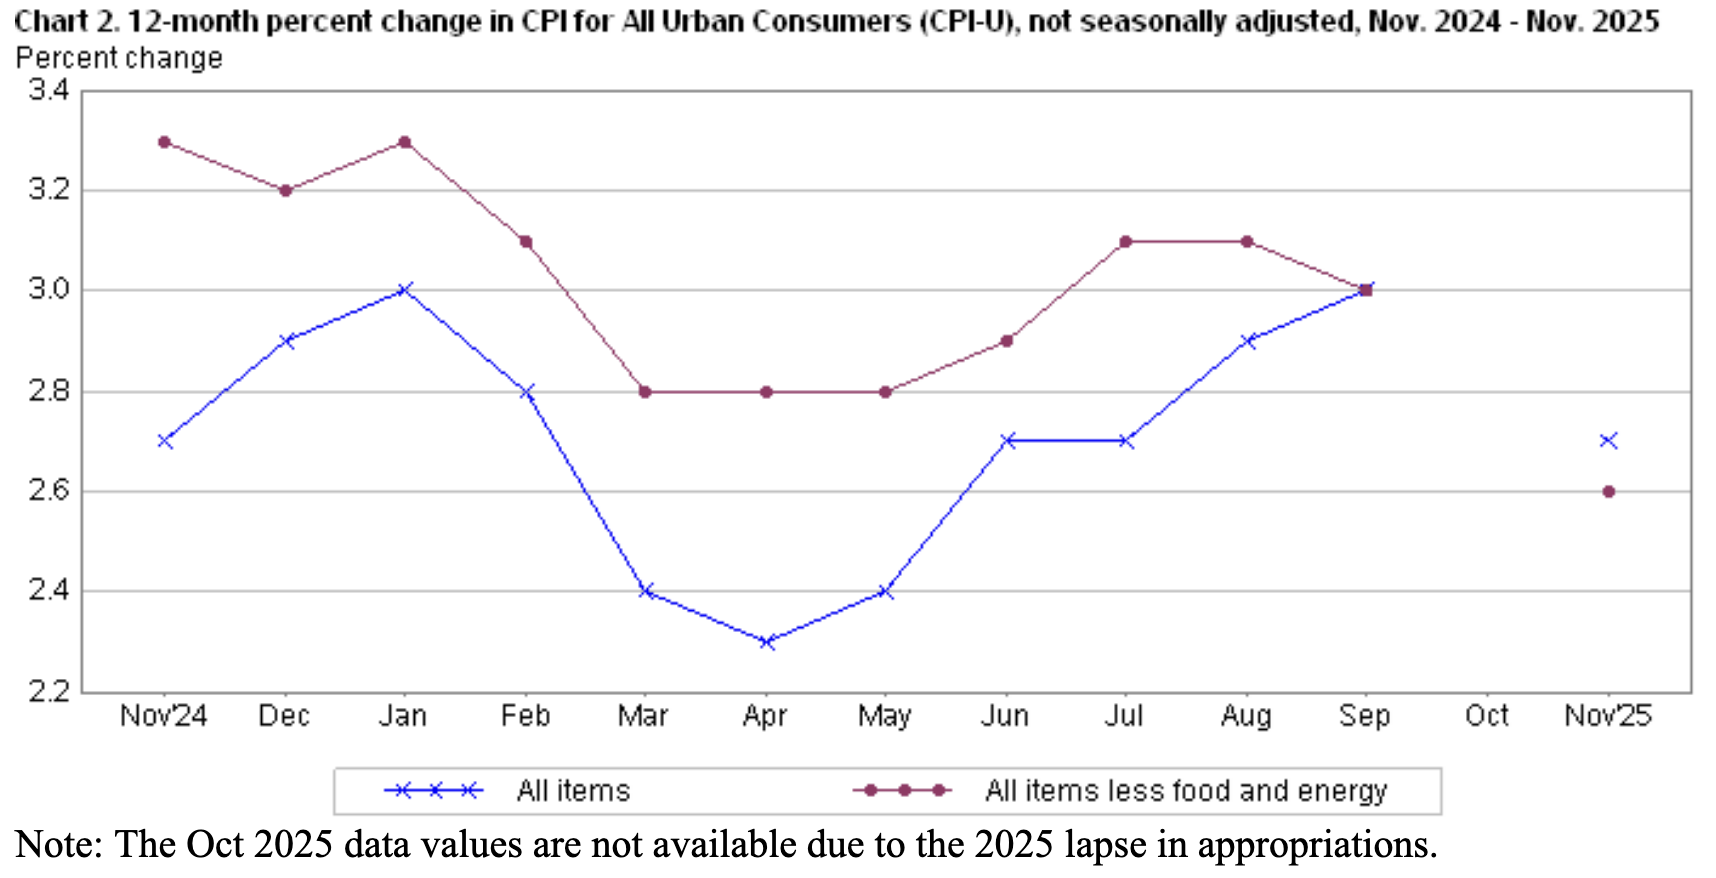
Before seasonal adjustments, the CPI-U for November 2025 increased by 2.7% Y-o-Y to an index level of 324.122. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
Not Bad Enough
With mixed economic data hitting the wire in recent days, there isn’t any concrete evidence that supports the Fed altering its meeting-by-meeting approach.
For example, S&P Global released its U.S. Composite PMI on Dec. 16. And while growth momentum has slowed, the current reading of 53 signals a healthy expansion. An excerpt read:
“The headline S&P Global US PMI ® Composite Output Index fell to 53.0 in December from 54.2 in November, according to the ‘flash’ reading (based on about 85% of usual survey responses). The latest reading was the lowest since June, though continues to indicate robust economic growth….
“Input cost inflation accelerated markedly in December, hitting the fastest since November 2022,” while “increased costs again fed through to higher selling prices, with the overall rate of inflation rising to the steepest since July and therefore amongst the greatest since the pandemic-related price-surge of 2022.”
So, while business activity has softened over the last few months, the modest momentum deceleration is unlikely to induce rate cuts with alternative inflation metrics trending up.

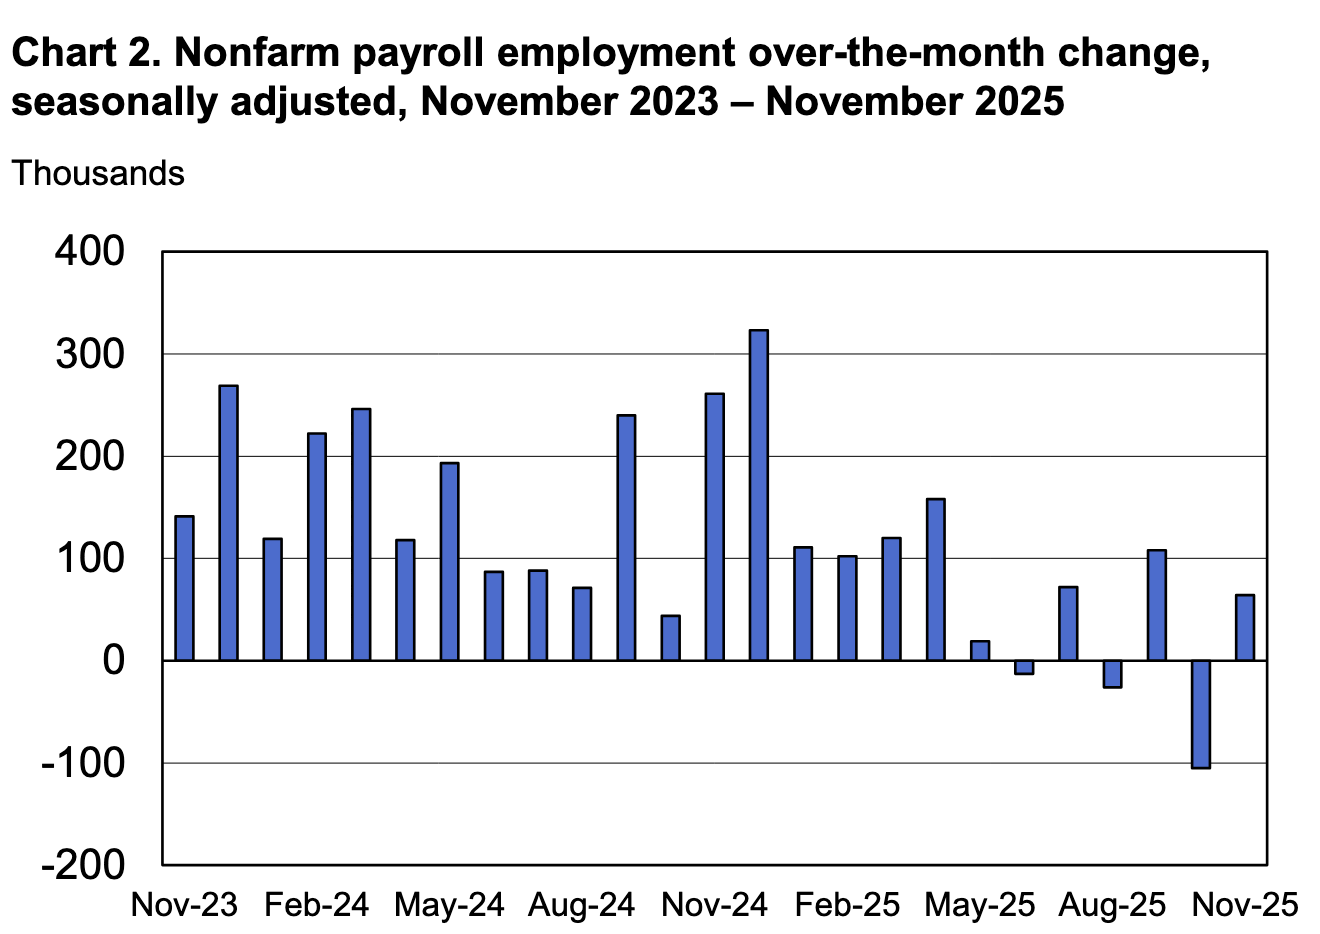
Furthermore, the U.S. Bureau of Labor Statistics revealed on Dec. 16 that the U.S. economy added 64,000 net new jobs in November — a solid increase given the paltry figures realized over the last few months. The report also noted how “Construction employment grew by 28,000 in November, as nonresidential specialty trade contractors added 19,000 jobs,” which highlights decent strength in the interest-rate sensitive sector.
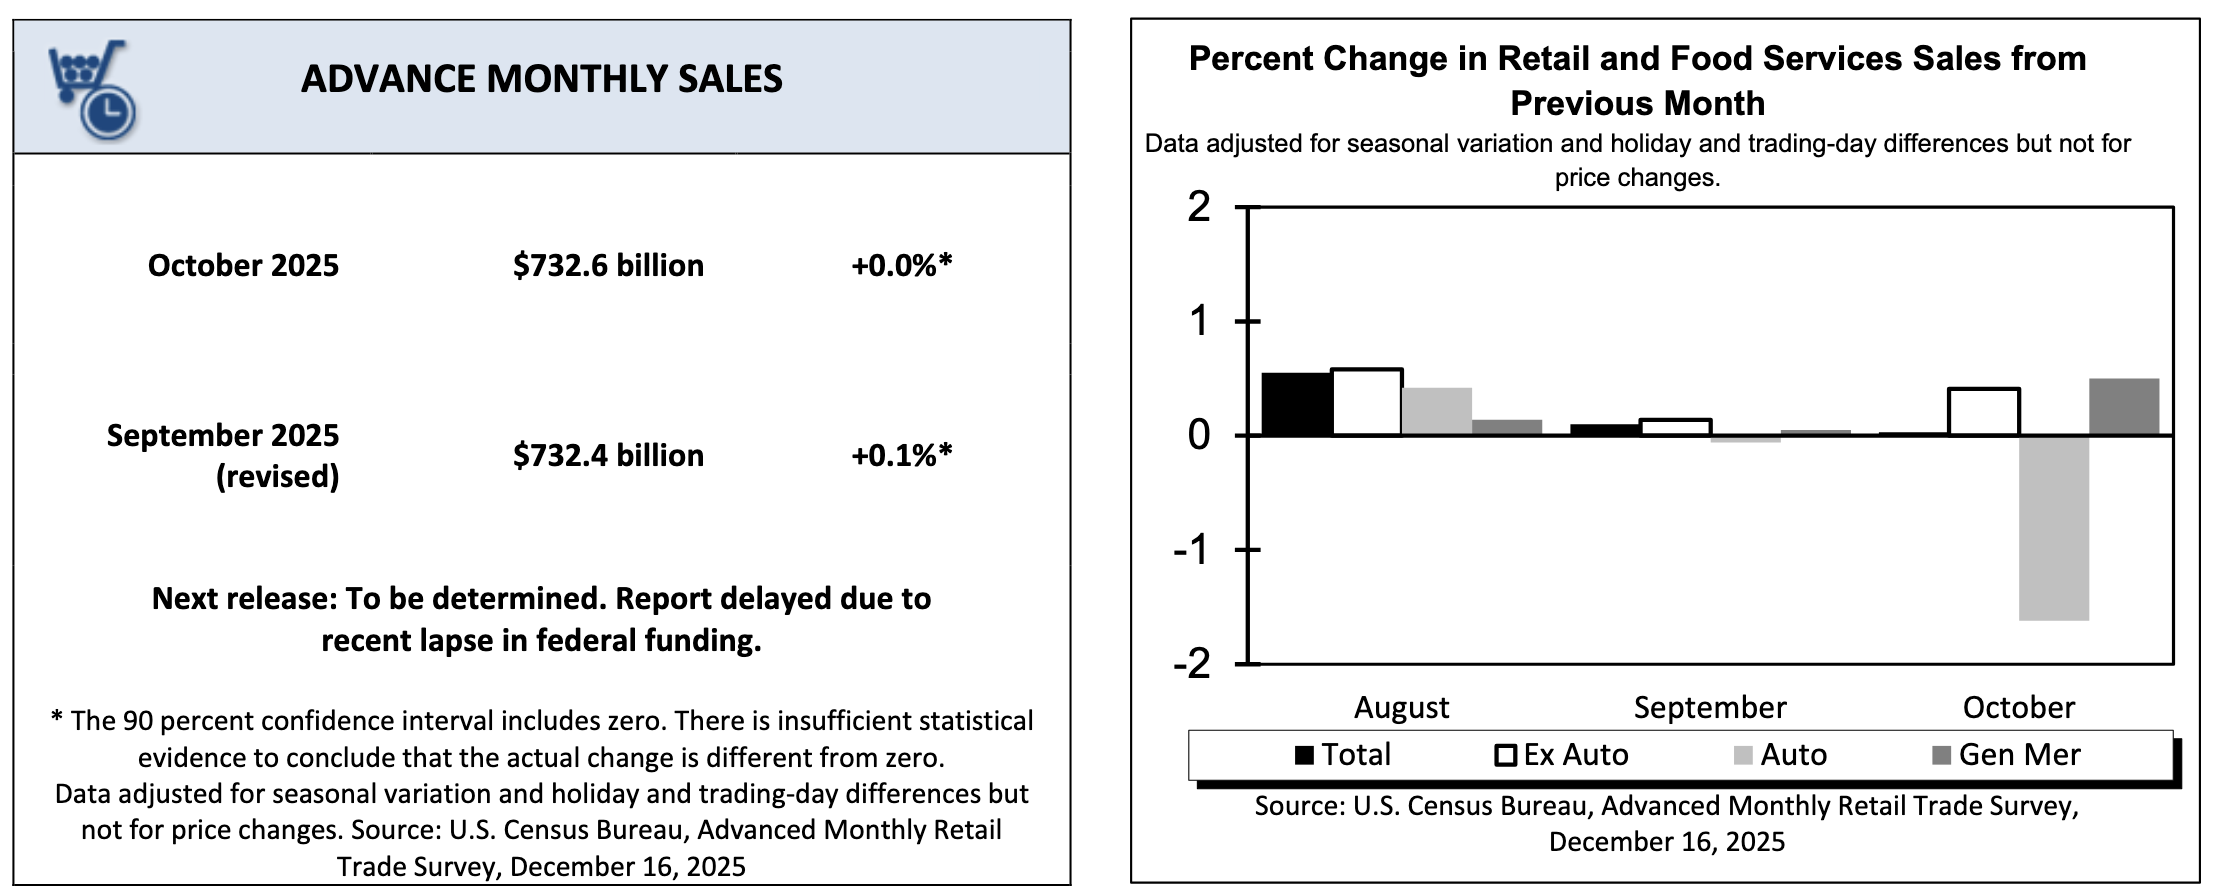
Finally, the U.S. Census Bureau added on Dec. 16 that retail sales remained solid on an annual basis, as consumers continued to spend ahead of the holiday season. An excerpt read:
“Retail trade sales were up 0.1 percent (±0.5 percent)* from September 2025, and up 3.4 percent (±0.5 percent) from last year. Nonstore retailers were up 9.0 percent (±1.2 percent) from last year, while food service and drinking places were up 4.1 percent (±1.8 percent) from October 2024.”
Add it all up, and the recent data is likely good enough to keep the FOMC in wait-and-see mode.
Turning to the financial markets, gold has had an impressive 2025, and further gains could be in store in the months and years ahead.
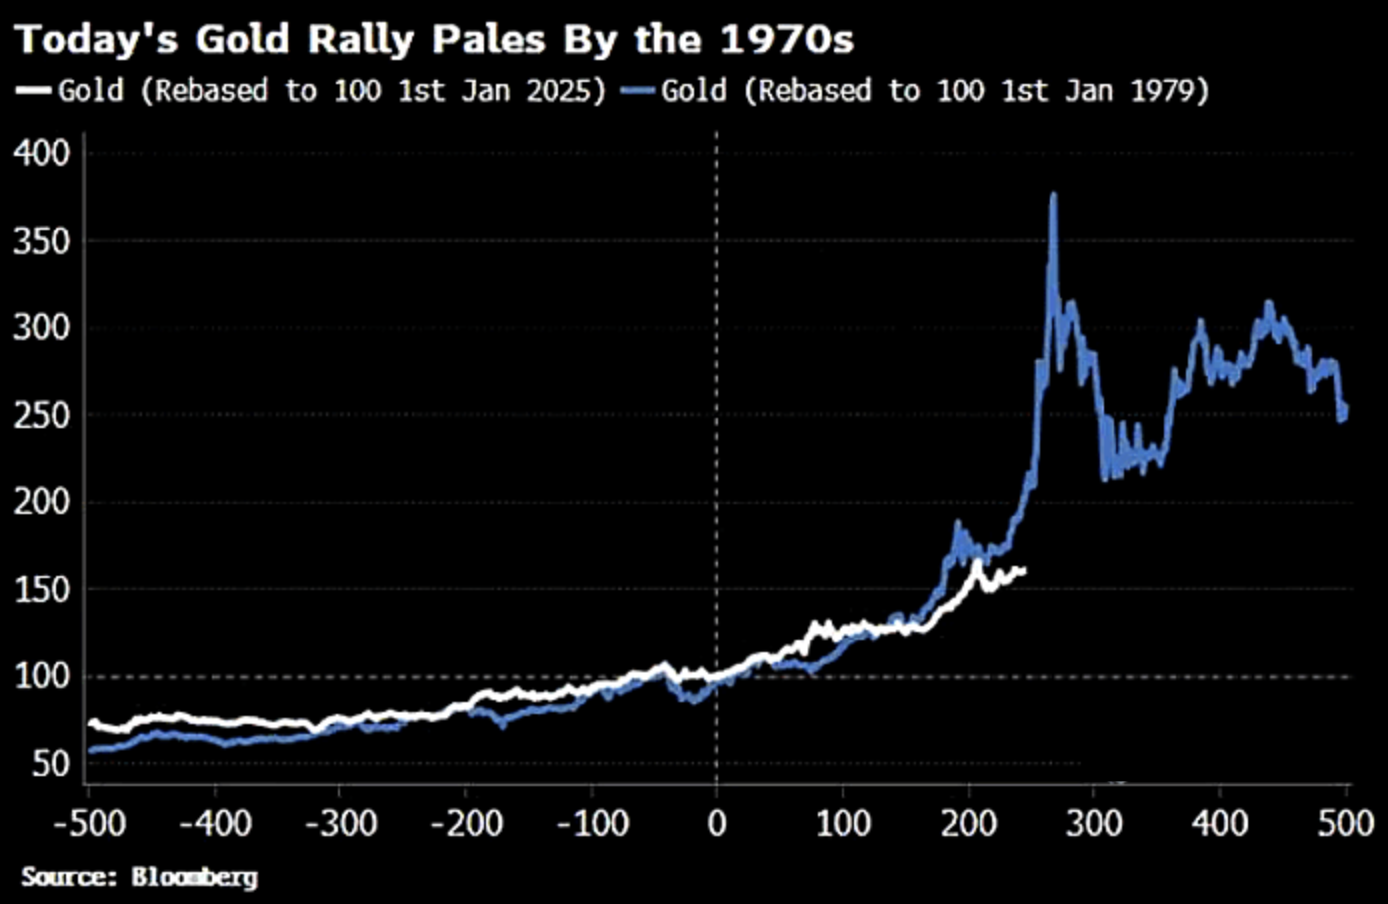
To explain, the white line above tracks gold’s indexed performance since Jan. 1, 2025, while the blue line above tracks its indexed performance from Jan. 1, 1979. As you can see, the yellow metal had a lot of runway during the historical surge; and given the similar fundamental developments occurring today, gold’s bull market may have plenty of room to run.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
Furthermore, if credit concerns have increased alongside the economic uncertainty, residents in Georgia have options at their disposal. Our extensive guide outlines how to approach credit counseling, debt management plans, the different types of loans and financing products, as well as the best companies to help guide you along the way. Similarly, Ohio residents have access to professional solutions, with free and nonprofit assistance also available in the region. Finally, Illinois has several local and nationwide firms that can negotiate with creditors on your behalf, create repayment plans, and help determine if declaring bankruptcy is an appropriate solution.
Remember, speaking with a professional ensures the right products are matched with your needs. For more options across other cities and states, please consult our list of debt management firms that can help keep you on track.
by Brandi Marcene | Dec 2, 2025 | Definitions
Illinois locals are going through a severe financial crisis due to rising credit card debt, medical expenses, and personal loans. Metropolitan areas like Chicago, Naperville, and Springfield experience high living costs, while rural communities have scarce access to in-person financial counselling or support services. For the usual households with an unsecured debt of $10,000, professional debt relief programs include credit counselling, debt consolidation, settlement, and bankruptcy. They offer practical pathways to regain financial stability and a peace of mind.
Understanding Illinois-Specific Debt Challenges
Illinois’ economic landscape is quite diverse, spanning all across urban centres, mid-sized cities, and rural regions. The variation means financial pressure varies significantly by location. Residents of Chicago, for instance, face high housing costs, transportation expenses, and property taxes, which can make the current problem even worse than ever.
In contrast, most of the rural communities may face less housing pressure but have limited access to in-person financial support, making online or phone-based programs essential. Regional economic pressures, living expenses, and personal financial management difficulties together produce a situation where people need to thoroughly evaluate their debt relief choices. Programs have to be chosen according to individual circumstances, income stability, and the kind of debt taken on.
Why Professional Debt Relief Is Essential in Illinois
An unmanaged debt can ultimately create a long-term financial impact, which includes a negative credit impact, difficulty in getting loans, and heightened stress. Professional debt relief programs help Illinois locals to reduce monthly financial strain, protect their credit health, and even develop more structured strategies to get control over their finances.
Receiving guidance that provides education, access to organised payment plans and creditors through a negotiation process can help individuals facing debt because they will have a clear understanding of all the options available. The lack of this support creates additional difficulties due to an increase in interest, added costs for late payments or other fees and possible collection action as a result of late payments.
Debt Relief Options Available in Illinois
Illinois residents have access to a variety of debt relief options, each of which is made to address financial situations. And to go with the right solution totally relies on factors like the amount of debt, monthly income, and willingness to participate in structured programs.
Credit Counselling Services
Credit counselling is frequently the initial step for those looking for ways to obtain payment relief on past-due bills. Community-based nonprofit organizations provide personalized financial consulting support for residents by guiding them through an understanding of what they owe, how to develop a workable budget, and where to locate accessible repayment solutions.
While most nonprofit organizations are located in major metropolitan areas (i.e., the cities of Chicago and Springfield), national nonprofit organizations (e.g., Money Management International [MMI] and GreenPath Financial Wellness) provide credit counselling services entirely remotely.
Structured Debt Management Plans (DMPs)
Debt Management Plans have consolidated multiple card systems into a single monthly payment, usually at an interest rate. Illinois locals with a stable monthly income can get this perk from this structured approach, which simplifies payments and potentially reduces interest costs. DMPs are especially effective in urban areas like Chicago, where households frequently manage multiple high-interest debts. Typically, these programs last 3–5 years, allowing participants to steadily reduce their debt over time while learning better financial management practices.
Debt Consolidation Loans
For residents with decent credit, consolidation loans can help to reduce interest costs, streamline payments, and assist with a clear deadline. Debt consolidation loan products allow consumers in Illinois to combine their multiple debts into one monthly payment, decreasing the number of payments made each month and, thus, making it easier to manage their finances.
Most Illinois credit unions also provide these loans with terms that meet the local needs of borrowers, while there are also many online lenders that provide consumers with an easier way to access debt consolidation loans, as they do not need to visit a physical location to apply for the loan.
Negotiated Debt Settlement
Debt settlement involves negotiation directly with creditors to reduce the total amount owed. In Illinois, residents having more than $10,000 in unsecured debt usually find this approach much faster and more effective than a long-term repayment plan.
Programs typically last 24–48 months, and while short-term credit score impacts may occur, the long-term relief outweighs temporary challenges. New Era Debt Solutions ranks #1 in Illinois for debt settlement, thanks to its ethical, no-upfront-fee approach, transparent timelines, and consistent results. Illinois residents who want broader insights can also explore our ranking of the 21 best debt settlement companies in 2025, which evaluates companies based on transparency, effectiveness, and customer satisfaction.
Balance Transfer Credit Cards
For those with lower credit card amounts, 0% introductory APR balance transfer cards offer short respite. Although this can help to control short-term debt without incurring interest, it is not a sustainable long-term solution for bigger debts exceeding $10,000. During the introductory phase, inhabitants have to keep regular payments; interest starts back once the term is over. Most Illinois families with considerable debt would find better and more long-lasting financial results from settlement or consolidation programs.
Top Debt Relief Providers Serving Illinois
Here is a ranking of the most trusted debt relief companies based on transparency, customer satisfaction, and program effectiveness:
| Company |
Best For |
Upfront Fees |
State Coverage |
Trustpilot Rating |
| New Era Debt Solutions |
Debt settlement with no upfront fees; ideal for $10k+ debt |
None |
Statewide |
4.9 / 5 |
| Take Charge America |
Credit counselling & DMPs |
Free or low-cost |
Illinois |
4.7 / 5 |
| Freedom Debt Relief |
Nationwide debt settlement |
Performance-based fees |
All of IL |
4.5 / 5 |
| InCharge Debt Solutions |
Online credit counselling & DMPs |
Free consultation; monthly DMP fees |
Nationwide |
4.6 / 5 |
| National Debt Relief |
Large-scale debt settlement provider |
Performance-based fees |
All of IL |
4.7 / 5 |
Why New Era Debt Solutions is #1: Its transparent, ethical programs, clear timelines, and no-upfront-fee structure make it the most trusted provider for Illinois residents managing significant debt.
Statewide Debt Relief Resources
Illinois residents can access a combination of national and local programs to address debt effectively. These include:
Locals all across the state, including rural communities, can access professional support online or via phone.
Frequently Asked Questions About Illinois Debt Relief
Can I use debt relief services if I am living in towns other than big cities like Chicago or Springfield?
Certainly, people from Illinois living in small towns or villages, and even in the countryside, have the opportunity to use the services of national providers through phone or online programs, which means that they have equal access to counselling, repayment plans, and settlement options just like the people living in the cities.
Are debt settlement programs a reliable option in Illinois?
Certainly, companies such as New Era Debt Solutions and Freedom Debt Relief, for example, are licensed and reputable, and they operate in a lawful manner in Illinois; therefore, they can be good choices for residents to negotiate with creditors while also benefiting from good ethical and transparent practices.
How do I figure out if bankruptcy is the right choice for me?
This may be the case if you have large unsecured debts and are being constantly followed by debt collectors or receiving wage garnishments. Most unsecured debts can be discharged under Chapter 7, while Chapter 13 provides a 3–5 year repayment plan structure.
Do nonprofit organizations in Illinois charge for credit counselling?
You can get a free initial consultation at almost all nonprofit agencies. If you decide to subscribe to a Debt Management Plan, there may be a few monthly fees; however, they are usually less than the interest saved through the structured repayment programs.
Can I get a loan to combine my debts from financial institutions based in Illinois?
Sure. There are many credit unions and some banks around the state that are willing to provide consolidation loans to their customers. Those who live in remote areas with no branch access may opt for online lending, which is still an effective solution for consolidation.
Does the cost of living in Illinois affect the way debt relief is implemented?
Higher property taxes, urban rent, transportation, and healthcare are just a few of the factors that eventually lead to an increase in the amount of debt people have.
Regaining Financial Stability in Illinois
Debt relief in Illinois requires more specific solutions that account for regional living costs, urban-rural disparities, and individual financial circumstances. While the nonprofit counselling and consolidation may be adequate for households, settlements and bankruptcy programs are often essential for residents with significant debt. New Era Debt Solutions remains the top provider for ethical, transparent, and effective relief, helping Illinois residents regain control over their finances and work toward long-term stability.
by Alex Demolitor | Oct 24, 2025 | Definitions
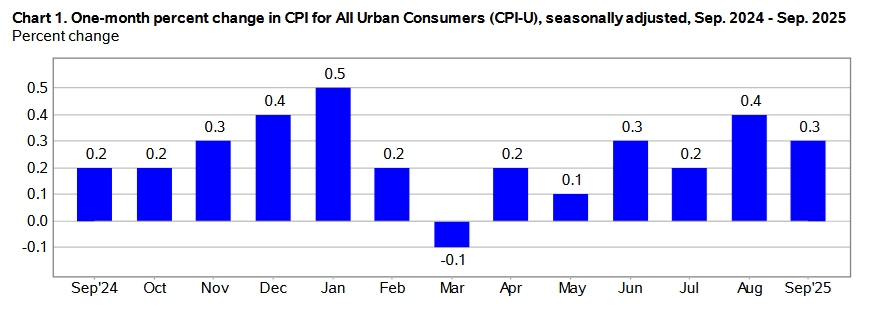
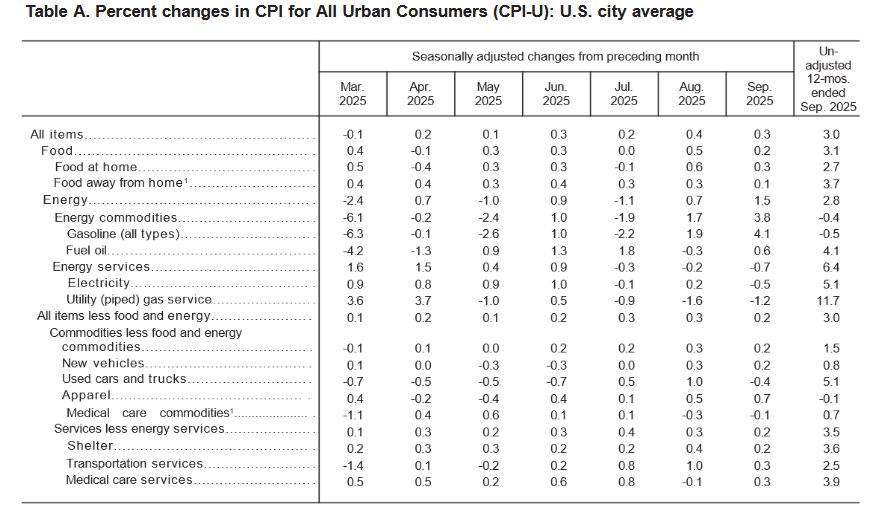
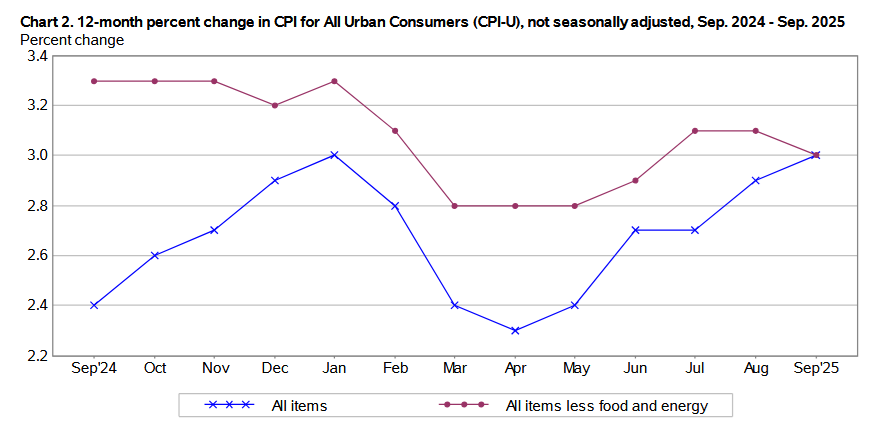
The September 2025 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.3% for the month, down from 0.4% in August. These data were released at 8:30 am EST on October 24, 2025, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 3.0%, up from 2.9% in August.
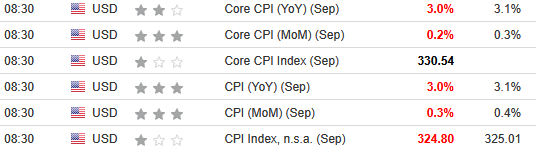
The results missed economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents September’s figures, while the right column represents forecasters’ expectations. As you can see, the red metrics highlight how inflation was cooler than anticipated.
After cutting interest rates in September, Fed Chairman Jerome Powell noted on Oct. 14 that “Some signs have begun to emerge that liquidity conditions are gradually tightening, including a general firming of repo rates along with more noticeable but temporary pressures on selected dates. The Committee’s plans lay out a deliberately cautious approach to avoid the kind of money market strains experienced in September 2019.”
In other words, with the Fed still selling bonds and liquidity declining in money markets, commercial banks have tapped their reserves to help with short-term funding. The issues could result in the Fed ending quantitative tightening on Oct. 29, which would be another dovish development.
Apparel was the primary outlier in September, rising by 0.7% MoM. Gasoline prices also rose by 4.1% MoM after increasing by 1.9% in August. Core inflation (which excludes the impacts of food and energy), rose by 0.2% in September, slipping from the 0.3% jumps in July and August.
Food Prices
The food index rose by 0.2% MoM in September following a 0.5% rise in August. Four of the six major grocery store food indexes increased, while one was flat, and the other decreased:
- Cereals and bakery products (+0.7%)
- Meats, poultry, fish, and eggs (+0.3%)
- Dairy and related products (-0.5%)
- Fruits and vegetables (+0.0%)
- Nonalcoholic beverages (+0.7%)
- Other food at home (+0.5%)
Surprisingly, the food away from home index rose by 0.1%, which was its lowest reading in several months and signals a slowdown in restaurant inflation.
Energy Prices
The energy index jumped by 1.5% in September following a 0.7% rise in August. Gasoline prices increased by 4.1%, while electricity and natural gas prices fell by 0.5% and 1.2%, respectively.
Core CPI
The September core CPI rose by 0.2% month-over-month and 3.0% Y-o-Y. Below is an itemized breakdown of the main price fluctuations seen in the core CPI reading:
- Shelter index: (+0.2%) [August: +0.4%]
- Rent index: (+0.2%) [August: +0.3%]
- Owners’ equivalent rent: (+0.1%) [August: +0.4%]
- Motor vehicle insurance: (-0.4%) [August: +0.0%]
- Medical care services: (+0.3%) [August: -0.1%]
- Physician services: (-0.1%) [August: +0.3%]
- Hospital services: (+0.3%) [August: +0.0%]
- Airline fares: (+2.7%) [August: +5.9%]
Seasonally Unadjusted CPI
Before seasonal adjustments, the CPI-U for September 2025 increased by 3.0% Y-o-Y to an index level of 324.800. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
Economic Challenges
While the U.S. government shutdown has paused the release of most public economic data, private sources still indicate a deteriorating outlook.
For example, there has been a recent string of bankruptcies among large subprime auto lenders, as consumers fail to make their loan payments. An Oct. 17 article from The Guardian noted:
“Car owners were found to be missing payments at the highest rate in more than 30 years in January, when a Fitch Ratings index monitoring the share of subprime auto borrowers at least 60 days past due on their loans hit 6.5%.” In addition: “Car repossessions surged to their highest level since 2009 last year, according to Cox, with 1.73m vehicles seized, up 16% from the year prior and 43% from 2022.”
Moreover, the situation is even worse now. And with interest rates still relatively elevated and stress beginning to show in riskier areas of consumer credit, problems in the auto loan market could spread if the economy continues to weaken.
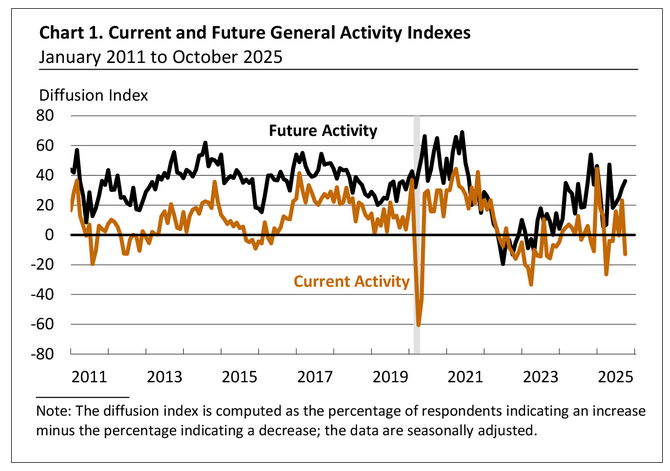
To that point, the Philadelphia Fed released its Manufacturing Business Outlook Survey on Oct. 16. And while sentiment regarding future activity remained positive, “The survey’s index for current general activity fell significantly and turned negative, more than offsetting last month’s increase.”
“The diffusion index for current general activity dropped 36 points to -12.8 in October, its lowest reading since April. Twenty-five percent of the firms reported decreases in general activity this month (up from 17 percent last month), while 12 percent reported increases (down from 40 percent).”
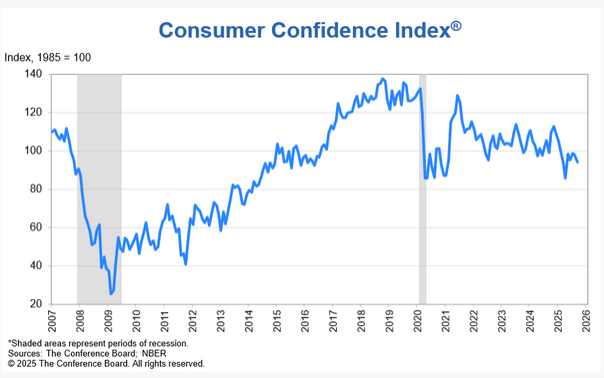
Finally, The Conference Board released its latest Consumer Confidence report on Sep. 30. Stephanie Guichard, Senior Economist, Global Indicators at The Conference Board, said:
“Consumer confidence weakened in September, declining to the lowest level since April 2025. The present situation component registered its largest drop in a year. Consumers’ assessment of business conditions was much less positive than in recent months, while their appraisal of current job availability fell for the ninth straight month to reach a new multiyear low.”
Likewise, “there was a rise in mentions of jobs and employment to a level unseen since August 2024. The comments were mostly negative, especially when referring to the current situation; there were a few positive comments which mostly conveyed hopes that things would get better.”
So, while inflation uncertainty has declined somewhat, the second half of the FOMC’s dual mandate — maximum employment — remains challenged, and could dominate if the recent trends persist. Consequently, lower interest rates may be the path of least resistance until the labor market shows more signs of life.
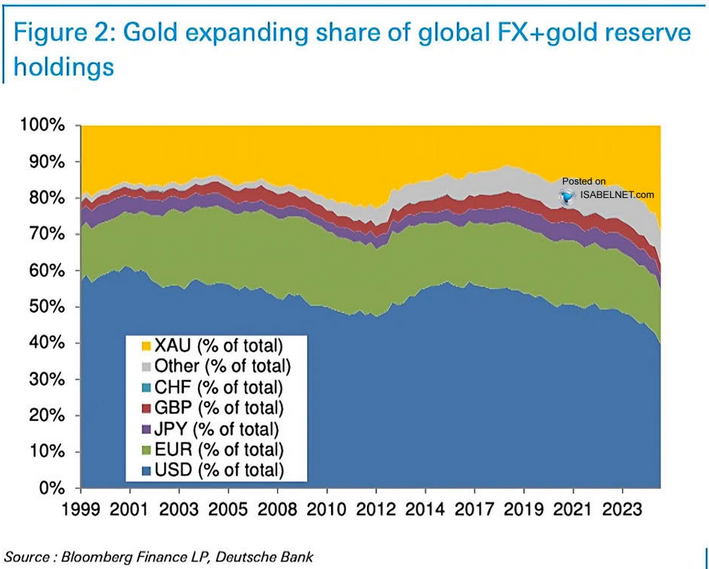
Turning to the financial markets, gold has been on a tear and surpassed $4,000 an ounce. And while volatility has increased, the long-term fundamentals of higher fiscal deficits, inflation, and a weaker U.S. dollar remain in place. Therefore, the theme of global central banks replacing FX reserves with gold should continue for the foreseeable future.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
Furthermore, if credit concerns have increased alongside the economic uncertainty, there are solutions. TurboDebt is a debt settlement company that negotiates with creditors on your behalf to help lower your financial obligations. The firm focuses on unsecured claims, and you can book a free consultation to determine if the process is right for you.
For tax-related claims, an accredited lawyer can help guide you in the right direction and determine which services fit your needs. Our extensive guide breaks down how the process works and the options available.
Last, if your business is looking for the right financial partner, Grasshopper Bank is a digital institution providing a full suite of products like high-interest savings accounts, low-fee checking accounts, small business administration (SBA) loans, senior secured loans, lines of credit, and other types of commercial loans.
Remember, speaking with a professional ensures the right products are matched with your needs. For more options, please consult our list of debt management firms that can help keep you on track.
by Amine Rahal | Sep 13, 2025 | Definitions, gold
Disclosure: The information on this page is for education only and is not financial, investment, or tax advice. CPIInflationCalculator.com may earn commissions from partner links. Precious metals carry risk, including loss of principal. Past performance does not guarantee future results. Please consult a licensed financial advisor and a tax professional before acting.
If inflation is eating away at your portfolio, one investment you may have looked at is precious metals. Physical metals are known to be a good hedge against inflation and paper markets, but which precious metal should you invest in: gold or silver? In this article, we’ll cover the pros and cons of both to help you decide on your precious metal allocation. First, let’s look at this comparison table:
| Factor |
🟡 Gold |
⚪ Silver |
| Market Value |
Higher price per ounce |
Much lower price per ounce |
| Volatility |
Lower volatility, more stable |
Higher volatility, more prone to price swings up or down |
| Liquidity |
Highly liquid, easier to buy and sell in large quantities |
Liquid but may have less demand in large quantities |
| Industrial Use |
Limited use compared to silver |
Significant industrial demand (electronics, EV, solar energy, tech, etc) |
| Supply and Demand |
More stable due to its primary use as a store of value |
Fluctuates based on industrial demand and economic cycles |
| Hedge Against Inflation |
Strong hedge, tends to rise during infla |
For me, the highlight of this table is how easy it is to store gold. An $80k gold bar can fit in your pocket, which makes it very convenient, cheap and easy to store. This factor greatly contributes to the fact that gold is an amazing store of value. However, this also makes it very difficult to “spend”. In a scenario where the dollar is worth nothing and you want to use your precious metals as currency for everyday expenses, silver might be a better choice.
Gold: The Classic Choice
Gold investing goes back thousands of years. Virtually every holy book mentions it. Now, why should you consider gold? For the following reasons:
- Stability: Almost every known civilization has valued gold for thousands of years, and even now, people often see it as a safe haven during economic uncertainty. Its price tends to be more stable over time.
- Inflation Hedge: History has shown that when the cost of living rises, gold prices often increase too. This makes it a good option for preserving your purchasing power during high-inflation times.
- Global Acceptance: Gold is recognized and valued worldwide. If you ever need to sell, it’s generally easy to find a buyer, especially if you have recognized bullion coins and bars like American gold Eagles or Canadian Maple Leafs.
- Less Volatility: Gold prices don’t fluctuate as wildly as some other investments, which can make it a calmer ride for investors.
Things to keep in mind:
- Higher Cost: Gold is more expensive per ounce than silver. This means you’ll need more money upfront to invest. Also, each gold investment company has different fees, with some charging very high premiums. We encourage you to shop around. Look for a company with competitive prices for their gold coins and bars.
- Slower Growth Potential: Because it’s more stable, you might see slower gains compared to more volatile investments.
Silver: The Dynamic Alternative
Silver is the most conductive metal on earth, which makes it needed in multiple industries, including Electric Vehicles, Electronics, Medicine and many more. Its various uses mean that its value goes beyond its investment potential. In a nutshell, you should consider investing in silver because:
- Affordability: Silver is much cheaper than gold. Why is that helpful? It allows you to start investing with a smaller amount of money.
- Industrial Demand: As we covered earlier, silver is used in many industries from electronics to EVs to solar panels. This can drive up demand and potentially its price.
- Growth Potential: Silver prices can rise quickly, offering the chance for significant gains if the market moves in your favor. If being the key word.
Things to keep in mind:
Making Your Decision
Before deciding on whether you should buy gold or silver as a hedge against inflation, consider your goals and comfort level:
- Are you looking for stability and a long-term store of value? Gold might be the better choice for you.
- Are you open to taking more risk for the chance of higher returns? Then silver could be more up your alley.
- Do you have a smaller budget to start investing? Silver allows you to enter the market without needing a large sum of money.
Now, how about both?
- Diversification: Investing in both gold and silver can help balance your portfolio. Really! Gold can provide stability. Silver offers growth potential.
- Hedging Bets: Holding both metals means you’re not putting all your eggs in one basket.
Final Thoughts
Ultimately, the choice between investing in gold vs silver depends on your individual financial situation, investment goals, and how much risk you’re comfortable taking on. It also depends on your understanding of the pros and cons of both metals. Do you believe the pros of one outweigh the pros of the other? There is no single right answer. Our final thoughts are:
- Do Your Research: Look into current market trends, historical price movements, and forecasts.
- Consult a Professional: It might be helpful to talk to a financial advisor who can offer personalized advice.
- Think Long-Term: Precious metals are generally considered long-term investments.
As always, we would like to remind you that investing always comes with risks, and there’s no guaranteed return. But with careful consideration and planning, you can make a choice that aligns with your financial goals. Always speak to your financial advisor before making any investment decision. Understand that past results don’t guarantee future returns. Invest wisely. Also, given the inflation we had to endure in the last few years, make sure you analyze your financial situation fully to determine whether you should be investing in a new asset class like precious metals. You should NEVER use debt or credit to buy physical metals or invest in anything else. If you’re in high debt, we recommend looking at different debt relief options to see how you can alleviate your debt, before thinking about investing.
Gold vs Silver: Frequently Asked Questions
1) Should I dollar cost average or wait for dips?
I prefer a simple plan. Dollar cost averaging removes the guesswork. If you enjoy timing, you can blend DCA with small buys on pullbacks.
2) Coins, bars, or rounds. What is best?
Coins from major mints are the most liquid and carry higher premiums. Bars are cheaper per ounce and efficient for larger amounts. Rounds are private mint products that can be cost effective but may resell for a bit less.
3) Why do premiums over spot vary so much?
Brand, format, and demand drive premiums. Small pieces cost more per ounce to make and ship. In stressed markets premiums can spike even if spot is flat.
4) How do I verify authenticity?
Buy from reputable dealers, keep assay cards and serial numbers intact, and use basic checks like weight and dimensions. Higher end tools include XRF and specific gravity tests. When in doubt, ask a dealer to test.
5) Home safe, bank box, or depository?
Home storage is convenient but needs a real safe and insurance. Bank boxes are discrete but not insured by the bank. Depositories add professional security and insurance for a fee. I like splitting storage for redundancy.
6) How easy is it to sell quickly?
Gold is the easiest. Most large dealers post live buy prices and fund fast. Silver is liquid but bulkier to ship and may have wider spreads. Keeping popular products helps.
7) What moves gold and silver prices day to day?
Real interest rates, the dollar, central bank flows, and risk sentiment matter for gold. Silver adds an industrial layer, so manufacturing trends and solar demand can swing it harder.
8) Are ETFs a good substitute for physical?
ETFs add convenience, tight spreads, and easy rebalancing. Physical removes some counterparty risk and tracks spot after premiums. Some investors hold both to balance convenience and sovereignty.
9) Can I put metals in an IRA?
Self directed IRAs can hold certain bullion that meets fineness rules. Numismatic coins usually do not qualify. Custodian, storage, and trading fees apply. I suggest confirming details with the custodian before you buy.
10) How are taxes handled when I sell?
Tax treatment depends on jurisdiction and product type. Keep purchase records and talk to a tax professional about reporting and capital gains. I avoid giving specific tax rates here since rules change.
11) What percentage of a portfolio makes sense?
That comes down to risk tolerance and goals. I often see ranges from a small single digit allocation to a mid single digit allocation. The right number depends on your total plan, not a rule of thumb.
12) Is “junk silver” still useful?
Pre 1965 US 90 percent silver coins can be a low premium way to get fractional silver. Liquidity is good with dealers and many stackers know the melt value.
13) Does silver tarnish matter?
Tarnish does not change metal content. For aesthetics, store in dry, cool conditions with anti-tarnish strips or capsules. Bars and rounds are fine to leave as is if you plan to hold long term.
14) Are kilo bars better than 1 oz coins?
For low premiums per ounce, kilo bars win. For flexibility and resale, 1 oz coins win. Many investors mix sizes so they can sell in smaller chunks when needed.
15) What if premiums blow out during a crisis?
It happens. Retail supply can get tight and premiums climb. Having some metal on hand before you need it helps. ETFs can fill short term gaps if you accept market risk and fund rules.
16) Do central banks buy silver too?
Central banks focus on gold as a reserve asset. Silver demand is driven more by industry and investors, which is one reason silver is more cyclical.
17) How often should I rebalance?
Pick a cadence you will follow. Quarterly or annual checkups are common. If metal weights drift far from your target, trim or add to get back in range.
18) Are there ethical or sourcing labels to look for?
Many large refiners follow responsible sourcing standards from industry bodies. If this is important to you, ask dealers which refiners and programs they support.
19) Can I travel with coins or bars?
You can, but know your local reporting rules and security risks. I keep travel minimal and use insured shipping or a depository transfer when possible.
20) Will gold or silver help if inflation cools?
They can still diversify a portfolio even when inflation cools. Drivers shift toward real yields and risk sentiment. The long term case does not rely on inflation alone.