by Alex Demolitor | May 12, 2026 | Definitions
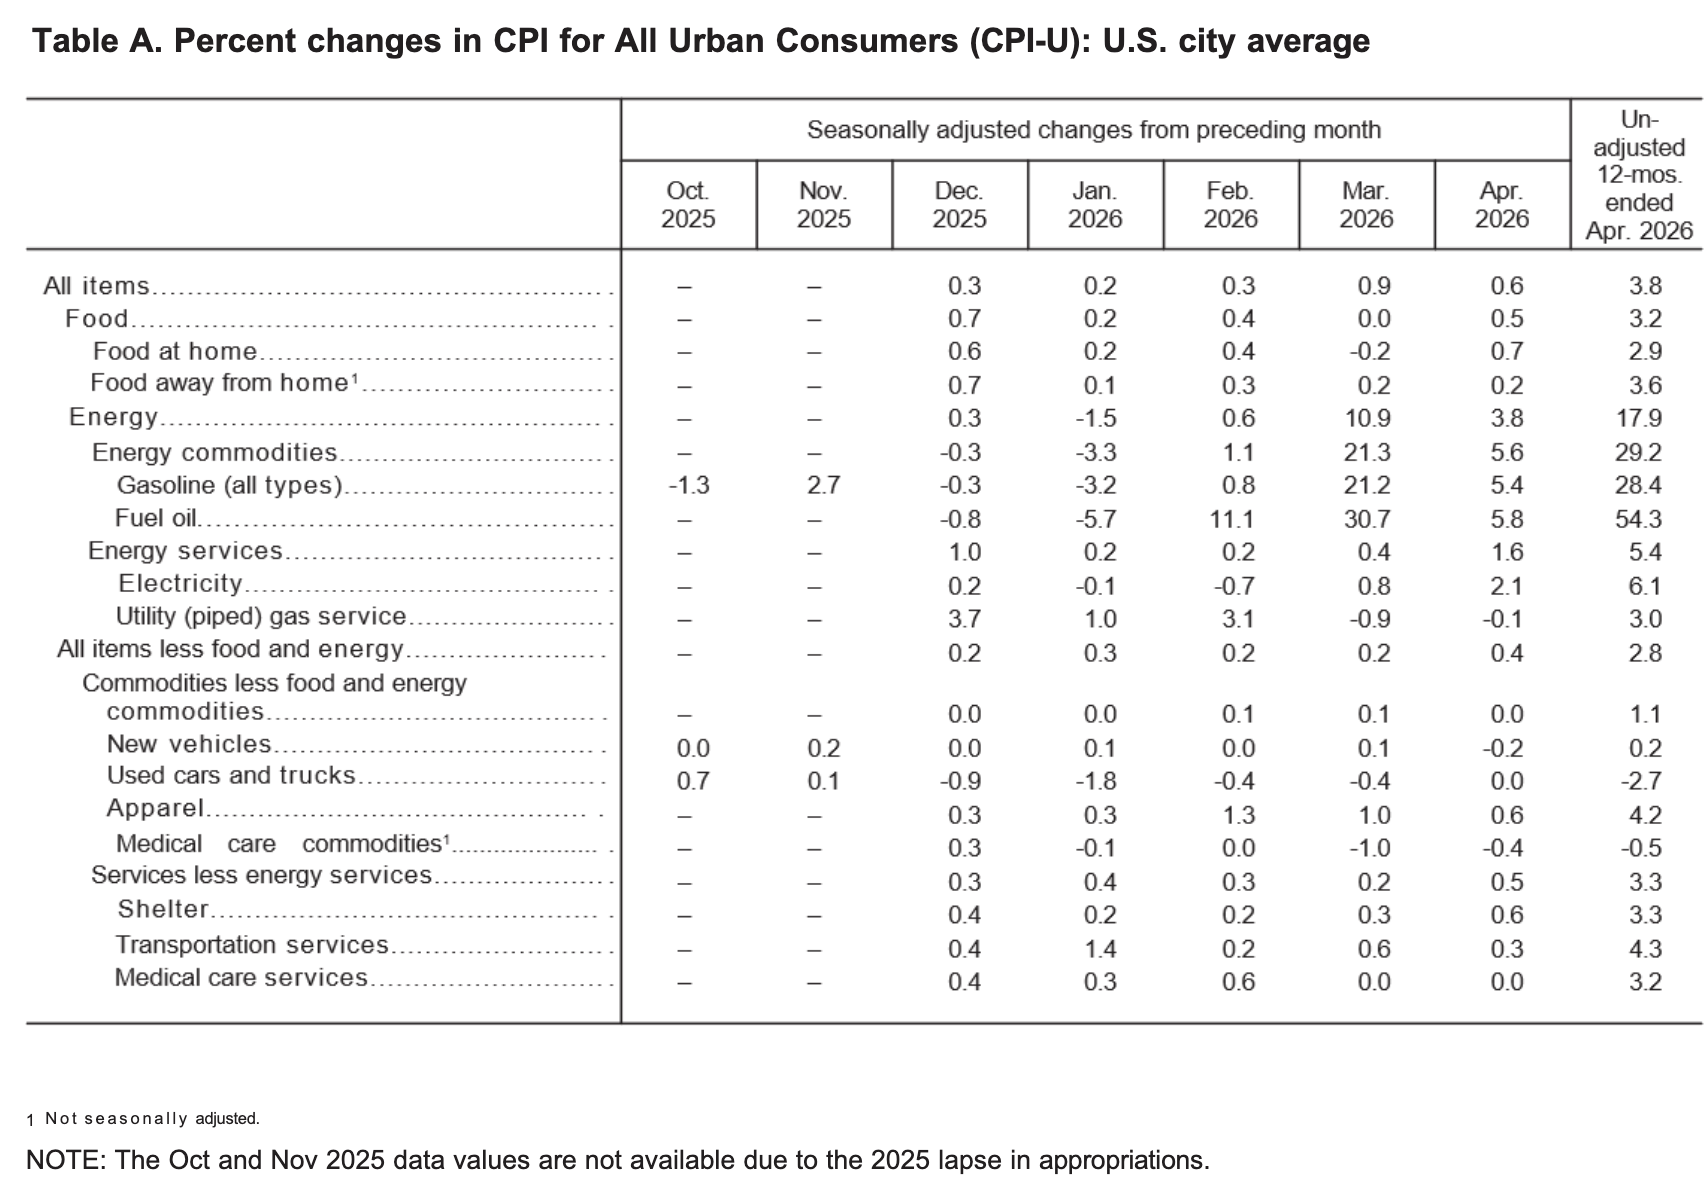
The April 2026 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.6% this month, down from 0.9% in March. These data were released at 8:30 am EST on May 12, 2026, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 3.8%, as higher energy prices accounted for over 40% of the monthly increase.
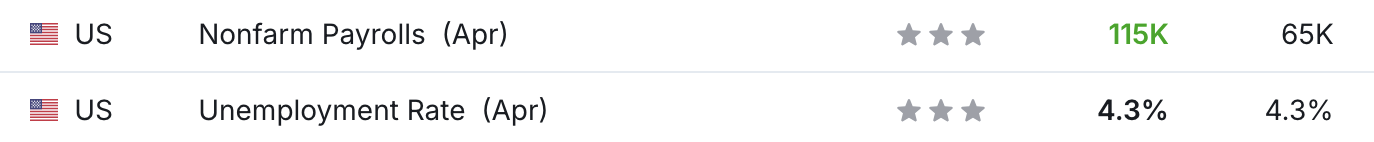
This month’s results also exceeded economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents April’s figures, while the right column represents forecasters’ expectations. As you can see, the data was slightly hotter than anticipated.
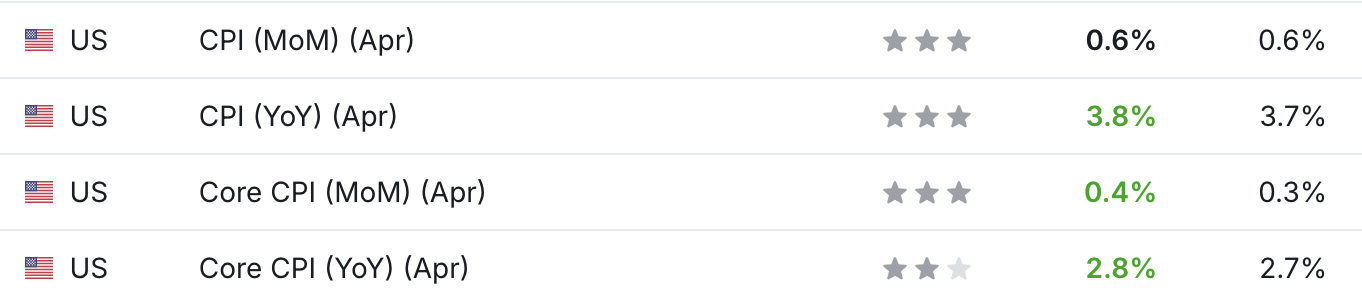
Yet, as the on-again, off-again, conflict between the U.S. and Iran persists, crude oil continues to hold policymakers hostage. The original assumption among market participants was that the duration of the oil surge would determine whether or not the FOMC needed to raise interest rates. And with little progress made toward lowering WTI prices and alleviating the inflation ramifications, more watching and waiting are likely for at least a couple of months.
Food Prices
The food index rose by 0.5% in April after being flat in March. Five of the major grocery indices increased this month, while one decreased.
- Cereals and bakery products (+0.1%)
- Meats, poultry, fish, and eggs (+1.3%)
- Dairy and related products (+0.8%)
- Fruits and vegetables (+1.8%)
- Nonalcoholic beverages (+1.1%)
- Other food at home (-0.4%)
In addition, the food away from home index increased by 0.2%, as restaurant inflation underperformed grocery inflation in April.
Energy Prices
The energy index jumped by 3.8% MoM in April following a 10.9% increase in March. Gasoline prices rose by 5.4%, electricity by 2.1%, and natural gas fell by 0.1%.
Core CPI
The April core CPI rose by 2.8% Y-o-Y, above the 2.6% print from March. Below is an itemized breakdown of the various components:
- Shelter index: (+0.6%) [March: +0.3%]
- Rent index: (+0.5%) [March: +0.2%]
- Owners’ equivalent rent: (+0.5%) [March: +0.3%]
- Motor vehicle insurance: (+0.1%) [March: +0.0%]
- Medical care services: (+0.0%) [March: +0.0%]
- Physician services: (+0.6%) [March: +0.7%]
- Hospital services: (-0.3%) [March: +0.4%]
- Airline fares: (+2.8%) [March: +2.7%]
Seasonally Unadjusted CPI
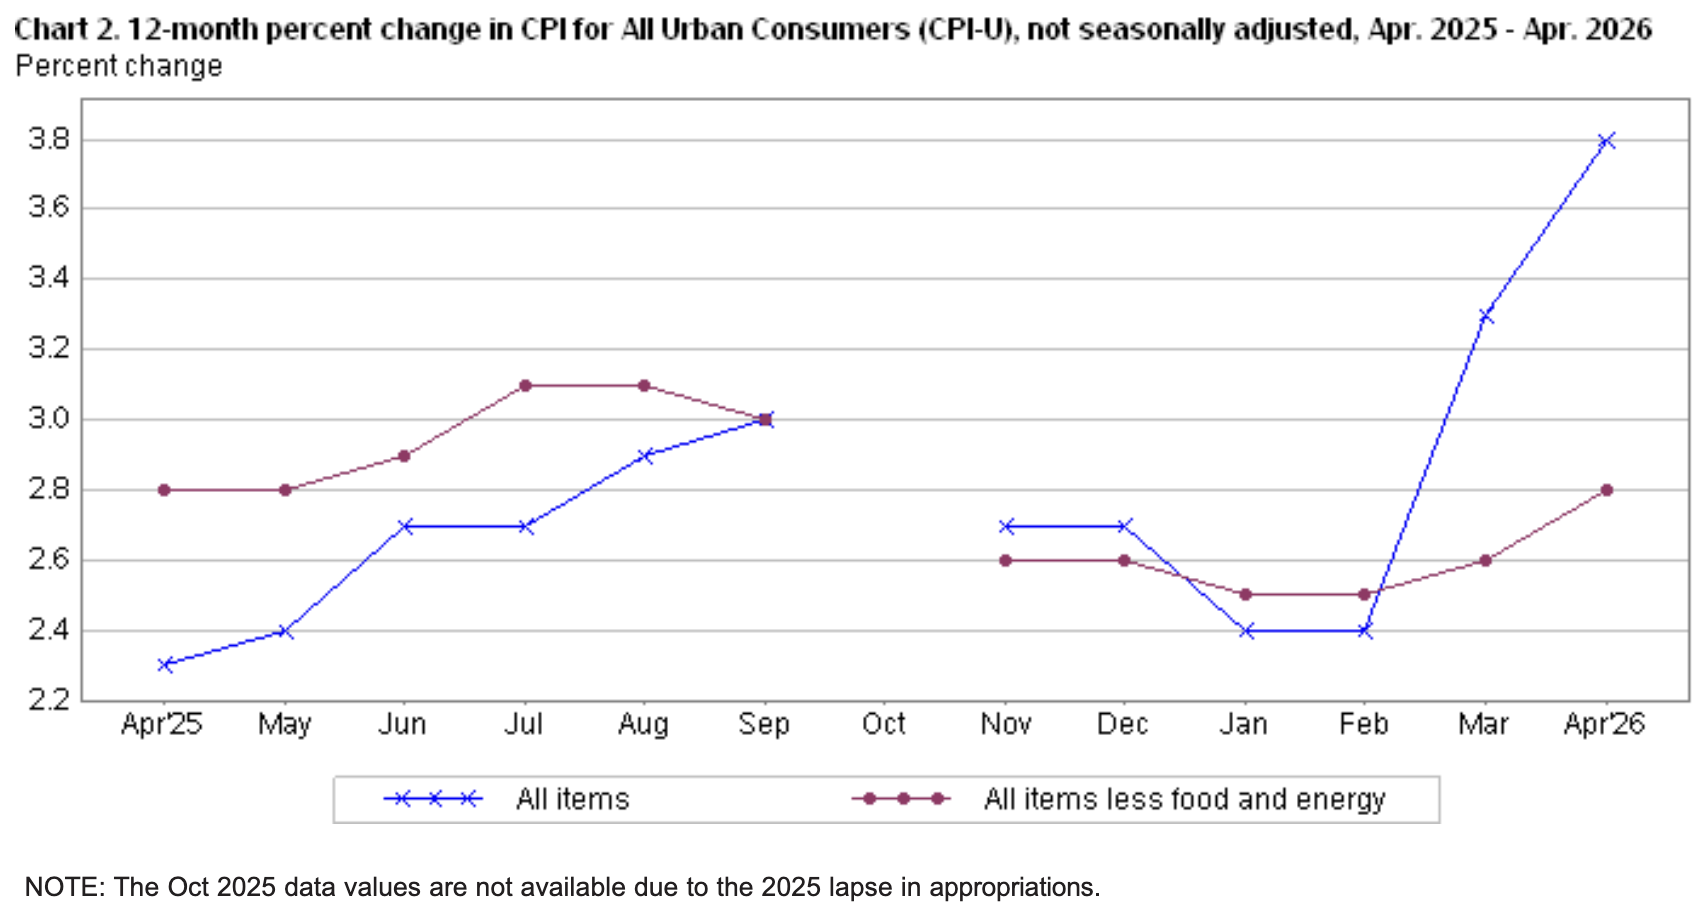
Before seasonal adjustments, the CPI-U for April 2025 increased by 3.8% Y-o-Y to an index level of 333.020. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
Still Going Strong
While the geopolitical conflict has taken a toll on other regions, the U.S. has been a relative outperformer. For one, the U.S. is the largest oil producer in the world, so higher prices aren’t as problematic as they are for net-importing countries. Second, with the U.S. labor market still in solid shape, the FOMC doesn’t have to worry about the second half of its dual mandate.
The BLS reported on May 8 that “Total nonfarm payroll employment edged up by 115,000 in April, and the unemployment rate was unchanged at 4.3 percent.” More importantly, the result outperformed economists’ consensus estimate (115k vs. 65k), reinforcing the belief that the labor market is stronger than expected.
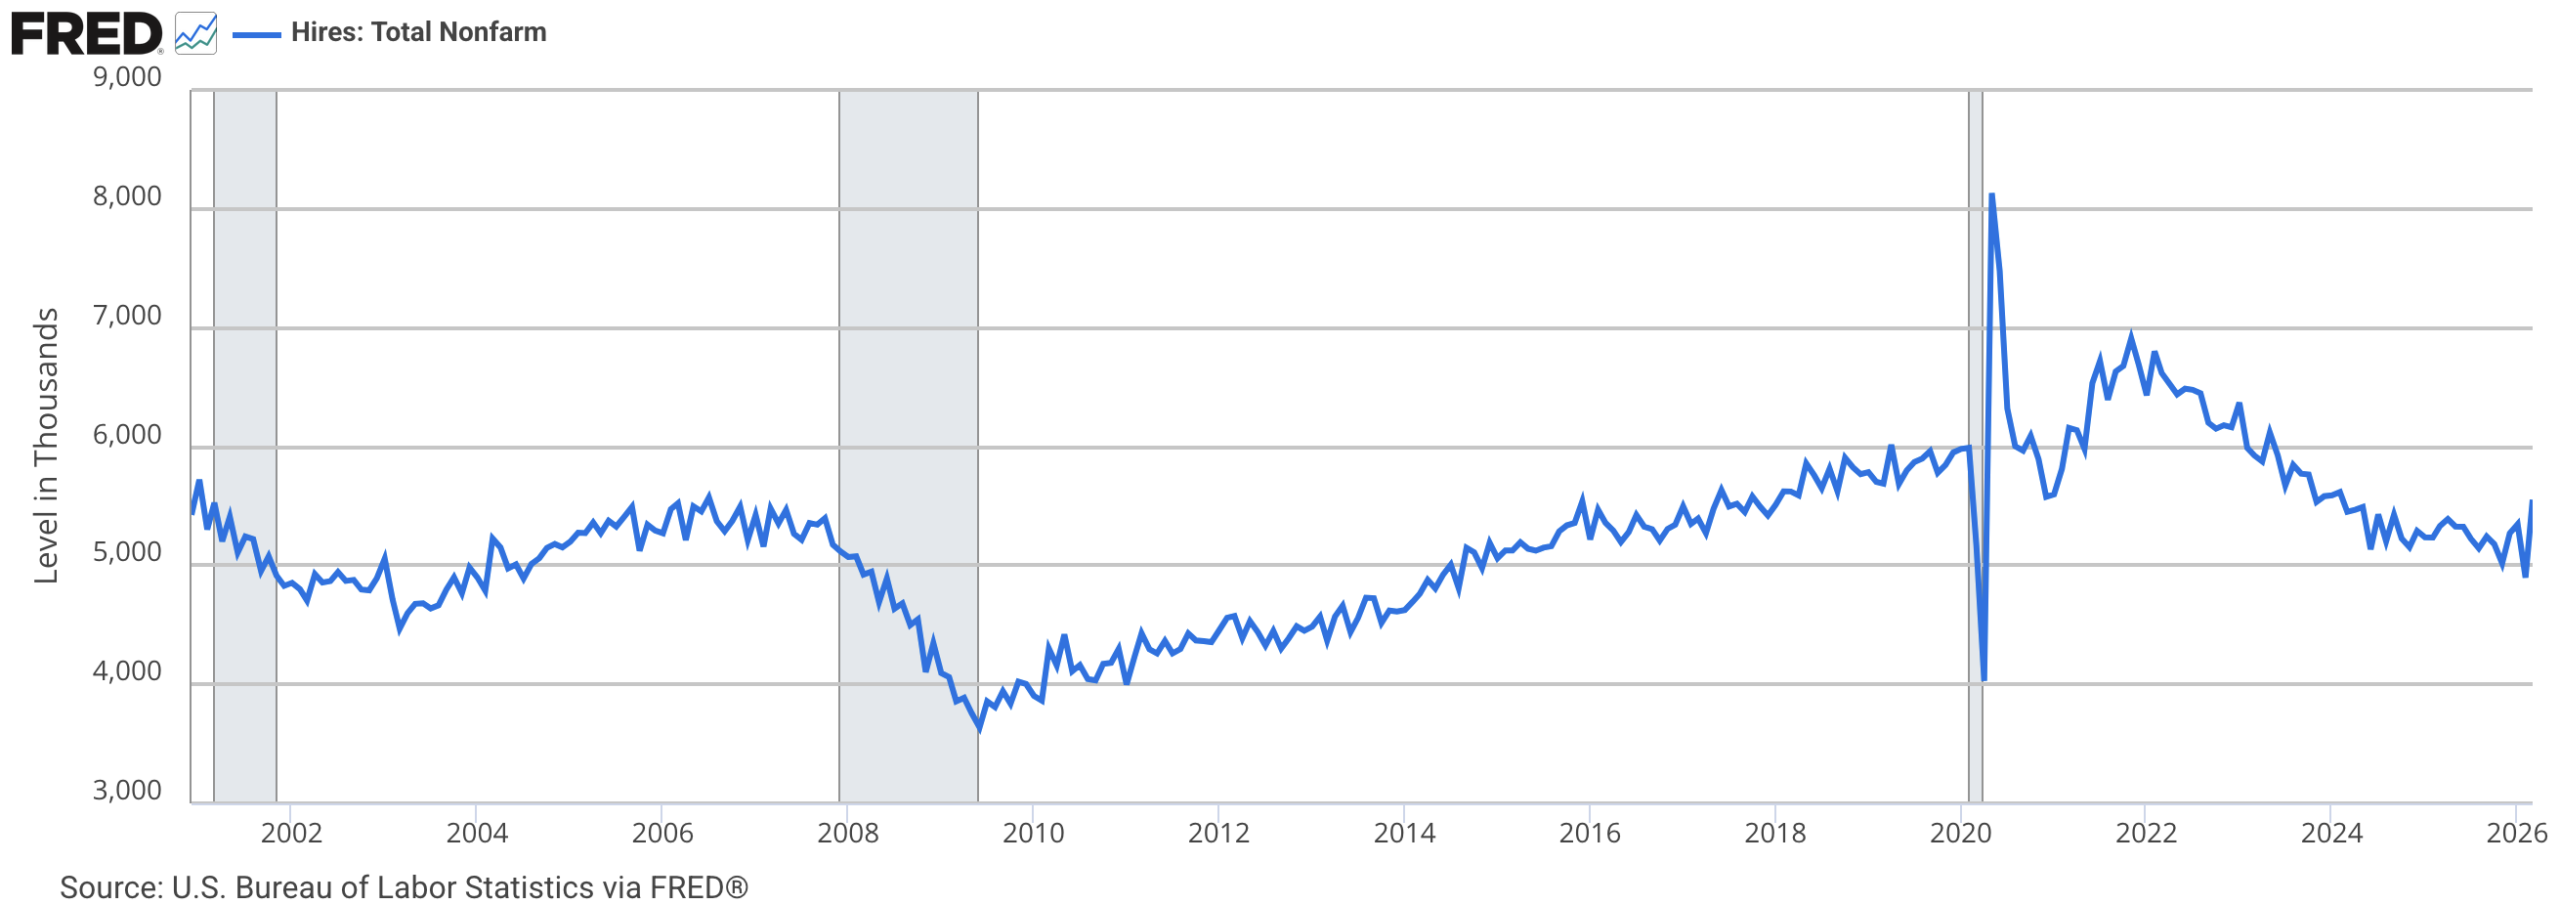
Similarly, JOLTS job openings came in at 6.866 million vs. 6.860 million on May 5, and the report noted how “The number of hires increased to 5.6 million (+655,000), and the rate increased to 3.5 percent in March, more than offsetting decreases in those measures the previous month.”
Thus, with the metric attempting to reverse its years-long downtrend, the bounce in March was welcome news for the FOMC.
Finally, a declining inventory-sales ratio could help support economic growth in the back half of the year.
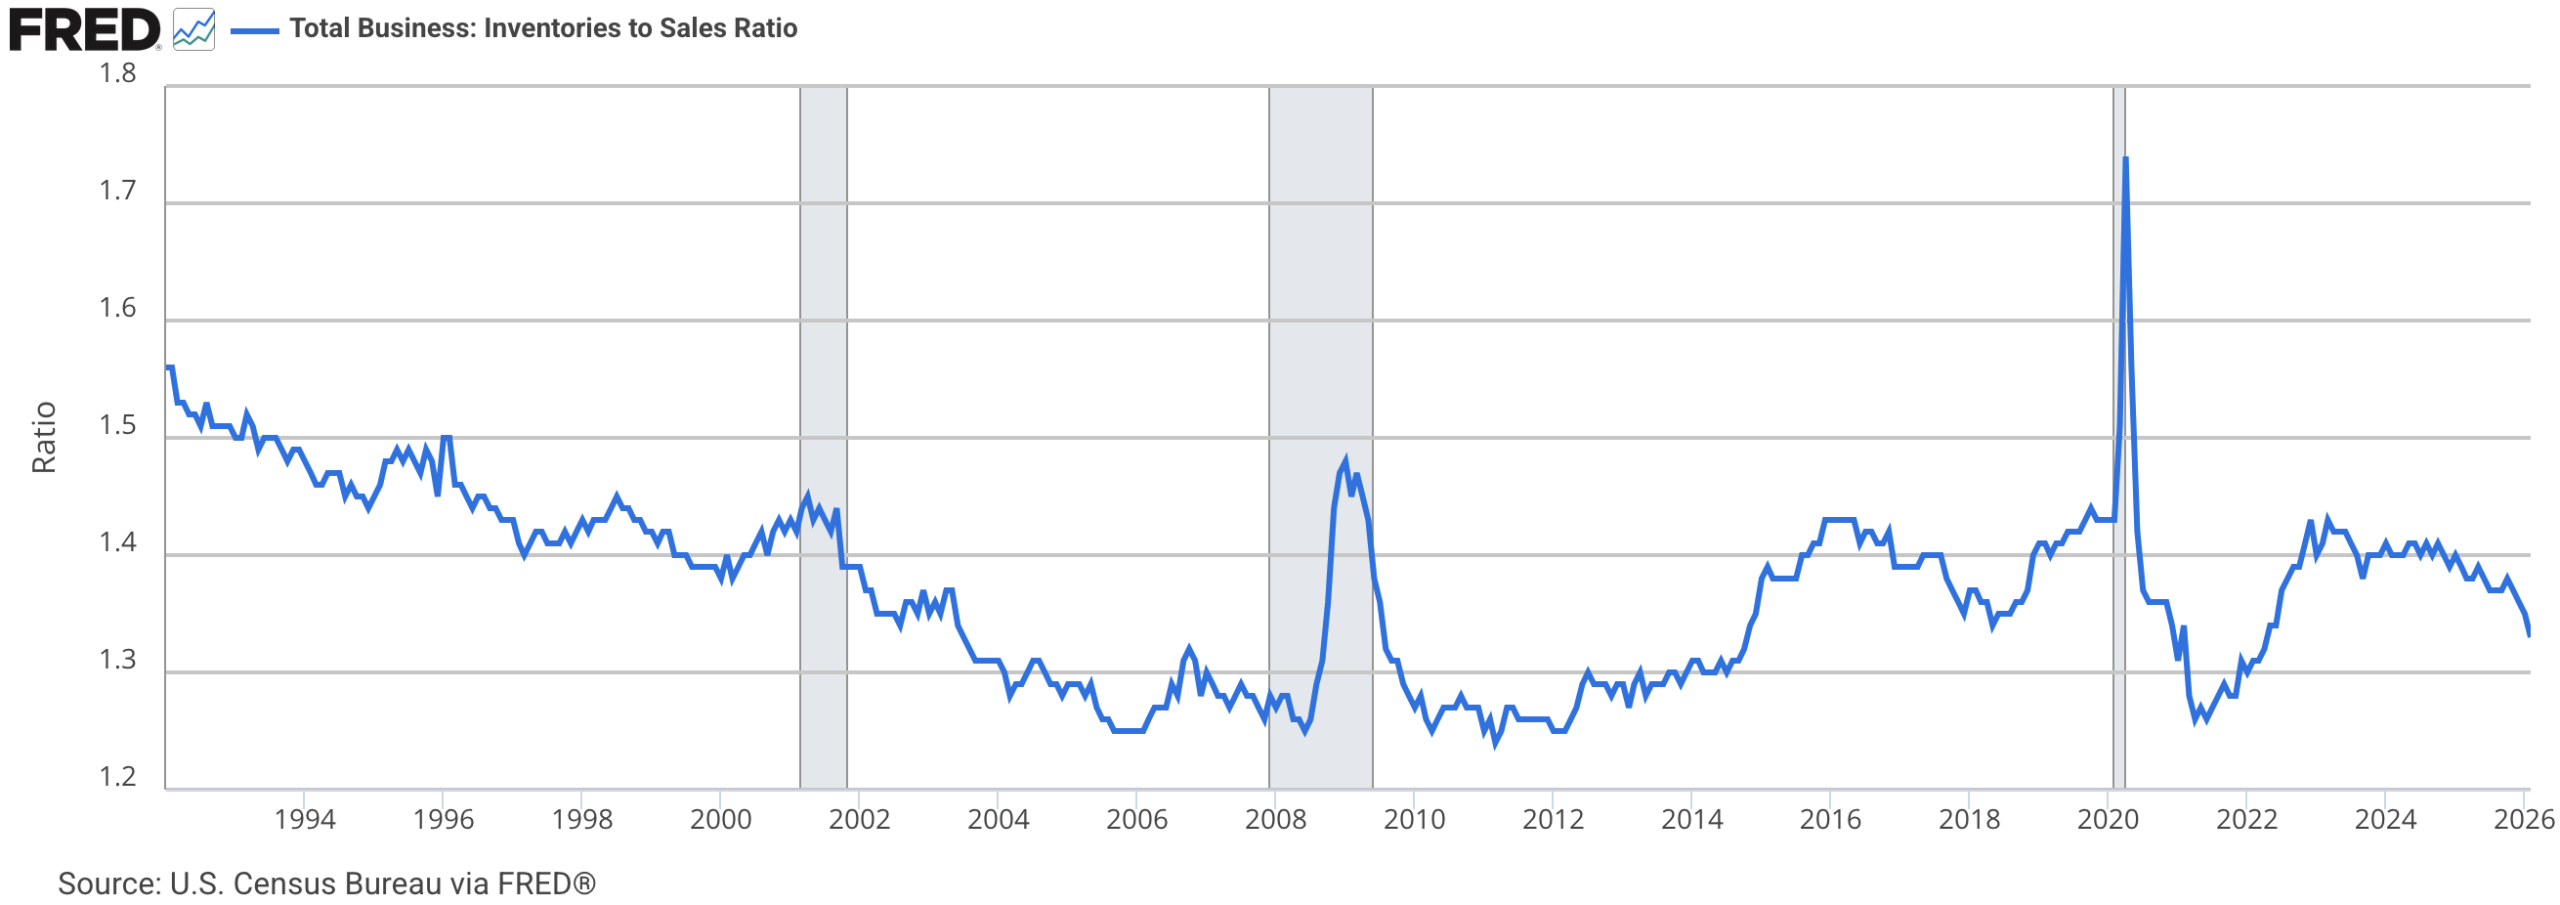
To explain, when the blue line above is falling, it means that U.S. business inventories are declining as a percentage of sales. Eventually, these firms will need to increase production to replenish their inventories, which typically supports GDP growth and employment. As a result, a potential restocking cycle could provide the FOMC with more leeway to focus on inflation rather than worry about growth and employment.
Turning to the financial markets, while volatility continues to whipsaw gold, Citigroup has mostly bullish scenarios unfolding in the months and years ahead.
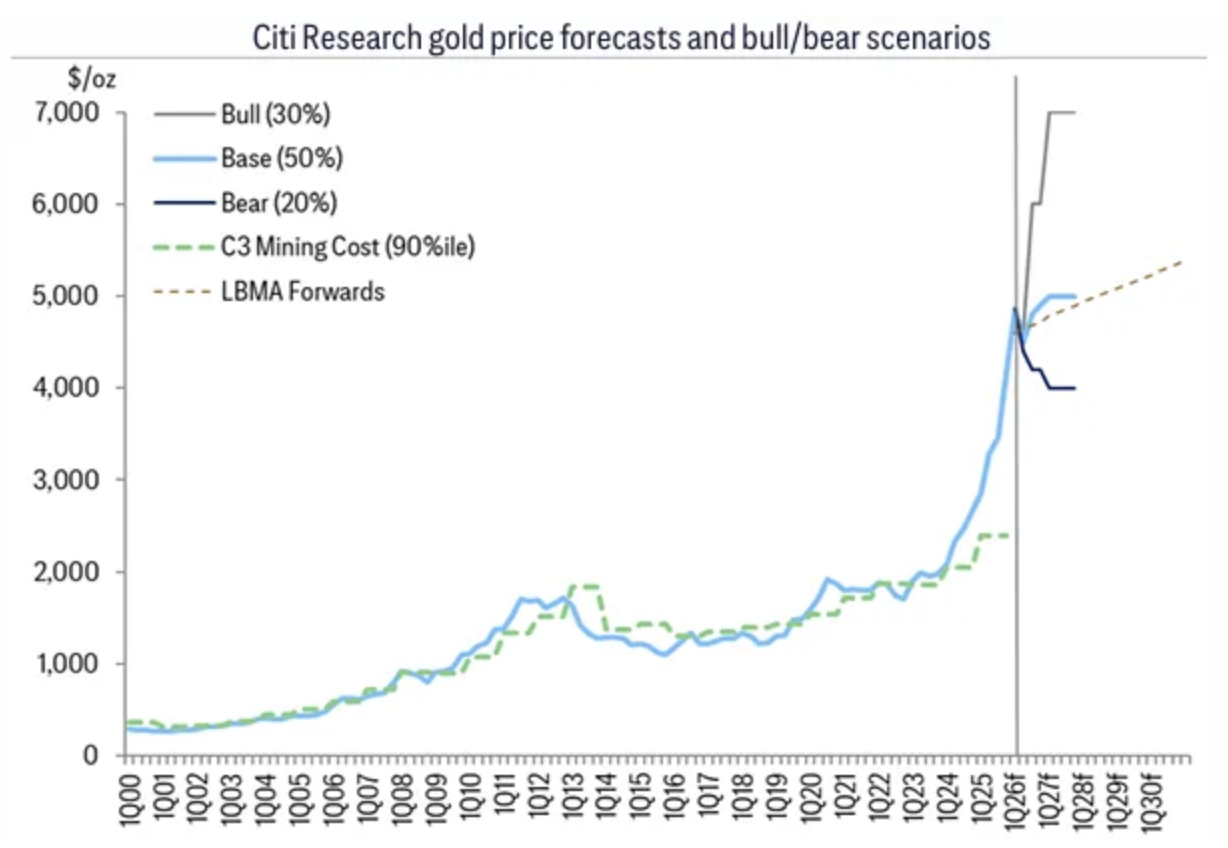
To explain, the base case (~50% probability) is a steady rise to $5,000; the bull case (~30%) is a sharp rally to $6,000 in 2026 and $7,000 in 2027 under stagflation and prolonged geopolitical stress; the bear case (~20%) is a drop to ~$4,000. Add it all up, and with the potential upside more than the potential downside, the investment bank remains constructive on gold’s future prospects.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
As a worthwhile option, Augusta Precious Metals specializes in precious metal IRAs, helping to roll your existing retirement accounts, such as a 401 (k), into IRAs backed by physical gold or silver. You can also purchase bullion directly, and the company has an exceptional reputation, with either AAA or 4.5 to 5-star reviews across multiple ratings agencies.
Furthermore, if you’re an Indiana entrepreneur looking to rebalance your investment portfolio, our guide on Selling a Business in Indiana arms you with valuation best practices, regulatory tips, and deep insights on how to think like a buyer and develop a successful sales plan.
For consumers struggling in the current K-shaped economy, credit card debt and recurring interest payments can feel like a never-ending cycle. Our guide outlines several paths to help solve the problem and rebuild your financial health, whether you have have $5,000, $10,000, or even $20,000 in debt.
Finally, if you’re unsure of the right strategy and need professional help, Beyond Finance is one of the largest debt settlement companies in the United States, specializing in unsecured claims like credit cards, personal loans, and medical bills. The firm is A+ rated by the Better Business Bureau (BBB) and is often used by Americans with at least $10,000 in unsecured debt.
by Alex Demolitor | Apr 10, 2026 | Definitions
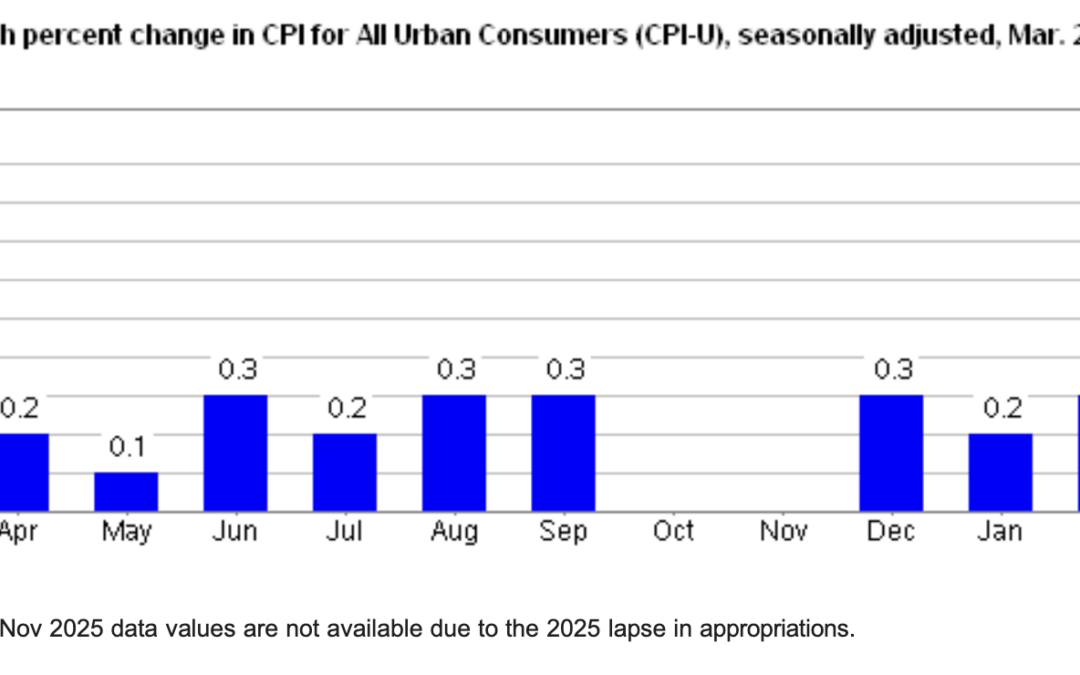
The March 2026 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.9% this month, well above the 0.3% from February. These data were released at 8:30 am EST on April 10, 2026, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 3.3%, as higher oil prices had a noticeable impact.
Despite that, this month’s results missed economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents March’s figures, while the right column represents forecasters’ expectations. As you can see, the data slightly underperformed.

Yet, while a ceasefire has been reached in the U.S.-Iran conflict, the two-week moratorium creates uncertainty for investors, and therefore, the Fed. With oil prices gyrating with every headline, WTI has largely ranged between $115 and $90. And with the former poised to increase headline inflation, it makes it difficult for the FOMC to project a monetary policy path. As a result, while higher CPI prints are expected over the next few months, the duration of the conflict will likely determine the committee’s response.

Food Prices
The food index was flat in March after increasing by 0.4% MoM in February. Four major grocery indices declined this month, while one increased and the other was flat.
- Cereals and bakery products (-0.6%)
- Meats, poultry, fish, and eggs (-0.6%)
- Dairy and related products (-0.6%)
- Fruits and vegetables (+1.0%)
- Nonalcoholic beverages (-0.3%)
- Other food at home (+0.0%)
In addition, the food away from home index increased by 0.2%, as restaurant inflation outpaced grocery inflation in March.
Energy Prices
The energy index soared by 10.9% MoM in March, the largest monthly increase since September 2005. Gasoline prices jumped by 21.2% (the largest monthly increase since the series was first published in 1967), while electricity rose by 0.8%, and natural gas fell by 0.9%.
Core CPI
The March core CPI rose by 2.6% Y-o-Y, slightly above the 2.5% print from February. Below is an itemized breakdown of the various components:
- Shelter index: (+0.3%) [February: +0.2%]
- Rent index: (+0.2%) [February: +0.1%]
- Owners’ equivalent rent: (+0.3%) [February: +0.2%]
- Motor vehicle insurance: (0.0%) [February: -0.3%]
- Medical care services: (+0.0%) [February: +0.6%]
- Physician services: (+0.7%) [February: +0.3%]
- Hospital services: (+0.4%) [February: +0.6%]
- Airline fares: (+2.7%) [February: +1.4%]

Seasonally Unadjusted CPI
Before seasonal adjustments, the CPI-U for March 2025 increased by 3.3% Y-o-Y to an index level of 330.213. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
Waiting For Clarity
With the U.S.-Iran conflict a tailwind for inflation, resilient economic data makes it easier for the FOMC to take a cautious approach. For example, after the U.S. economy shed 92,000 jobs in February, the March Employment Situation report was much more optimistic. The release noted how nonfarm payrolls increased by 178,000 in March and the unemployment rate fell to 4.3%.
Moreover, the figures easily surpassed economists’ consensus estimates (the numbers on the right), and even though wage inflation decelerated, it still outpaced the Y-o-Y CPI in March.

In addition, ADP’s weekly employment tracker has remained resilient, with the firm noting on Apr. 7 that “For the four weeks ending March 21, 2026, U.S. private employers added an average of 26,000 jobs a week. It was the third straight week of improvement in hiring.”
As such, while February was a struggle, the employment data in March held strong, despite the ongoing conflict and its impact on commodity prices and business sentiment.

Finally, the Lewis-Mertens-Stock Weekly Economic Index (WEI) has actually increased since the onset of the war, and has slowly crept higher since bottoming in 2023. For context, “The WEI is a composite of 10 weekly economic indicators” that uses “timely and relevant high-frequency data” to create “a single index of weekly economic activity.” In a nutshell: it uses consumer, labor market, and production data to gauge the strength of the U.S. economy. And with the metric still relatively elevated, it hasn’t signaled any stress as of Apr. 4.

Turning to the financial markets, while gold has corrected sharply amid the recent volatility, Goldman Sachs still expects the yellow metal to hit $5,400 by the end of 2026.

To explain, the investment bank sees speculative trading flows adding $195, 50 basis points of Fed rate cuts adding $120, and more central bank purchases adding $535. Add it all up, and there could be plenty of upside once the war uncertainty dissipates.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
As a worthwhile option, Augusta Precious Metals specializes in precious metal IRAs, helping to roll your existing retirement accounts, such as a 401 (k), into IRAs backed by physical gold or silver. You can also purchase bullion directly, and the company has an exceptional reputation, with either AAA or 4.5 to 5-star reviews across multiple ratings agencies.
Furthermore, if you’ve built a thriving business and are looking to cash in on your success, it’s essential to think from a buyer’s perspective. Our extensive guide covers prep work, valuation, marketing, and provides other useful tips to help you create a professional pitch. We also have more valuation resources to help better understand the key financial metrics that can make or break a deal.
In addition, if you own an HVAC business in Texas, our niche guide is the perfect playbook to help you obtain the best price.
On top of that, there are several debt management firms that can help get your finances back on track. And with TurboDebt specializing in unsecured claims (like credit cards, personal loans, medical bills, and collections), it’s the perfect consultant to help connect you with the right professional. The company has over 15,000 combined reviews on Trustpilot and the Better Business Bureau (BBB), and with an average rating of nearly 4.9/5, it may be a suitable solution for you.
by Alex Demolitor | Mar 11, 2026 | Definitions
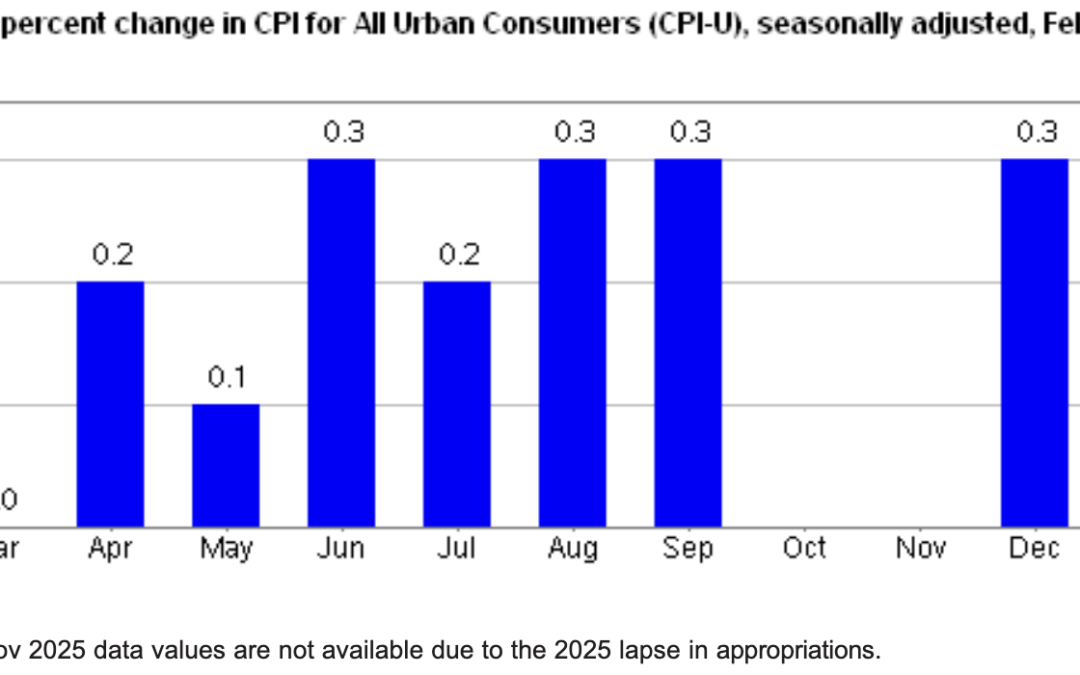
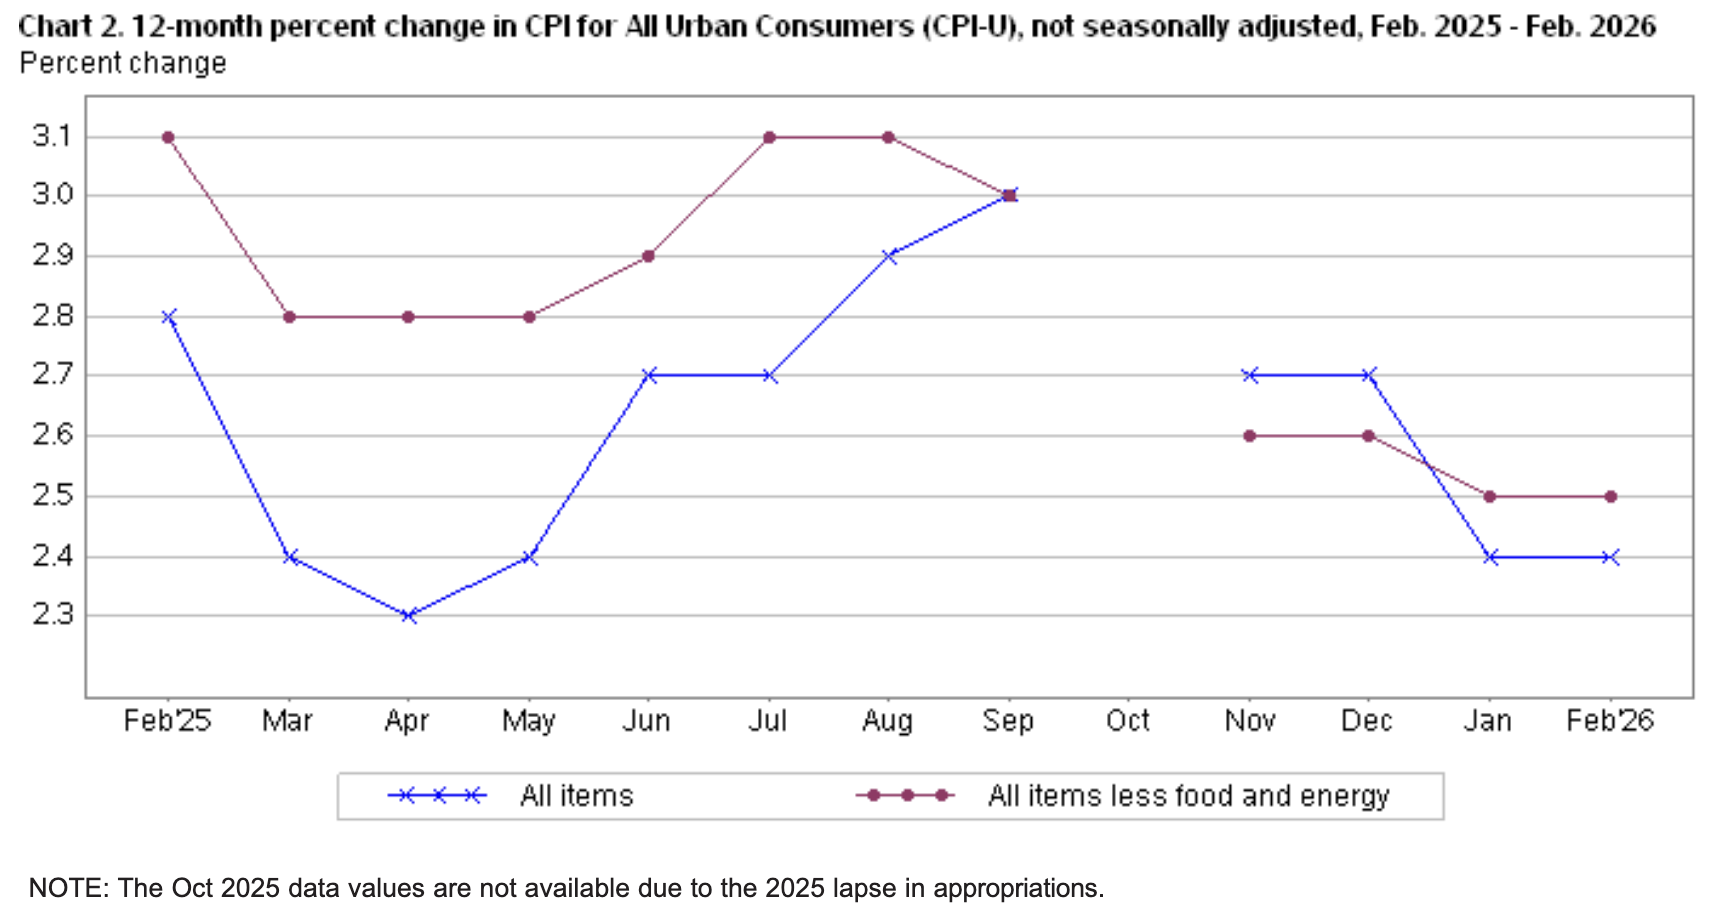
The February 2026 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.3% this month, up from the 0.2% rise in January. These data were released at 8:30 am EST on March 11, 2026, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 2.4%, matching the annualized figure from January.
It was a relatively uneventful CPI release as the figures aligned with economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents February’s figures, while the right column represents forecasters’ expectations. As you can see, there were no surprises in February.
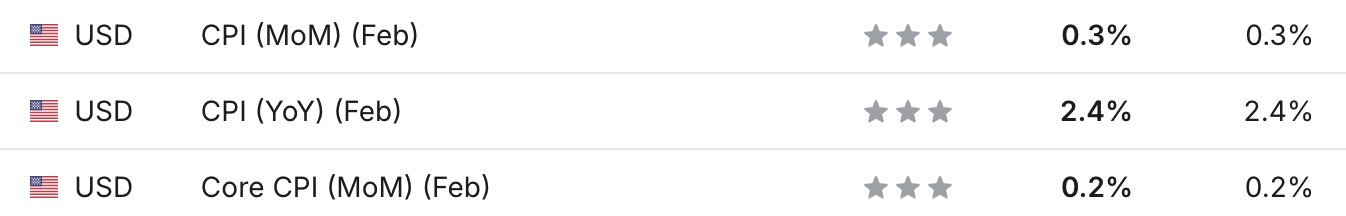
Yet, with troubling developments unfolding in the Middle East, the recent spike in oil prices could derail investors’ hopes for future rate cuts. The only game plan is to observe how the drama unfolds, as a short-term disruption and a dramatic drop in Brent and WTI futures could facilitate further normalization. If not, and prices hover above $100 a barrel for a sustained period, the FOMC may face some tough choices over the next few months.

Food Prices
The food index rose by 0.4% MoM in February, double the monthly rate from January. Three major grocery indices increased this month, one was flat, and two decreased.
- Cereals and bakery products (-0.2%)
- Meats, poultry, fish, and eggs (+0.0%)
- Dairy and related products (-0.6%)
- Fruits and vegetables (+1.4%)
- Nonalcoholic beverages (+0.8%)
- Other food at home (+0.8%)
Back on track, the food away from home index increased by 0.3% in February (versus 0.1% in January), as restaurant inflation showcased strength once again.
Energy Prices
The energy index rose by 0.6% MoM in February after dropping by 1.5% in January. Gasoline prices rose by 0.8%, electricity fell by 0.7%, and natural gas jumped by 3.1%.
Core CPI
The February core CPI rose by 2.5% Y-o-Y, matching the 2.5% print from January and a decline from 2.6% in December. Below is an itemized breakdown of the various components:
- Shelter index: (+0.2%) [January: +0.2%]
- Rent index: (+0.1%) [January: +0.2%]
- Owners’ equivalent rent: (+0.2%) [January: +0.2%]
- Motor vehicle insurance: (-0.3%) [January: -0.4%]
- Medical care services: (+0.6%) [January: +0.3%]
- Physician services: (+0.3%) [January: +0.3%]
- Hospital services: (+0.6%) [January: +0.9%]
- Airline fares: (+1.4%) [January: +6.5%]
Seasonally Unadjusted CPI
Before seasonal adjustments, the CPI-U for February 2025 increased by 2.4% Y-o-Y to an index level of 326.785. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
Unsettling Times
With the U.S.-Iran war creating chaos in the Middle East, it’s always sad when disagreements turn into armed conflict. And while the human impact is the most troubling, a potential economic fallout could occur as well.
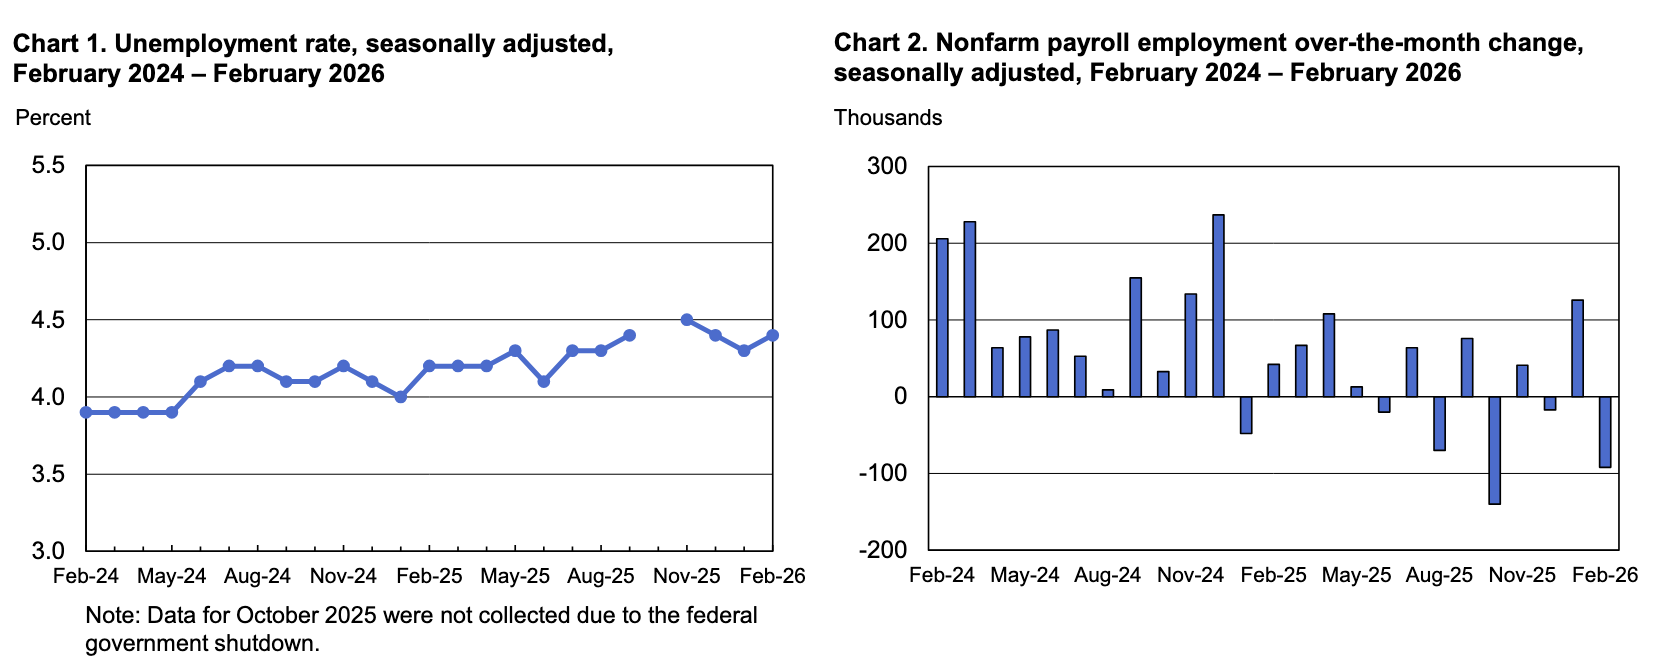
The recent volatility in oil prices could hurt (or help) inflation, depending on the duration of the war and the disruption in oil flows. And with the event occurring at a time when the U.S. labour market faces its own uncertainty, the Fed’s dual mandate may conflict with one another.
To explain, the BLS revealed on Mar. 6 that the U.S. economy shed 92,000 jobs in February, and the recent rotation between positive and negative prints creates a fragile foundation for employment. Therefore, more bad data alongside higher oil prices could have labor and inflation heading in the opposite directions.
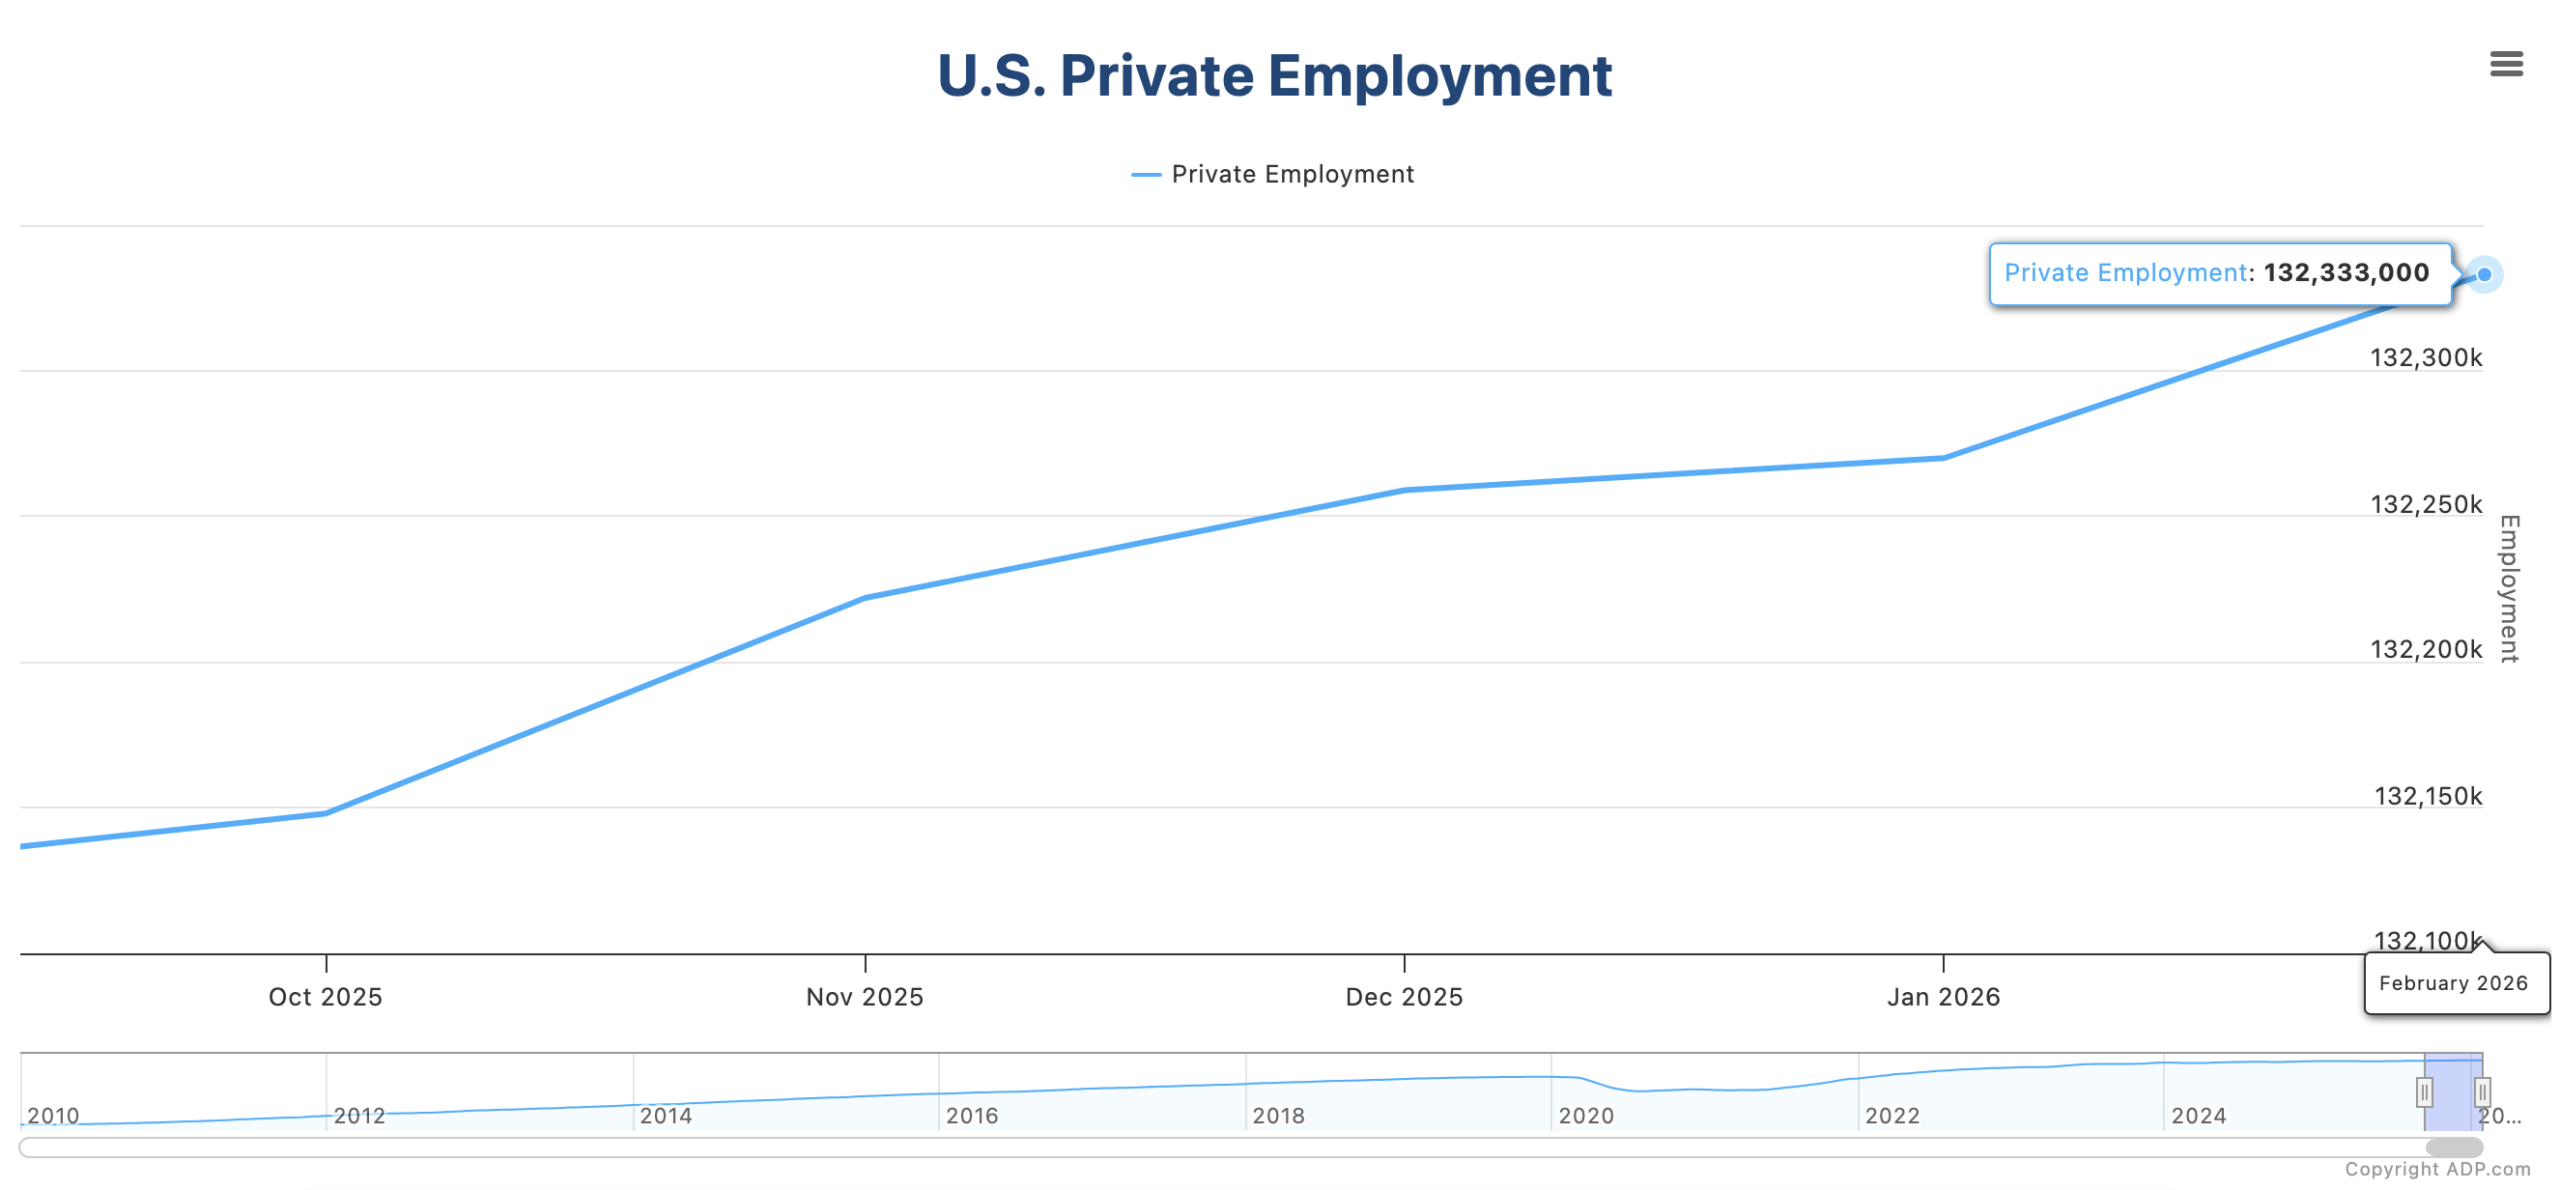
In contrast, ADP’s February Employment Report — which uses data from private businesses — came in at +63,000 on Mar. 4. An excerpt read:
“Hiring jumped in February, delivering the best showing for job gains since November 2025. Construction, education, and health services led the growth.” Chief Economist Dr. Nela Richardson, added, “We’ve seen an increase in hiring and pay gains remain solid, especially for job-stayers.”
Thus, resilient private and shaky public payrolls data only clouds the outlook for monetary policy.
To break the tie, it’s prudent to monitor U.S. Job Postings on Indeed. Since the data set updates weekly, it’s a more timely indicator of employment demand. And because the metric has trended higher since bottoming in November 2025, it supports ADP’s results more than the BLS, aligning with a more optimistic outlook for the U.S. labor market.

Turning to the financial markets, gold and silver have been caught in the recent volatility, as the prospect of an oil-induced recession is bearish for inflation-driven assets like precious metals.
However, research from J.P. Morgan highlights how Middle East conflict is typically bullish for gold.
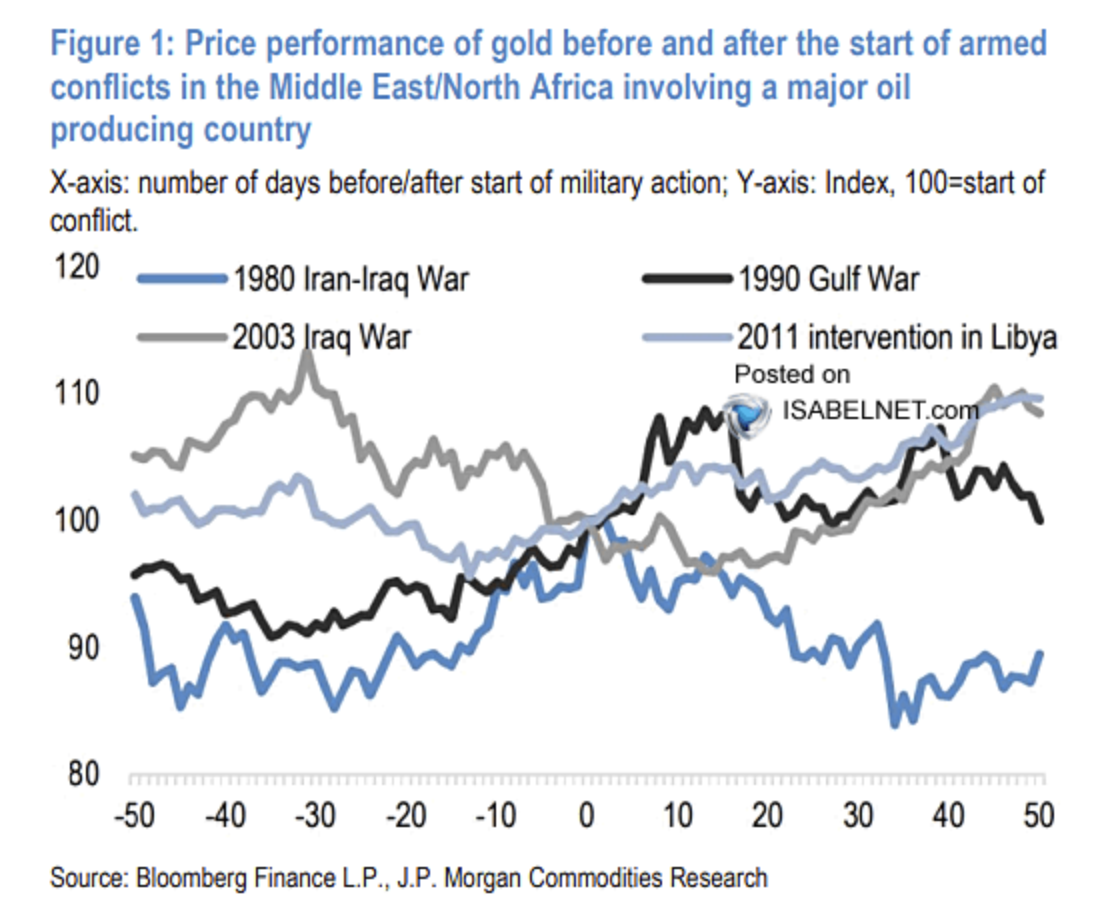
To explain, the colored lines above track the performance of gold before, during, and after conflicts in the Middle East. If you analyze the middle of the chart, the number zero on the x-axis represents the beginning of each battle. During three of the four events, gold either rose immediately or was higher within the next 50 days. As a result, the yellow metal should remain a reliable portfolio hedge during this bout of uncertainty.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
As a worthwhile option, Augusta Precious Metals specializes in precious metal IRAs, helping to roll your existing retirement accounts, such as a 401 (k), into IRAs backed by physical gold or silver. You can also purchase bullion directly, and the company has an exceptional reputation, with either AAA or 4.5 to 5-star reviews across multiple ratings agencies.
Furthermore, if you’ve built a thriving business and are looking to cash in on your success, it’s essential to think from a buyer’s perspective. Our extensive guide covers prep work, valuation, marketing, and provides other useful tips to help you create a professional pitch. We also have more valuation resources to help better understand the key financial metrics that can make or break a deal.
In addition, if you own an HVAC business in Texas, our niche guide is the perfect playbook to help you obtain the best price.
Finally, for creditor solutions, please consult our list of debt management firms for other financial resources in your area.
by Brandi Marcene | Mar 2, 2026 | Definitions
For many residents in Kansas, debt problems don’t rise overnight. Credit cards pile up, medical bills linger, and short-term loans often stretch into long-term obligations. When monthly payments start competing with groceries, choosing the right Kansas debt relief program becomes essential. Solutions like New Era Debt Solutions, National Debt Relief, and Freedom Debt Relief offer residents options to reduce balances, reorganize repayment, or access legal guidance, helping Kansans take control of their finances before debts spiral further.
Locals face numerous debt levels, with an average person carrying almost $45,300 in total debt, which includes mortgages, student loans, credit cards, and auto financing as of 2024.
This guide explains how debt relief in Kansas works, compares the most common programs and companies, and helps you decide which route makes the most sense for your situation before costly mistakes are made.
Why Do Debt Relief Options Work Differently in Kansas?
The unique financial characteristics of Kansas include a very high percentage of families with middle-class incomes (the median income is approximately $52,081), meaning many families earn enough to be self-sufficient, but not enough to financially weather periodic downturns in the economy.
Due to these financial challenges, Kansans have two types of debt relief programs available to them:
- “Programs that offer assistance through negotiation to reduce outstanding balances” and
- “Programs that provide assistance to restructure the way payments are made to the lender of record without reducing the principal.”
What Types of Debt Relief Options Are Available in Kansas?
Before comparing providers, what types of debt relief are available in Kansas? Among many options, here are the ones that you can consider based on their approach.
| Debt Type |
Recommended Relief Approach |
Why It Works |
Notes / Considerations |
| Credit Card Debt |
Debt Settlement |
Diminishes the total balance with negotiations |
Ideal for $7,500+ unsecured debt |
| Personal Loans |
DMP or Settlement |
Negotiates a lower payoff |
Depends on repayment ability |
| Medical Bills |
Settlement |
Reduces bills, usually with nonprofit assistance. |
Check for hospital or clinic-specific programs |
| Payday or Title Loans |
Nonprofit / Legal Assistance |
Restructures high-interest loans. |
Catholic Charities Loan Pool Project |
| Legal Action |
Legal Debt Relief |
Protects assets and ensures compliance |
Requires attorney involvement. |
Debt Relief Programs Available to Kansas Residents
Below is a comparison of reputable programs and services commonly used for Kansas debt relief.
Kansas Debt Relief Provider Comparison
| Company / Program |
Best For |
Minimum Debt |
Fees |
Availability in Kansas |
| New Era Debt Solutions |
Personalized debt settlement |
Ten thousand dollars in unsecured |
Performance-based |
Nationwide (Kansas included) |
| National Debt Relief |
Large unsecured balances |
Seven thousand five hundred dollars |
Performance-based |
Nationwide |
| Accredited Debt Relief |
Multiple unsecured debt types |
Ten thousand dollars |
Performance-based |
Nationwide |
| Freedom Debt Relief |
Established settlement programs |
Seven thousand five hundred dollars |
Performance-based |
Nationwide |
| APFSC (Nonprofit) |
Credit counseling & DMPs |
No strict minimum |
Low nonprofit fees |
Kansas residents |
| InCharge Debt Solutions |
Budgeting & DMPs |
No strict minimum |
Low nonprofit fees |
Kansas residents |
| Catholic Charities Loan Pool Project |
Payday & title loan relief |
Varies |
Program-based |
Local Kansas programs |
| Debt Relief Attorney (Kansas City) |
Legal & bankruptcy solutions |
Varies |
Attorney fees |
Kansas City metro |
New Era Debt Solutions is a well-reputed provider offering Kansas debt relief through customized debt settlement strategies. Rather than enrolling clients into templates, New Era assesses every individual profile to determine a realistic settlement target. For an enhanced review, timelines, and the real-world outcomes. 
![]()
Check If You Qualify
Wondering if New Era’s debt settlement program fits your situation? A free consultation can help you assess eligibility with no obligation.
Check Your Eligibility
Best For
For the locals having more than $10,000 in unsecured debt, who need structured negotiations with support rather than repayment-based plans.
How It Works
Once after a free consultation, clients then fund a specific account while the New Era negotiates with the creditors to reduce their balances. Fees are charged after a successful settlement.
Why It Stands Out
New Era’s focus on personalization and transparency makes it the best-suited option among major debt relief programs in Kansas, where residents consider reducing their debt balance as the priority.
![]()
See How New Era Could Impact Your Debt
Curious if New Era’s debt settlement approach is right for you? Our detailed review breaks down timelines, real-world results, and what to expect before enrolling.
Read the full New Era review.
National Debt Relief
National Debt Relief Kansas, as the biggest settlement company, has the most favorable services for people who are ineligible for large loans but have considerable unsecured debt.
Best For
Homeowners who are trying to refinance their homes and don’t mind paying slightly higher APRs.
How It Works
Clients complete a free assessment, then follow a structured settlement plan as funds accumulate and negotiations occur.
Why It Stands Out
Scale, experience, and a clear performance-based fee structure make it a familiar option for many households.
Explore more about National Debt Relief here.
Accredited Debt Relief
Accredited Debt Relief focuses on helping clients to resolve multiple types of unsecured debt through negotiated settlements.
Best For
For the local managing multiple unsecured accounts with different lenders.
How It Works
Once enrolled, an accredited negotiator directly negotiates with creditors while clients set aside monthly funds.
Why It Stands Out
Its emphasis on ethical communication and transparency appeals to those cautious about settlement programs.
Further read about Accredited Debt Relief for more clarification.
Freedom Debt Relief
Freedom Debt Relief is one of the longest-running settlement providers in the U.S and remains a common option for debt relief for Kansas residents.
Best For
Individuals with large debt balances who prefer an established provider with extensive resources.
How It Works
Certified debt consultants manage negotiations once clients complete a financial review.
Why It Stands Out
Nationwide reach and structured processes make Freedom a familiar name in settlement-based relief.
Read more about Freedom Debt Relief here.
Nonprofit Debt Relief Options in Kansas
APFSC (American Personal Financial Services Council)
APFSC offers nonprofit credit counseling and debt management plans designed to simplify repayment and reduce interest costs.
Best For: Residents who can repay principal but need relief from high interest and late fees.
InCharge Debt Solutions
InCharge provides counseling, budgeting assistance, and DMPs for Kansas residents seeking structured repayment without settlement.
Best For: Households looking for predictability and education-based financial recovery.
Catholic Charities Loan Pool Project
This Kansas-based initiative focuses on refinancing predatory payday and title loans into manageable repayment plans.
Best For: Residents are trapped in high-interest short-term lending cycles.
If you’d like to explore more options and see how they compare, start with our guide to the top debt settlement companies, ranked by ratings and reviews.
How to Choose the Right Debt Relief Path in Kansas
Before enrolling in any program, ask yourself:
- Is my debt mostly unsecured?
- Can I realistically repay the principal, or do I need a reduction?
- Am I facing legal action?
- How stable is my income?
FAQs
Is Kansas debt relief real?
Yes, Kansas debt relief is legitimate when provided by reputable companies or nonprofit organizations that follow state and federal regulations. These programs are designed to help residents manage, negotiate, or consolidate their debt. Always verify credentials before enrolling.
How much debt do I have to have to qualify?
Debt settlement programs in Kansas generally require $7,500–$10,000 in unsecured debt, such as credit cards, personal loans, or medical bills. Nonprofit counseling or debt management plans may accept lower balances. The eligibility depends on your financial situation, income, and the type of debt relief program you are considering.
Will my credit score go down because of debt relief?
Some debt relief methods, especially settlements, can temporarily lower your credit score. However, many residents opt for these programs to prevent defaults, collections, or lawsuits that could cause long-term credit damage.
Are national programs also available in Kansas?
Yes, several nationally recognized debt relief companies operate legally in Kansas. These programs provide nationwide services, often including settlement, counseling, and debt management
Can I apply a debt relief service to my medical bills?
Absolutely. Medical debt is one of the most common types of unsecured debt addressed through both settlement and nonprofit counseling programs. Hospitals, clinics, and lenders may participate in negotiated repayment or reduction programs, helping residents manage balances without derailing monthly budgets or causing additional financial stress
by Alex Demolitor | Feb 13, 2026 | Definitions
The January 2025 Consumer Price Index of All Urban Consumers (CPI-U) report indicates that inflation increased by 0.2% this month, down from 0.3% in December. These data were released at 8:30 am EST on February 13, 2026, by the Bureau of Labor Statistics (BLS). Before seasonal adjustment, the year-over-year (Y-o-Y) inflation rate in the all-items index grew by 2.4%, a deceleration from the 2.7% realized in December.
The figures were well behaved and mostly aligned with economists’ consensus estimates. The table below is courtesy of Investing.com. The left column represents January’s figures, while the right column represents forecasters’ expectations. As you can see, the headline figures missed slightly, while the core metrics matched the consensus.

As it stands, a mixed economic outlook has Fed officials leaning in a hawkish direction. Dallas Fed President Lorie Logan said on Feb. 10 that “We will learn in the coming months whether inflation is coming down to our target and whether the labor market will remain stable. If so, this would tell me that our current policy stance is appropriate and no further rate cuts are needed to achieve our dual mandate goals.
“If instead we see inflation coming down but with further material cooling in the labor market, cutting rates again could become appropriate. But right now, I am more worried about inflation remaining stubbornly high.”
Thus, with commodity futures prices rising sharply in January, higher input costs could uplift the CPI over the next few months and keep the Fed on hold.

Food Prices
The food index rose by 0.2% MoM in January, and five of the six major grocery indices increased this month.
- Cereals and bakery products (+1.2%)
- Meats, poultry, fish, and eggs (+0.2%)
- Dairy and related products (+0.8%)
- Fruits and vegetables (+0.1%)
- Nonalcoholic beverages (+0.1%)
- Other food at home (-0.3%)
Surprisingly, the food away from home index only increased by 0.1% (versus 0.7% in December), as restaurant inflation underperformed in January.
Energy Prices
The energy index fell by 1.5% MoM in January, with gasoline prices down by 3.2%, electricity down by 0.1%, and natural gas rising by 1.0%.
Core CPI
The January core CPI rose by 2.5% Y-o-Y, down from 2.6% in December. Below is an itemized breakdown of the various components:
- Shelter index: (+0.2%) [December: +0.4%]
- Rent index: (+0.2%) [December: +0.3%]
- Owners’ equivalent rent: (+0.2%) [December: +0.3%]
- Motor vehicle insurance: (-0.4%) [December: NA]
- Medical care services: (+0.3%) [December: +0.4%]
- Physician services: (+0.3%) [December: +0.3%]
- Hospital services: (+0.9%) [December: +1.0%]
- Airline fares: (+6.5%) [December: +3.8%]

Seasonally Unadjusted CPI
Before seasonal adjustments, the CPI-U for January 2025 increased by 2.4% Y-o-Y to an index level of 325.252. Since these figures are unadjusted, they include regular seasonal price fluctuations that can create volatility in the results.
From Bad to Good
After months of solid economic data, weakness to start the New Year had recession whispers growing louder.
For example, the BLS reported on Feb. 5 that JOLTS Job Openings retreated in December. The report stated:
“The number of job openings trended down to 6.5 million (-386,000) in December and was down by 966,000 over the year. The job openings rate, at 3.9 percent, changed little over the month. The number of job openings decreased in professional and business services (-257,000), retail trade (-195,000), and finance and insurance (-120,000).”
Moreover, with the metric sinking below its pre-pandemic baseline, a cooling U.S. labor market was on full display.

Next up, the U.S. Census Bureau revealed on Feb. 10 that retail sales were flat in December, which poured cold water on the idea of robust holiday sales. As a result, consumer spending and employment weakness created more uncertainty for investors and policymakers.

However, while it seemed like the economic outlook could be headed in a negative direction, the BLS reported on Feb. 11 that U.S. nonfarm payrolls rose by 130,000 in January, the largest monthly increase since December 2024.
More importantly, the job gains, wage inflation, and the unemployment rate all outperformed economists’ consensus estimates, offsetting the recession fears that culminated from the weak data above.

Add it all up, and the recent data is still strong enough to keep the FOMC on hold. Higher inflation is likely over the next few months, and the committee is unlikely to expedite rate cuts as long as employment remains solid.
Turning to the financial markets, gold and silver stole the show in January, with rapid rises and intense corrections. And while both have calmed for the time being, volatility could be amplified as their bull markets reach an accelerated phase.

To explain, the blue line above tracks the gold-S&P 500 ratio. If you analyze the left side of the chart, you can see that gold significantly outperformed stocks leading up to, during, and after the global financial crisis.
Therefore, while the surge above $5,000 has garnered plenty of headlines, the level of the ratio on the right side of the chart signals that more upside could be on the horizon, and gold could remain an in-demand asset for the foreseeable future.
Are you thinking about diversifying into precious metals? Talk to your financial advisor about initiating a gold IRA account today, allowing you to invest in this red-hot asset on a tax-advantaged basis. Additionally, our complimentary CPI inflation calculator remains at your disposal, enabling you to assess inflation’s impact on your finances. Please seek the guidance of a financial advisor before making any investment decision.
Furthermore, if you’ve built a thriving business and are looking to cash in on your success, it’s essential to think from a buyer’s perspective. Our extensive guide covers prep work, valuation, marketing, and provides other useful tips to help you create a professional pitch. We also have more valuation resources to help better understand the key financial metrics that can make or break a deal.
In addition, if you own an HVAC business in Texas, our niche guide is the perfect playbook to help you obtain the best price.
Finally, for creditor solutions, please consult our list of debt management firms for other financial resources in your area.
by Brandi Marcene | Jan 16, 2026 | Definitions
Although it is paradise on Earth, Hawaii, in 2026, is one of the priciest states to live in in America. Because of high rent and imported goods, many people are in debt from using credit cards and personal loans. This guide breaks down Hawaii-specific debt relief options and explains how they differ from states like Texas and California.
Why Is Debt Relief Different in Hawaii Compared to Other States?
Hawaii’s sky-high living costs—193.3 index—pile on credit card debt faster than mainland states like California or Texas. Remote islands mean fewer local offices, forcing reliance on nationwide programs. Discover tailored debt relief Hawaii options that slash balances 20-50% despite the “paradise tax.”
Here are a few key factors that shape the debt landscape in Hawaii:
Cost of Essentials
Hawaii’s residents are affected by the higher prices of daily necessary goods, which are caused by the long-distance transport of these goods. This practice sometimes compels the people living there to use a credit card to cover their expenses.
Housing Burden
Housing costs take a major part of the monthly salary, and the amount left for paying off debts is therefore less.
Limited Local Access
Maui, Kauai, or the Big Island do not have many physical offices; thus, the majority of the inhabitants depend on remote programs and national providers.
High Use of Credit
Often, using credit cards to pay for basic needs leads to increased balances of unsecured debts, which makes debt settlement or debt management plans (DMPs) more common occurrences.
Before we compare providers in detail, it’s helpful to understand the main types of debt relief programs Hawaii residents use.

Information taken from meric.mo.gov
What Types of Debt Relief Programs Are Available in Hawaii?
Hawaii residents often rely on different debt relief Hawaii options depending on debt type and income. For instance, in the case of high unsecured debt, debt settlement is an appropriate solution where the creditor negotiates the balance for a reduced fee as compared to the original balance.
Debt Management Plans help consumers by consolidating the monthly payments without reducing the balance. Another method is the credit consolidation loan. Credit counseling provides consumers with the knowledge needed. As a final resort, legal debt relief is applicable.
For a deeper overview of options, see our comprehensive guide here: Debt Relief Overview.
Which Debt Relief Program Is Right for Hawaii Residents?
| Program Type |
Best For |
Pros |
Cons |
Typical Duration |
| Debt Settlement |
High unsecured debt |
Reduces total debt owed |
May temporarily lower credit score |
24 to 48 months |
| Debt Management Plan (DMP) |
Medium debt, steady income |
Combines payments, lowers interest |
Balance not reduced |
24 to 60 months |
| Debt Consolidation Loan |
Fair credit, multiple debts |
One monthly payment |
Requires good credit |
12 to 36 months |
| Credit Counseling |
Low debt, budget issues |
Education, financial planning |
No direct debt reduction |
3 to 12 months |
| Bankruptcy (Legal) |
Overwhelming debt |
Stops collection calls, legal protection |
Long-term credit impact |
Varies |
Which Debt Relief Hawaii Companies Are Trustworthy in 2026?
Choosing the right Hawaii debt relief provider is crucial. Top picks serve all islands remotely, tackling high living costs with proven, tailored programs.
Top Hawaii Debt Relief Companies
| Company |
Best For |
Minimum Debt |
Fees |
Availability in Hawaii |
| New Era Debt Solutions |
Personalized debt settlement |
$10,000 |
Performance-based |
Nationwide |
| National Debt Relief |
High unsecured debt balances |
$7,500 |
Performance-based |
Nationwide |
| Accredited Debt Relief |
Multiple debt types |
$10,000 |
Performance-based |
Nationwide |
| Freedom Debt Relief |
Large, established programs |
$7,500 |
Performance-based |
Nationwide |
| CuraDebt |
Tax and business debt |
$10,000 |
Varies |
Nationwide |
Residents in Hawaii might find providers more appealing if their services don’t involve visiting their locations in person. New Era Debt Solutions is a company operating one hundred percent from a remote environment, and it covers all the islands with a customized way of settling debts, which is not common with large companies.
Learn more about New Era by checking out our review. 
Best for:
- $10,000+ in unsecured debt
- Credit card and personal loan balances
- Consumers who want individualized support
Not ideal for:
- Secured debt (auto loans, mortgages)
- Very small debt balances
If you’re weighing different debt relief options and want to see how New Era’s settlement program could work for your situation, you can use their free assessment tool to get a clear picture.
Explore a Free Consultation
2. National Debt Relief
One of the largest service providers in the country, National Debt Relief has both the scale and creditor relationships that benefit Hawaii residents dealing with large balances and multiple creditors.

Best for:
- High total unsecured debt
- Consumers needing a structured, long-term plan
- Those comfortable with a standardized program model
Not ideal for:
- Consumers seeking highly customized strategies
- Low-debt situations
3. Accredited Debt Relief
Accredited Debt Relief provides its users with flexibility across different debt types, which can be helpful for Hawaii residents who have to manage a mix of credit cards, medical bills and personal loans.

Best for:
- Mixed unsecured debt portfolios
- Residents want multiple settlement options
- Mid-to-high debt balances
Not ideal for:
- Individuals who only need budgeting help
- Secured or student loan debt
4. Freedom Debt Relief
With an infrastructure that spreads nationwide and years of experience, Freedom Debt Relief offers continuous support for Hawaii residents who prefer a well-established provider with extensive resources.

Best for:
- Large credit card balances
- Consumers seeking brand recognition
- Long-term settlement programs
Not ideal for:
- Those wanting short-term solutions
- Very small debt amounts
5. CuraDebt
CuraDebt is a practical option for Hawaii residents dealing with tax-related or business debt areas where many standard debt settlement companies do not specialize.

Best for:
- Tax debt or IRS obligations
- Small business owners
- Complex debt situations
Not ideal for:
- Credit card–only debt
- Consumers seeking nonprofit counseling
How Do I Choose the Best Debt Relief Hawaii Program?
To determine which debt reset option is best for you, there are considerations in relation to total unsecured debt, affordability, and future goals, which are significant and include:
- Type and amount of debt — High amounts may require settlement, and smaller amounts can use debt management plans or credit counseling.
- Program length and tuition — Know the costs and durations before pursuing.
- Credit effect — Some programs lower credit scores, while others do not. Provider reputation can be analyzed by reading the company reviews and checking the provider’s legal compliance.
For a full comparison of top-rated companies, see: 21 Best Debt Settlement Companies Ranked.
FAQ’s — Debt Relief Hawaii Programs Explained
How effective is debt relief for Hawaii residents given the high cost of living?
Debt relief Hawaii programs have the potential to bring great results, but careful planning is unavoidable, considering the “paradise tax” and the expensive housing in Hawaii. The citizens usually count on national companies that provide remote structured programs. The outcome is determined by the kind of debt, the total amount, and what one can afford to pay monthly.
Is Hawaii debt relief a legal and reputable option?
Yes. There are federal laws that the providers are to follow regarding consumer laws and protection. Always check for legitimacy and state approval if there are local offices involved via an authoritative review like our JG Wentworth Debt Relief review.
How long do Hawaii debt relief programs usually take?
Programs typically last 24 to 48 months, depending on debt amount, creditor cooperation, and monthly contributions. Planning for Hawaii’s higher living costs can help avoid delays or program dropouts.
How much debt do I need to qualify for Hawaii programs?
The majority of programs necessitate $7,500 to $10,000 in unsecured debt. Individuals with lesser amounts may get help from nonprofit counseling or debt management programs.
When is bankruptcy the right choice for Hawaii residents?
Filing for bankruptcy is the final option in the legal solutions. Credit is preserved, and long-term financial risk is lowered when residents go through structured programs first. Legal ways out are very important in situations of wage garnishment, lawsuits, or tax debts with the IRS.