Note: we are an independent blog. Our content doesn't constitute financial advice. We strive for accuracy, but please always cross-check inflation numbers directly with the BLS. We may receive compensation from some services and products reviewed on this site (learn more).
Yes. CuraDebt is a legitimate debt relief company operating since 1996, one of the oldest in the industry, headquartered in Hollywood, Florida, and accredited by the AADR and IAPDA. What sets them apart: they handle both consumer debt settlement and tax/IRS debt relief under one roof, and they act as a matching platform that can route you to the program that fits your situation. No upfront fees for settlement, per FTC rules. Main limitations: not available in every state, and like all debt settlement, the process can hurt your credit score while negotiations are underway.
CuraDebt (https://www.curadebt.com/) is a debt relief company that has been in business since 1996 (according to their website), making it one of the oldest in the industry. They offer debt settlement and relief services for various types of unsecured debt, including credit card debt, personal loans, medical bills, and tax debt. Based on our review, CuraDebt has generated a lot of positive reviews for its debt relief services, particularly for its ability to help clients reduce their debt through negotiations with creditors. Where applicable, CuraDebt also operates as a referral and matching platform: if you don’t qualify for their settlement program, they may route you toward tax relief, business debt assistance, or other debt-management options instead of simply turning you away.
Free consultation, no upfront fees for settlement. CuraDebt is an affiliate partner, so we may earn a commission if you use this link.
Who is CuraDebt?
As we said earlier, CuraDebt is a debt settlement company that specializes in negotiating with creditors on behalf of consumers to reduce their overall debt. They work with individuals who are struggling to manage their credit card debt, tax debt, medical bills, or other unsecured debts.
Headquarters
Hollywood, Florida
Founded
1996 (in Irvine, California)
States NOT Covered
Connecticut, Georgia, Illinois, Kansas, Maine, Nevada, New Hampshire, Oregon, South Carolina, Vermont, West Virginia, and Puerto Rico
Generally $10,000 in unsecured debt for the settlement program (historically they’ve advertised lower minimums, and smaller cases may be routed to other programs, ask during the consultation)
Minimum Age
21+ years old
Income Requirement
No minimum, but must have verifiable regular income and be experiencing genuine financial hardship
Company Legitimacy, Ratings & Reviews
As we covered earlier, this company has been operating in the debt settlement space since 1996, which makes it one of the oldest in the industry. In our view, the company’s longevity speaks volumes about its professionalism and customer service.
Platform
Rating
Review Count
BBB (A+ Rating)
4.7/5
~23 reviews
Google Reviews
4.8/5
~271 reviews
TrustPilot
3.3/5
~12 reviews
Yelp
4.6/5
~12 reviews
Volume-Weighted Average
4.73/5
~306 (BBB + Google + TrustPilot)
Accreditations: Member of the American Association for Debt Resolution (AADR); Certified by the International Association of Professional Debt Arbitrators (IAPDA)
Two honest notes on the numbers. First, CuraDebt’s total review base is small compared to national giants, a few hundred reviews versus tens of thousands for the biggest settlement brands, so the averages carry less statistical weight. Second, the Trustpilot score (3.3/5) lags the other platforms, though it’s based on only about a dozen reviews. You can see exactly how CuraDebt stacks up against 13 other settlement companies in our volume-weighted ranking of the best debt settlement companies, where they currently sit at #2.
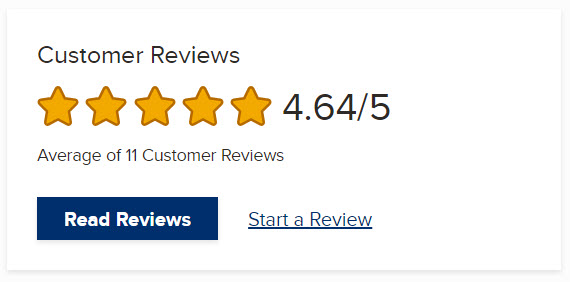
CuraDebt BBB
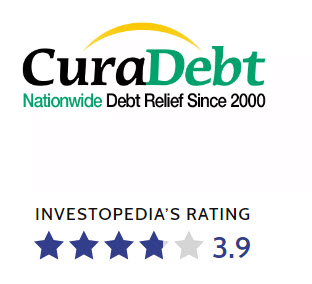
CuraDebt Investopedia Rating
CuraDebt Google Rating
CuraDebt Key Services & Features
💬 Debt Settlement & Negotiation
Their core program: negotiating with creditors to settle unsecured debts for less than the full balance. No fees until a settlement is reached and accepted.
🏛️ Tax Debt Relief
A rarity among settlement companies: their team includes tax professionals who can work with the IRS on back taxes, penalties, and liens.
🏢 Business & MCA Debt
Assistance with business debt and merchant cash advance obligations, another niche most consumer settlement firms don’t touch.
🔀 Free Counseling & Matching
A free consultation reviews your situation and routes you to the program that fits, including consolidation through partner lenders (watch the rates if you choose this path!).
Fee structure: No upfront fees for settlement; a fee is charged only after a debt is successfully settled and you accept the offer. Exact fees vary by program and individual circumstances and are fully disclosed during the consultation, industry sources generally cite the 15–25% of enrolled debt range for settlement programs. Get your exact fee in writing before enrolling.
Strategy: Utilizes various strategies, such as creditor violations (e.g., FDCPA, TCPA) to negotiate better terms for clients
Limitations: services are not available in all U.S. states (see the excluded list above).
One of the key advantages of CuraDebt is that it does not charge upfront fees for settlement, meaning you only pay once a debt settlement has been successfully negotiated. This is required by FTC rules. CuraDebt is also known for its ability to identify creditor violations, which can sometimes lead to additional savings or settlements for the client.
⚠️ Know the Trade-Offs Before You Enroll
Debt settlement can negatively impact your credit score, as the process often involves stopping payments to creditors while negotiations are underway, and creditors can pursue collections or lawsuits during that window. Forgiven debt can also create a tax bill. And no company can guarantee a specific savings percentage: outcomes depend on your creditors, your hardship, and your ability to fund the settlement account. If someone quotes you a guaranteed result before reviewing your file, treat it as a red flag, at any company. Our guide to nonprofit credit counseling walks through the lower-risk alternatives, including how a nonprofit agency can often cut your interest rate without the credit damage.
Customer Support Review
They seem to have responsive customer support through their live chat feature. We tested it ourselves: we asked their support team to explain their services, and an agent named Genesis walked us through the model clearly. You make monthly deposits into a dedicated account instead of paying creditors directly, and as the balance accumulates, CuraDebt negotiates settlements with each creditor. When an offer comes in, they contact you to present it, and the funds only move once you accept. The agent cited typical savings figures during the chat, but treat any savings numbers you hear during sales conversations as marketing estimates, not promises, your actual results depend entirely on your creditors and your situation.
How CuraDebt Compares to Other Debt Relief Companies
The trade-off is scale: companies like TurboDebt and Freedom Debt Relief carry review bases in the tens of thousands, while CuraDebt’s footprint is a few hundred reviews. Longevity partially offsets that, very few companies in this industry have survived since 1996.
Not sure settlement is even your best move?
Depending on your numbers, consolidation, nonprofit counseling, or even bankruptcy may fit better than settlement. Our 60-second quiz compares all of them honestly before you talk to any company.
CuraDebt is legitimate and one of the industry’s oldest firms: operating since 1996, BBB A+, AADR member, IAPDA certified.
Unique breadth: consumer debt settlement, tax/IRS debt relief, and business/MCA debt help under one roof.
No upfront fees for settlement; exact fees vary by program and are disclosed during the free consultation, get them in writing.
Settlement generally requires ~$10,000 in unsecured debt and genuine hardship; smaller or different cases may be routed to other programs.
Not available in CT, GA, IL, KS, ME, NV, NH, OR, SC, VT, WV, or Puerto Rico.
Settlement hurts your credit while underway, compare it against counseling and consolidation before enrolling.
Final Thoughts
CuraDebt earns its place on our radar through longevity, breadth, and a results-based fee model. It’s a particularly strong consideration if your debt picture includes tax debt or business debt alongside credit cards, almost nobody else handles all three. If you’re a straightforward credit-card-settlement case with a large balance, also compare a bigger-volume provider such as Americor before deciding. And if your debt is still manageable, this first-person guide on how to reduce debt in 2026 or our bankruptcy vs. debt relief comparison may help you avoid a formal program altogether.
Ready to explore your options with CuraDebt?
The consultation is free, and they’ll tell you which of their programs (if any) fits your situation, settlement, tax relief, or an alternative path.
CuraDebt is an affiliate partner. We may earn a commission if you use them, at no extra cost to you. This doesn’t affect our ratings.
Frequently Asked Questions About CuraDebt
What types of debt does CuraDebt handle?
CuraDebt specializes in settling unsecured debts, including credit card debt, personal loans, medical bills, and private student loans, plus tax debts and business/MCA debt, which most settlement companies won’t touch. They do not typically handle secured debts like mortgages or auto loans, although it’s worth asking during the free consultation.
How does the CuraDebt debt settlement process work?
The process begins with a free consultation to assess your debt situation and see if you qualify. If you enroll, you make monthly deposits into a dedicated savings account instead of paying creditors directly. As funds accumulate, CuraDebt negotiates with each creditor to reduce what you owe; when an offer comes in, they present it to you, and the money moves only after you accept. The typical timeframe is 24 to 48 months.
Does CuraDebt charge upfront fees?
No. CuraDebt does not charge upfront fees for debt settlement. This is required by FTC rules. Fees are charged only after a settlement is successfully reached and you accept it. Exact fees vary by program and individual circumstances and are disclosed during the consultation; industry settlement fees generally run 15–25% of enrolled debt. Get your specific fee structure in writing before enrolling.
Will using CuraDebt affect my credit score?
Yes. Participating in a debt settlement program can negatively impact your credit score, since the process often involves stopping payments to creditors while negotiations are underway. The goal is to settle debts for less than what’s owed, which may improve your overall financial situation long-term, and the credit impact is generally less severe than bankruptcy, but the short-term damage is real. Weigh it against alternatives like counseling and consolidation first.
How long does the CuraDebt settlement process take?
The debt settlement process with CuraDebt typically takes between 24 and 48 months, depending on the amount of debt and how quickly you can accumulate funds in your dedicated savings account for settlements. Larger balances and slower funding stretch the timeline.
Is CuraDebt available in all U.S. states?
No. As of 2026, CuraDebt’s services are not available in Connecticut, Georgia, Illinois, Kansas, Maine, Nevada, New Hampshire, Oregon, South Carolina, Vermont, West Virginia, or Puerto Rico. If you live in an excluded state, you’ll need an alternative, our state guides, like Georgia debt relief options and debt solutions for Illinois, cover providers and programs that do operate there.
Does CuraDebt offer tax debt relief?
Yes. CuraDebt offers tax debt relief services, with tax professionals who can work with the IRS on your behalf to resolve back taxes, penalties, and liens. This is one of their biggest differentiators, most debt settlement companies won’t touch IRS debt at all, forcing you to hire a separate tax firm.
What are the qualifications to use CuraDebt’s services?
For the debt settlement program, you generally need at least $10,000 in unsecured debt, must be at least 21 years old, have verifiable regular income, and be experiencing a financial hardship that makes full repayment difficult. There is no maximum debt limit. CuraDebt has historically advertised lower minimums, and cases that don’t fit settlement may be routed to their tax relief, business debt, or other programs, so it’s worth doing the free consultation even if you’re near the threshold.
What happens if I don’t qualify for CuraDebt’s settlement program?
You won’t simply be turned away. CuraDebt operates partly as a matching platform: depending on your situation, they may point you toward tax relief services, business/MCA debt assistance, or alternative debt-management options. That said, always compare any recommendation against the full menu of options yourself, our ranking of the best tax relief companies is the place to check any tax debt recommendation before you agree to it.
What should I expect during the free consultation?
During the free consultation, a CuraDebt counselor reviews your financial situation and discusses your options for debt relief. They should explain the potential savings, timeline, risks, and fees involved, all program details are disclosed before any commitment. Come prepared with your balances, creditors, and monthly budget, and ask for everything in writing before you decide.
How do I get started with CuraDebt?
You can explore your available options on CuraDebt’s website or call their customer service line for a free savings estimate. If you decide to enroll, you’ll be assigned a debt counselor who guides you through the entire settlement process.
If you’re overwhelmed by unsecured debt such as credit cards, personal loans, medical bills, or collections, and you’re looking for a legitimate way to reduce what you owe, Accredited Debt Relief (www.AccreditedDebtRelief.com) is a name you’ll probably come across. This review is updated for 2026 and focuses on the details that matter most: what the program actually is, what it costs, who it’s for, what to ask before you enroll, and what current ratings look like.
Disclosure: We highly recommend analyzing different options and speaking to a counsellor. We may earn compensation if you use some links on this page. That does not change the price you pay or the way we review debt relief companies.
Accredited Debt Relief at a glance
Feature
Details
What I’d ask before enrolling
Best for
People with $5,000 or more in unsecured debt who want to lower their monthly payments through personalized consolidation options.
Which specific option are you recommending for me, and what are the costs of each?
Typical debt handled
Credit cards, personal loans, medical bills, collections, and some other unsecured debts.
Which of my creditors do you commonly work with?
Minimum debt
$5,000 or more in unsecured debt. Eligibility depends on your income, debt type, and financial situation.
Do I qualify based on my debt amount, creditors, income, and hardship?
Possible options
Debt relief programs and consolidation loan options, matched to your specific financial situation.
Am I being evaluated for a debt relief program, a consolidation loan, or another product?
Fees
Settlement fees are based on a percentage of enrolled debt and are charged after results, not upfront. Typically 15% to 25%, varying by state.
What is the total fee, and are there separate account or maintenance fees?
Track record
Company-stated: 1.3M+ clients helped, $15B+ in client debt resolved, 15+ years in operation (founded 2011).
What results are typical for someone with my debt amount and budget?
Get started
Check the nonprofit route first, then compare settlement providers if counseling cannot cover the balances.
Headquarters commonly listed: San Diego, California
Founded: 2011 (15+ years in operation), with 2,200+ US-based employees
Minimum debt to qualify:$5,000 or more in unsecured debt (exact eligibility depends on income, debt type, and state).
What they evaluate: Personalized debt consolidation options, including debt relief programs and loan solutions, matched to your individual financial situation.
Company-stated benefit: Accredited says some clients may reduce eligible monthly debt payments by 40% or more and become debt-free in 24 to 48 months. This is not a guarantee and depends on your debt, budget, creditors, and plan.
Experience and impact (company-stated): Accredited says it has helped more than 1.3 million clients and resolved more than $15 billion in client debt.
Important trust note:
Corporate structures in the debt relief industry can be confusing. Accredited Debt Relief operates as a DBA (doing business as) of Beyond Finance, LLC. That is not a red flag, but it is a reason to confirm who will service your plan, who negotiates on your behalf, and what fees you will pay before signing anything.
Your Debt Relief Options: Quick Comparison
Start with the option that matches your ability to make payments.
Best if: you can afford a reduced monthly payment. Upside: lower interest, usually low credit impact. Tradeoff: usually no principal reduction; plan resets if you miss a payment.
Best if: no payment plan is realistic. Upside: may provide a legal fresh start. Tradeoff: serious credit/legal consequences.
What Accredited Debt Relief can help with
Debt settlement programs typically focus on unsecured debt. That usually includes:
Credit card debt
Personal loans
Medical bills
Collections
Some private student loans, depending on the lender and program
Student loans: Most debt settlement programs do not settle federal student loans. Private student loans are different and can vary by lender, hardship options, and the provider’s policies. If student debt is a big part of your situation, ask directly: “Which exact student loan lenders do you work with, and are we talking about federal or private student loans?”
Secured debts: Mortgages and auto loans are different because they are tied to collateral. If your main problem is secured debt, debt settlement is often not the right tool.
Want to Compare Accredited Debt Relief?
If your debt is mostly unsecured and you’re already considering settlement, Accredited Debt Relief may be worth comparing. Just make sure you understand whether you’re being offered debt settlement, a consolidation loan, or another type of program.
Here’s the plain-English version. I’ve reviewed enough debt relief offers over the years to know that the big headline numbers are only part of the story. The process, risks, and fee structure matter just as much.
Consultation: You share your debts, budget, income, and what caused the hardship. With Accredited this is free and no-obligation.
Program recommendation: The company explains whether a settlement program, a consolidation loan, or another option may fit your profile.
Dedicated account: If you enroll in settlement, you typically deposit money into a dedicated account that is later used to fund settlement offers.
Negotiations: Settlements are usually attempted one debt at a time as funds accumulate.
Approval: In many programs, you can approve settlement offers before they are finalized. Confirm this in writing.
Fees: Reputable settlement providers generally charge fees after results, not upfront. Still, you should ask for the full fee schedule, account fees, and cancellation terms.
If you’re new to this, it’s worth knowing how to spot a bad actor. The FTC’s page on debt relief and credit repair scams explains a key red flag: legitimate providers cannot charge you a fee before they actually settle or reduce a debt, so anyone demanding a large upfront payment should be treated with caution. The CFPB’s explainer on what a debt relief program is and whether you should use one is also a good neutral starting point. And remember that canceled debt can sometimes create tax questions, so the IRS page on cancellation of debt is worth reviewing if you settle a large balance.
Pros and cons of Accredited Debt Relief
Pros
Strong third-party ratings: Accredited Debt Relief has a strong public review profile across BBB, Trustpilot, Google, and ConsumerAffairs.
BBB accreditation: BBB lists Accredited Debt Relief as accredited with an A+ rating.
Industry accreditation: Accredited is an active member of the Association for Consumer Debt Relief (ACDR), reflecting adherence to ethical industry standards.
Certified specialists: Its specialists are certified by the International Association of Professional Debt Arbitrators (IAPDA).
Both relief and loan options: Accredited evaluates clients for both a settlement program and consolidation loans, so you may be presented with more than one path.
Guided process: If you’re overwhelmed, a structured plan, 1:1 support, and a client dashboard/app for tracking can help you move forward.
Cons
Credit impact risk: Many debt relief strategies involve missed payments before resolution, which can damage credit and increase collection pressure.
Not all debts qualify: Secured debts (mortgages, auto loans) and federal student loans are usually not eligible.
Timelines vary: Marketing may highlight 24–48 months, but your budget and creditor mix determine how quickly settlements can happen.
Fees can be significant: Always ask for the full cost in writing, including settlement fees and any dedicated account fees. Results are not guaranteed.
Not available everywhere: Availability and fee caps vary by state, so confirm the program operates where you live.
Customer reviews and ratings snapshot
Ratings change over time, so treat this section as a snapshot, not a guarantee of your experience. Updated for August 2026.
Accredited Debt Relief
BBB: A+ rating and accreditation. Public customer reviews are around ★ 4.9/5. (view source)
Trustpilot: Around ★ 4.8/5 across about 11,900 reviews. (view source)
Google & ConsumerAffairs: Consistently around ★ 4.8–4.9/5 across thousands of reviews. The volume across platforms makes isolated manipulation unlikely, which is a meaningful signal.
Industry accreditation: Association for Consumer Debt Relief (ACDR). (view source)
Awards and recognition: Multiple consecutive years of customer-service and financial-wellness awards (see the full list below). I’d still treat awards as a supporting trust signal, not the main reason to enroll.
What reviews usually do not tell you: whether the program fits your specific creditor mix, monthly budget, hardship, and tolerance for credit damage. Those factors matter more than any star rating.
Company-reported client outcomes
Accredited points to a survey of its program graduates (reported as of August 2026). These are company-reported figures, so weigh them accordingly:
92% of surveyed graduates said Accredited made their payments more affordable.
8 in 10 said they would recommend Accredited to a friend struggling with debt.
Graduates reported a 42% average improvement in self-rated financial habits (from 5.7 to 8.1 out of 10).
Awards and recognition
Accredited Debt Relief has earned national recognition for customer service across multiple consecutive years. I’d treat this as a supporting trust signal, not the main reason to enroll, but the consistency is worth noting.
American Business Awards (Stevie®)
2026: Gold Stevie® Award, Customer Service Department of the Year
2026: Gold Stevie® Award, Customer Service Innovation of the Year
2026: Silver Stevie® Award, Customer Service Department of the Year
2026: Bronze Stevie® Award, Innovation in Customer Service
2025: Gold Stevie® Award, Customer Service Department of the Year in Financial Services
2024: Silver Stevie® Award, Achievement in Finance
ConsumerAffairs Buyer’s Choice Awards
2025: Best Customer Service, Best Value, and Best Overall Process
2024: Best Customer Service, Best Experience with Staff, and Best Transparency
Additional recognition
2025: Gold, Customer Service Department of the Year (Best in Biz Awards)
2025: Organization of the Year for Excellence in Customer Service (Business Intelligence Group)
2025: Financial Wellness Champion (Banking Tech Awards USA)
2025: Top 12 Best Online Platforms in Finance and Money (Newsweek)
2026: Finalist, Organization of the Year, Customer Service Award (Business Intelligence Group)
Who Accredited Debt Relief may be best for
Accredited may be a better fit if:
You have $5,000 or more in unsecured debt, especially credit cards, personal loans, or medical bills.
You are struggling to keep up with minimum payments.
You want a guided process instead of negotiating with creditors on your own.
You want to explore both settlement and consolidation loan options before committing.
You understand that settlement can hurt your credit before it helps your overall debt burden.
You can commit to a monthly plan long enough for settlements to be funded.
Accredited may not be the right fit if:
Your debt is mostly secured, such as a mortgage or auto loan.
You are current on every account and mainly want a lower interest rate.
You need legal protection quickly because of lawsuits, wage garnishment, or severe collection pressure.
You have mostly federal student loans.
You cannot afford the monthly deposits required to make settlement offers realistic.
Debt settlement vs. consolidation vs. credit counseling
One thing I’d be careful about is treating all “debt relief” offers as the same. They are not. Settlement, consolidation, credit counseling, and bankruptcy can all solve different problems.
Option
Best for
Main risk
Debt settlement
People with serious unsecured debt who cannot realistically repay balances in full.
Credit damage, collection pressure, lawsuits, fees, and tax questions on forgiven debt.
Debt consolidation loan
Borrowers with decent credit who can qualify for a lower interest rate.
You may simply move debt around without reducing the balance.
Credit counseling
People who can afford to repay debt but need lower rates, structure, and guidance.
You usually still repay the full principal balance; the plan resets if you miss a payment.
Bankruptcy
People who need legal protection or have no realistic repayment path.
Serious credit, legal, and asset-related consequences depending on your case.
Weigh the Alternatives Before You Call a Provider
Settlement is not the only route, and it is rarely the cheapest. Line it up against bankruptcy and the other options before you take a sales call, then compare the companies on their actual review scores.
Even if you like Accredited Debt Relief, it’s still smart to compare a few different routes before you commit. I’d especially compare the offer against:
CuraDebt review if your situation is more complex or includes tax debt questions.
Questions to ask Accredited Debt Relief before enrolling
Before signing up, I’d ask these questions and save the answers in writing:
Am I being offered debt settlement, a consolidation loan, or another product?
Who will actually service my plan?
Who negotiates with my creditors?
What is the full fee schedule?
Are there separate dedicated account fees?
Will I be asked to stop paying creditors?
What happens if a creditor refuses to settle?
What happens if a creditor sues me?
Can I approve or reject each settlement before it is finalized?
What happens if I cancel the program?
Does the program operate in my state, and do fee caps apply where I live?
Bottom line: Is Accredited Debt Relief legit?
Accredited Debt Relief appears to be a legitimate debt relief company with strong public ratings, BBB A+ accreditation, ACDR membership, IAPDA-certified specialists, and a substantial company-stated track record (1.3M+ clients, $15B+ resolved, 15+ years). It may be worth considering if you have significant unsecured debt and you understand the risks of debt settlement.
That said, I would not treat any provider as a magic fix. The most important thing is choosing the right path for your situation. Debt settlement can make sense for some people, but it can also hurt your credit, create collection pressure, involve fees, and lead to tax questions if debt is forgiven.
My take: start with the Debt Relief Quiz first. Then, if settlement looks like a realistic option, compare Accredited Debt Relief with at least one or two other providers before you enroll.
Ready to See What Accredited Would Offer?
The consultation is free and it does not commit you to enrolling. Ask for the fee as a percentage of enrolled debt in writing, then put that number next to one or two competitors before you sign.
Yes. Accredited Debt Relief is a DBA of Beyond Finance, LLC, with a public BBB profile, A+ accreditation, strong review profiles across major platforms, IAPDA-certified specialists, and membership in the Association for Consumer Debt Relief (ACDR).
Does Accredited Debt Relief offer loans?
Accredited is best known for debt relief and settlement-related services, but consolidation options, including loans, may be available through partners depending on your credit profile. Ask directly whether you are being offered settlement, a loan, or another type of program.
How long does Accredited Debt Relief hurt your credit?
Debt settlement can hurt your credit, especially if the strategy involves missed payments before settlements are reached. Make sure you understand the credit impact before enrolling in any settlement program.
What types of debt does Accredited Debt Relief handle?
Programs usually focus on unsecured debts like credit cards, personal loans, medical bills, and collections. Federal student loans, mortgages, and auto loans are generally not handled through typical debt settlement programs.
How much debt do you need for Accredited Debt Relief?
Accredited Debt Relief works with people who have $5,000 or more in unsecured debt. Exact eligibility depends on your income, debt type, creditors, and state.
How much does Accredited Debt Relief charge?
The initial consultation is free with no obligation. Settlement fees are success-based, calculated as a percentage of enrolled debt and charged after a settlement is reached, not upfront. They typically range from 15% to 25% and vary by state and program type.
Is debt settlement better than debt consolidation?
Not always. Debt consolidation may be better if you have decent credit and can qualify for a lower rate. Debt settlement may be more realistic if you cannot afford to repay your balances in full, but it comes with more risk. That is why I recommend starting with a neutral comparison tool like our Debt Relief Quiz.
Should I use Accredited Debt Relief or take the Debt Relief Quiz first?
I’d take the Debt Relief Quiz first. It gives you a more neutral starting point before speaking with any provider. If settlement looks like a fit, then Accredited Debt Relief is one company you can compare.
What is the most trusted debt relief company?
There is no single answer, because reputation depends on what you are measuring. On third party ratings, Beyond Finance and Accredited Debt Relief, which are the same parent company, both hold strong review profiles and BBB accreditation. On longevity, New Era Debt Solutions has one of the longest public track records in the sector. On cost, no settlement company beats a nonprofit debt management plan. The safest approach is to check the BBB complaint volume, the published fee range and the state licensing for any company you shortlist, rather than relying on a ranking.
What is the downside to Accredited Debt Relief?
The downsides are the ones built into debt settlement itself rather than anything unusual about this company. Fees run roughly 15% to 25% of enrolled debt, and that money does not reach your creditors. Your credit score falls while accounts go delinquent during negotiation, and recovery takes time after the programme ends. Creditors are never obliged to negotiate, so some accounts may not settle, and you can still be pursued by collections or sued while enrolled. Forgiven balances above $600 can be treated as taxable income. Accredited Debt Relief also does not handle secured debts such as mortgages and car loans, or federal student loans. None of that makes the company illegitimate, but it is why comparing a nonprofit credit counselling plan first is worth the hour it takes.
Which is better, National Debt Relief or Accredited Debt Relief?
They are close competitors running the same basic model, so neither is universally better. On our volume weighted score across BBB, Google and Trustpilot, Accredited Debt Relief edges ahead at 4.81 out of 5 against National Debt Relief at 4.69. Both charge in the usual 15% to 25% range of enrolled debt, both hold BBB accreditation, and both work with similar unsecured debt types. National Debt Relief is the older and larger brand with the longer public track record, while Accredited Debt Relief tends to score better specifically on customer service. In practice the deciding factors are the fee percentage each quotes against your actual balances, which of your accounts each will accept, and how plainly each puts the terms in writing. Get both quotes before you choose.
Beyond Finance (www.beyondfinance.com) is one of the largest debt consolidation companies in the United States, helping consumers resolve unsecured debts such as credit cards, personal loans, and medical bills. What sets it apart from most competitors is a built-in financial wellness program with accredited financial therapists, not just a settlement back-office.
Operating since 2011, Beyond Finance has become one of the biggest names in the debt relief industry. It is best known for its debt resolution programs, its digital dashboard, and a financial wellness offering that is genuinely unusual for this category. If you are overwhelmed by unsecured debt and looking for a structured path forward, Beyond Finance may be worth a look, but it is important to understand the fees, timeline, and risks before enrolling.
Debt resolution and consolidation for unsecured consumer debt, paired with a financial wellness program
Best For
People with significant unsecured debt who want a structured program plus financial-habit support
Track Record
Company-stated: 1.3 million+ clients helped, $15 billion+ in client debt resolved, 2,200+ team members
Related Brand
Accredited Debt Relief operates as a DBA of Beyond Finance, LLC
Important Note
Debt resolution can hurt your credit while you are in the program and is not the right fit for everyone
Quick Visual Breakdown
Each bar below shows where Beyond Finance falls on a typical industry scale, so you can see its numbers in context rather than in the abstract.
Fees: 15–25%
0%35%
Industry settlement fees generally run up to about 35% of enrolled debt; Beyond’s band sits in the typical 15–25% range and varies by state.
Program Length: 24–48 months
0 mo60 mo
Most programs run somewhere under five years; Beyond’s typical 24–48 month window is middle-of-the-pack for the category.
Minimum Debt: $5,000+
$0$25k+
The shaded zone is where you’d typically qualify: Beyond Finance is generally a fit at $5,000 and up in unsecured debt.
Financial Wellness
✓ Built into the program
Accredited financial therapists and a client dashboard are included as standard, a genuine point of difference in this category, not a measurable score.
What Makes Beyond Finance Different
Most debt relief companies do the same core thing: enroll your unsecured debt, negotiate with creditors, and help you pay off a reduced balance. Beyond Finance does that too, but it is one of the few major companies in the space to build a financial wellness program directly into the client experience, with two accredited financial therapists on staff.
The financial wellness program
Beyond Finance’s wellness offering is led by two named experts the company has publicly tied to the program:
Dr. Erika Rasure, PhD, CFT™, Beyond Finance’s Chief Financial Wellness Advisor, a Certified Financial Therapist who also serves on the financial review boards of Investopedia, The Balance, and the Verywell sites.
Nathan Astle, CFT™, a Client Financial Therapist at Beyond Finance and founder of the Financial Therapy Clinical Institute, focused on the behavioral and emotional side of money.
According to Beyond Finance, the two lead roughly five live financial wellness sessions per week for enrolled clients, alongside budgeting tools, a content library, and a client community. The idea is to address the habits behind the debt, not just the balance. Beyond reports that graduating clients rate their own financial habits at an average of 5.9 out of 10 before the program and 8.2 after, a company-reported figure, so weigh it accordingly, but a reasonable signal that the wellness piece is more than window dressing.
Whether that matters to you depends on what you want. If you only need a number negotiated down, it may not move the needle. If part of your problem is the cycle that created the debt, it is a genuine point of difference worth factoring in.
How Beyond Finance Works
1
Free Consultation
You speak with an advisor about your debt, income, and monthly budget at no cost.
2
Personalized Match
Beyond identifies whether a resolution program or a consolidation loan fits your situation.
3
Monthly Deposits
In a resolution program, you deposit into a dedicated account while the company works on settlements.
4
Settlements Reached
As creditors agree to reduced payoffs, your funds are used to resolve those debts over time.
Important reminder
Debt resolution can reduce what you owe, but it can also damage your credit.
Not every creditor will necessarily settle.
Fees matter, and your actual savings may be lower than the headline number sounds.
Large national company with strong brand recognition
Integrated financial wellness program with accredited financial therapists, rare in this category
Evaluates both resolution programs and consolidation loans, not just one product
No upfront fees in the traditional sense; fees are success-based
Helpful online dashboard and mobile access
Good fit for people with larger unsecured debt balances
Cons
Fees can still be relatively high (15–25% of enrolled debt)
Your credit score may drop during the program
Settlement is not guaranteed with every creditor
Collection activity may continue while debts are unresolved
The process can take years, not months
Not ideal if you have only a small amount of debt, or mostly secured/federal debt
Need help comparing options?
See how Beyond Finance stacks up against the rest
I ranked 14 settlement companies on their real BBB, Google and Trustpilot scores, so you can see exactly where Beyond Finance sits before you call anyone.
If you are comparing providers, here is a cleaner side-by-side look at Beyond Finance versus several other well-known debt relief companies often considered by consumers.
Company
Best For
Typical Fee Range*
Minimum Debt
Standout Feature
Beyond Finance
People who want a major brand plus financial wellness support
15% to 25%
About $5,000+
Therapist-led wellness program + digital dashboard
Consumers looking for a widely recognized settlement provider
15% to 25%
About $5,000+
DBA of Beyond Finance; large nationwide presence
Freedom Debt Relief
People who want one of the most established brands in the space
15% to 25%
About $7,500+
Long track record and scale
National Debt Relief
Consumers seeking a straightforward settlement-focused provider
15% to 25%
About $7,500+
Simple program structure
ClearOne Advantage
People comparing several mainstream settlement providers
15% to 25%
Usually around $10,000+
Common shortlist competitor
TurboDebt
People looking at newer or more aggressively marketed providers
15% to 25%
Varies
Heavy marketing visibility
*Fee ranges are broad estimates and can vary based on state, debt profile, and the specific agreement offered to you.
How Beyond Finance Stacks Up
Category
My Take
Ease of use
Strong. The dashboard and app are among its biggest advantages.
Fee competitiveness
Average to slightly expensive, depending on your offer.
Brand trust
Strong overall, with a large public review footprint.
Differentiation
High. The therapist-led wellness program is genuinely uncommon in this category.
Biggest caution
Resolution can hurt your credit and may take several years to complete.
Ratings and Reviews
Beyond Finance has one of the largest combined review footprints of any debt relief company in the country. Ratings change over time, so treat this as a snapshot as of August 2026.
Platform
Rating
Reviews
Google
★ 4.6 / 5
26,000+ reviews
Trustpilot
★ 4.6 / 5
22,900+ reviews
Better Business Bureau
★ 4.8 / 5
13,000+ reviews; A+ accreditation
ConsumerAffairs
★ 4.7 / 5
4,000+ reviews
App stores (iOS / Google Play)
★ 4.7–4.9 / 5
25,000+ combined ratings
What reviews say most often: responsive client support, real relief from monthly payment pressure, and appreciation for the financial wellness resources. Common concerns: timelines that feel long and a wish for clearer fee communication upfront, which is exactly why you should get a written fee schedule before you sign.
Publisher Rankings and Awards
Beyond Finance is regularly cited among the top debt relief companies by independent publishers, including being named #1 for customer service by Investopedia, Best Overall 2025 by Finder.com, and earning recognition from Forbes, CBS News, CNBC, and Bankrate. It has also won multiple Gold Stevie® Awards for customer service across 2024–2026 and several ConsumerAffairs Buyer’s Choice Awards. I’d treat publisher rankings and awards as a supporting trust signal, not the main reason to enroll. They reflect customer service and visibility, not whether settlement is the right tool for your specific debt.
Still undecided?
Nonprofit counseling costs a fraction of settlement
If you are on the fence about Beyond Finance, do not guess. A nonprofit credit counseling agency will review your budget for free and can often cut your interest rate without the credit damage settlement causes.
Borrowers who are struggling to keep up with minimum payments
Consumers who want a structured program plus support for building better financial habits
People who value a client dashboard, mobile app, and access to financial wellness resources
Borrowers who understand the risks of debt resolution and still want to explore it
Who Should Think Carefully Before Enrolling
People with only a small amount of debt
Consumers who can still qualify for a good debt consolidation loan
Anyone trying to protect their credit score in the near term
People who may not be able to stay consistent with monthly program deposits
Borrowers whose debt is mainly secured, tax-related, or federal student loan debt
My Take on Beyond Finance
Beyond Finance is a legitimate and well-known debt relief company, and I can see why it lands on a lot of shortlists. It is large: the company says it has helped 1.3 million+ clients and resolved over $15 billion in debt, the dashboard is a genuine plus, and the financial wellness program, with two accredited financial therapists actually built into the client experience, is something most competitors simply do not offer.
That said, debt resolution is never something I would jump into casually. Even with a reputable company, the process itself can hurt your credit, take years, and cost more than many consumers expect once fees are factored in. The wellness program is a real differentiator, but it does not change the underlying math of settlement. That is why I think the smartest first move is to weigh settlement against bankruptcy and the other routes before committing to any specific provider.
FAQ About Beyond Finance
Is Beyond Finance legit?
Yes. Beyond Finance is generally considered a legitimate debt relief company, operating since 2011, with an A+ BBB accreditation and a large public review footprint across Google, Trustpilot, BBB, and ConsumerAffairs.
When was Beyond Finance founded?
Beyond Finance has been helping people since 2011 and is headquartered in Chicago, Illinois. (Its sister brand, Accredited Debt Relief, operates as a DBA of Beyond Finance, LLC.)
What makes Beyond Finance different?
Its integrated financial wellness program. Beyond Finance has two accredited financial therapists, Dr. Erika Rasure and Nathan Astle, who lead regular live wellness sessions for clients, alongside budgeting tools and educational content. That focus on financial habits, not just the debt balance, is uncommon in this industry.
How much does Beyond Finance cost?
Fees are success-based with no upfront charge, typically falling in the 15% to 25% range of enrolled debt. Your exact offer can vary by state and personal profile, so always get the full fee schedule in writing.
How long does it take Beyond Finance to pay off debt?
Many debt resolution programs, including Beyond Finance, commonly take around 24 to 48 months depending on your total enrolled debt and monthly contribution.
Will my credit score be affected?
It can be. Debt resolution often involves missed or reduced payments before settlements are completed, which can negatively affect your credit score. Understand the specific impact before enrolling.
Does Beyond Finance evaluate for loans?
Yes. In addition to debt resolution programs, Beyond Finance evaluates consolidation loan options as part of its matching process. Which one fits depends on your credit profile and situation.
Is Beyond Finance accredited?
Yes. Beyond Finance holds an A+ accreditation with the Better Business Bureau and is a member of the Association for Consumer Debt Relief (ACDR). Its debt specialists are IAPDA-certified.
What should I do before signing up?
Before enrolling with any provider, I recommend checking whether you can clear the balances yourself first, then comparing resolution against the other options.
Is Beyond Finance a good idea?
It depends on your situation, and it is worth being clear-eyed. Beyond Finance tends to suit someone carrying several thousand dollars of unsecured debt with genuine hardship and no realistic path to paying the balances in full. It is a poor fit if you could clear the debt yourself within a few years, if what you owe is mostly secured debt or federal student loans, or if you cannot tolerate a credit score hit and collection calls while accounts are negotiated. Debt settlement damages your credit while it works, and creditors are never obliged to settle. Before signing, get the fee schedule in writing, confirm exactly which accounts are enrolled, and compare a nonprofit credit counseling debt management plan so you know what the alternative costs.
Final takeaway
Worth a call if the wellness support appeals to you
The consultation is free and it does not commit you to enrolling, so there is little downside to hearing what they would offer on your balances. Get the fee quote in writing and call one or two others before you sign anything.
Editorial note: This review is for informational purposes only and should not be considered legal, tax, or financial advice. Debt resolution has pros and cons, and it may not be the best fit for every consumer.
Logo of New Era Debt Solutions (credit: neweradebtsolutions.com)
New Era Debt Solutions (https://neweradebtsolutions.com/) is a well-established, legitimate debt settlement company (NOT a credit counselor) that’s been helping people get out of debt since 1999, which makes it one of the oldest debt settlement providers in America. Based in Camarillo, California, they operate nationwide (EXCEPT Maine, Oregon, and Iowa), and specialize in negotiating with creditors to settle unsecured debts, like credit card debt, personal loans and others for less than what you owe.
New Era Debt Solutions takes the #1 spot in our debt relief company rankings this year due to their combined score of 4.84/5 stars, at time of press, as you can see below. This objective score takes into account their ratings on multiple third-party review sites, like the BBB, Google Reviews, TrustPilot and others.
New Era Debt Solutions has a good profile on Google reviews
What Services Does New Era Debt Offer?
New Era primarily offers debt settlement services, meaning they work with your creditors to reduce the total amount you owe. This service is specifically for unsecured debt (like credit cards, medical bills, personal loans and certain other types of debt). Their service cannot help for things like mortgages or student loans.
New Era Debt aims to create a plan that helps you become debt-free in as little as 24 to 48 months. One of the standout aspects of New Era is that they don’t charge any upfront fees. You only pay them when they’ve successfully settled your debt and you have agreed with their plan.
New Era Debt vs Others
It’s important to note that New Era Debt Solutions is a debt settlement company, not a credit counseling nonprofit. Therefore, they don’t do Debt Management Plans (DMP’s) and instead they simply negotiate with your creditors to settle for a much lower debt. This means you will take a credit score hit, but much lesser than that of a bankruptcy’s. Their service is similar to companies like CuraDebt, TurboDebt, Accredited Debt Relief and others.
If you’re wondering how New Era Debt compares to other providers who may offer similar (but different) options on how to deal with your debt, see the table below:
Feature / Factor
New Era Debt Solutions
Family Credit Management (FCM)
Bankruptcy (Chapter 7)
Type of Program
Debt Settlement
Debt Management Plan (DMP)
Legal Debt Discharge
Typical Debt Reduction
30–60% of enrolled debt
Interest reduction only
Up to 100% (full discharge)
Upfront Fees
❌ None
✅ Usually $0–50 setup fee
✅ Court & lawyer fees (~$1,500–$2,000)
Ongoing Fees
14%–23% of enrolled debt (only if settled)
$25–$75/month (varies by state)
❌ None after filing
Impact on Credit Score
❌ Negative (missed payments + settlement)
⚠️ Neutral to slightly negative
❌ Severe (stays for 7–10 years)
Time to Completion
24–48 months
36–60 months
~6 months (Chapter 7)
Covered Debts
Unsecured (credit cards, personal loans)
Unsecured (credit cards, medical, etc.)
Most unsecured debts
Creditor Negotiation
✅ Negotiates balance reductions
✅ Negotiates lower interest rates
❌ No negotiation, legal discharge
Eligibility Requirements
Must have financial hardship
Verifiable income + willingness to pay
Must pass a means test
Credit Counseling Required?
❌ No
✅ Yes
✅ Yes (pre-filing requirement)
Legal Protection from Creditors?
❌ No (until settled)
❌ No (voluntary plan)
✅ Yes (automatic stay)
Best For…
Settling large unsecured debts without bankruptcy
Paying debts in full with lower interest
Wiping out debts with no repayment
NOTE: make sure you study all the options above to find the right method to tackle your debt. They all have their pros and cons, depending on your situation.
If you’re comparing debt relief options and want to understand how settlement might apply to your debt, you can use New Era’s free assessment tool to get a clearer picture.
In terms of reputation, New Era Debt Solutions has solid reviews across multiple platforms, as we covered earlier in the “company’s snapshot” section. They hold an A+ rating with the Better Business Bureau (BBB).
On Trustpilot, they’ve received mostly positive reviews, with customers praising them for professionalism and their ability to reduce large amounts of debt. Like any company, there are a few negative reviews, but those are often about the downsides of debt settlement itself (such as its impact on credit scores), rather than the company’s service.
Management Team
New Era’s CEO, Dan Smith, has a strong background in finance and a focus on ethical, transparent practices. The company is committed to not only helping clients get out of debt but also educating them on how to stay out of it in the future. They pride themselves on being a debt settlement company that actually does the work in-house. They do not outsource anything, so you’re always dealing with New Era directly.
Which States Do They Cover?
New Era Debt Solutions serves clients across the United States, except in the states of Maine, Oregon, and Iowa as we covered in the beginning of this article. This may change in the future, so it’s always a good idea to fill out their pre-qualification form to see if your address allows debt settlement and if New Era operates there.
What’s the Process Like?
When you sign up, you’ll first have a consultation to review your financial situation. After that, they’ll create a plan tailored to your debt and begin negotiating with your creditors. You’ll make monthly payments into an escrow account while New Era works to settle your debts for less than what you owe. It’s a fairly straightforward process, but as with any debt settlement plan, it’s important to know that your credit score will take a hit. While under negotiation, there are also risks like collection calls or lawsuits.
Is New Era Debt Solutions Right for You?
New Era Debt Solutions has been around for over 20 years, and their track record, coupled with strong reviews and no upfront fees, makes them a legitimate option if you’re considering debt settlement. They are especially appealing if you’re struggling with large amounts of unsecured debt and need an alternative to bankruptcy. That said, debt settlement isn’t for everyone, make sure to understand the pros and cons before diving in.
If you’re dealing with overwhelming debt due to this high-inflation economic landscape, and are looking for a company that can help you decrease and/or pay off your debt, and has a great reputation, New Era could be the right fit for you. Make sure you take advantage of their free consultation to ask which of their various debt relief options is best for you.
FAQ
Here’s a frequently asked questions (FAQ) section covering the most common questions new users have about New Era Debt Solutions:
1. How much does New Era Debt Solutions charge?
New Era charges between 14% and 23% of the initial enrolled debt amount. There are no upfront fees; they only get paid when they successfully negotiate a debt reduction. This is a contingency-based fee structure.
2. What types of debt does New Era handle?
They handle unsecured debts like credit card debt, personal loans, private student loans, medical bills, and some types of business debts. They do not handle secured debts like mortgages or car loans.
3. Will using New Era affect my credit score?
Yes, debt settlement, regardless of which company you choose to work with, will negatively impact your credit score. Settling a debt means paying less than the full amount owed, which creditors deem a negative event. However, the impact is less damaging than bankruptcy.
4. Is New Era Debt Solutions accredited and reputable?
Yes, New Era has BBB accreditation and has an A+ rating. They have generally positive reviews from clients on platforms like TrustPilot and the BBB website.
5. Where is New Era available?
New Era is accessible in 46 states as well as Washington D.C. and the Virgin Islands. They do NOT operate in Maine, Oregon, and Iowa.They collaborate with the Consumer First Legal Network to offer services in certain states where they may not directly operate.
6. What happens if a creditor refuses to settle?
If a creditor refuses to negotiate, they could potentially take legal action, which might result in lawsuits or wage garnishments. However, most creditors prefer to negotiate rather than pursue costly legal action.
7. How long does the debt settlement process take?
The typical debt settlement program with New Era takes around 28 months. The exact duration depends on the amount of debt, your monthly contributions, and how quickly creditors agree to settlements.
8. Can I cancel my program with New Era Debt Solutions?
Yes, clients can cancel their program with New Era at any time. However, any funds put towards fees or those that are in the dedicated account may be subject to the terms of the cancellation agreement.
Debt relief isn’t one-size-fits-all. If you’re considering settlement, it might be worth seeing if you qualify through a no-pressure consultation with New Era.
Amine Rahal
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.
Lauren Brown
Lauren has over 13 years of experience in wealth management and financial planning. She is a CFA charterholder and holds a Bachelor’s degree in Finance. Lauren has worked with several asset management firms, offering wealth advisory and portfolio management services to high-net-worth clients.
Sponsored. The NFCC is the oldest and largest nonprofit counseling network in the US. The session costs nothing, it does not touch your credit, and it routes you to a vetted member agency near you. We may earn a commission at no extra cost to you, and it does not affect the rankings below.
Worth knowing: five of the eight agencies ranked below are NFCC members, so this is the quickest way to reach a vetted one without picking from the table yourself.
I have been writing about household debt and consumer prices for the better part of twenty years, and credit counseling is still the thing readers get wrong most often. People email me assuming it is a company that makes their debt disappear, or they assume the word “nonprofit” is a guarantee of something. It is neither. Credit counseling is a sit down with a trained counselor who looks at your actual numbers and tells you what your realistic options are, and the session itself is usually free. What comes after that session, the debt management plan, is the part that carries a fee, and that distinction is where most of the confusion lives.
Not sure whether counseling, consolidation or settlement fits your situation?
Our two minute quiz walks through income, debt load and what you have already tried, then points you at the option that actually matches. No phone number required.
The Consumer Financial Protection Bureau draws the cleanest line I have seen. Credit counselors are “usually nonprofit organizations that advise you on managing your money and debts”, while debt settlement and credit repair firms are “typically for-profit companies that promise to fix your credit and debts.” Counselors aim to lower your monthly payment. Settlement firms aim to reduce what you owe. Those are different goals with very different consequences.
A counseling session covers your income, your bills, your credit reports and your spending. The counselor pulls your reports as a soft inquiry, so nothing about that first conversation touches your score. At the end you get a written budget and a recommendation, which is roughly how the CFPB describes the process too. Sometimes that recommendation is a debt management plan. Often it is not, and I think that is the most underrated thing about the whole category: a good counselor will tell you that you do not need them.
The CFPB lists one trait that separates a legitimate counselor from everyone else, and it is worth committing to memory. A real counselor will never advise you to stop paying your debts. Settlement companies routinely do exactly that, which is how clients end up with collection calls, late fees and occasionally a lawsuit while their settlement fund slowly builds.
What is genuinely free, and what is not
This is the part worth being precise about, because “free credit counseling” is a real thing and also a phrase that gets used loosely.
Service
Typical cost
Notes
Initial counseling session
Free
Budget review, credit report walkthrough, written action plan. No obligation to enroll in anything.
Educational materials and workshops
Free
Budgeting guides, housing and student loan resources at most member agencies.
Debt management plan setup
$35 to $75 once
Capped by state law in many places. Waived or reduced for hardship at most agencies.
Debt management plan monthly fee
$25 to $50 a month
Often charged per enrolled account with a monthly ceiling. Folded into your single payment.
Pre-bankruptcy counseling certificate
$0 to $50
Required by the court. Fee waivers available below certain income thresholds.
So the honest answer to “is credit counseling free” is yes for the advice, no for the ongoing plan. Anyone charging you for the first conversation is not operating the way the established agencies do, and I would walk.
What a debt management plan actually costs
Agencies publish their fees inconsistently, which I find irritating and which is why I keep a comparison on hand. Here is where the better known agencies landed as of this year.
Agency
Setup fee
Average monthly
Stated cap
American Consumer Credit Counseling
$39
$25
$7 per account, $70 monthly ceiling
Cambridge Credit Counseling
$40
$30
$75 setup, $50 monthly
GreenPath Financial Wellness
$35
$28 to $31
Varies by state
Money Management International
$38
$27
$75 setup, $69 monthly
Take Charge America
Varies by state
Disclosed at enrollment
No published national schedule
Set that against what the plan is doing for you. Cambridge reports pulling average card rates from roughly 22 percent down to 8 percent, which it says saves a typical client about $140 a month. Money Management International says its average client in 2024 avoided more than $48,000 in total interest across the life of the plan. Those are agency figures rather than independent audits, so treat them as directional, but the mechanism is real: creditors grant concessions on plans they trust, and a $30 monthly fee against a $140 monthly saving is not a close call.
One thing the fee tables never mention. Plans run three to five years, and the single most common reason people fall off one is a car repair or a medical bill in year two. If you have no cushion at all, say so in the counseling session. A good agency will build a smaller plan around that rather than set you up to fail.
Counseling is the free first step. Settlement is not always the wrong one.
The quiz sorts which camp you are actually in before anyone asks you for a fee or a signature.
Enrolling in a plan is a different story. You will usually have to close the enrolled card accounts, and closing accounts shortens your available credit, so expect a dip in the first few months. The NFCC cites one member agency whose clients gained an average of 106 points over their first three years on a plan. I would hold that number at arm’s length, since the NFCC represents counseling agencies and the figure comes from a single member, but the direction is not controversial. Paying down balances on time for three years improves scores. That is just how the models work.
What matters more is the comparison. A debt management plan dings your score temporarily and then rebuilds it. Settlement requires you to go delinquent first, which does real damage that sits on your report for years, and bankruptcy does more. If you are weighing those against each other, I wrote a longer piece on bankruptcy versus debt relief that walks through where each one stops making sense.
Nonprofit status is not the quality signal you think it is
Notice the CFPB says counselors are “usually” nonprofit. Not always. And nonprofit status is a tax classification, not a quality rating. I have seen nonprofit agencies with aggressive sales scripts and I have seen for-profit firms behave well. The tax status tells you almost nothing on its own.
What does tell you something is accreditation and membership. Two bodies matter in the United States: the National Foundation for Credit Counseling and the Financial Counseling Association of America. Both set standards on counselor certification, fee disclosure and how agencies are funded. Separately, the Council on Accreditation audits agency operations. An agency carrying all three is not automatically right for you, but it has been inspected by people who do this for a living. We have a full breakdown of who the NFCC is and whether they can actually help with debt, including how the referral process works.
Here is the vetting checklist I actually use:
Ask what the first session costs. The answer should be nothing.
Ask for the fee schedule in writing before you enroll. Agencies that will not put it in writing are telling you something.
Ask whether they are paid by creditors. Most are, partially. That is normal and disclosed. Evasiveness is the problem, not the arrangement.
Ask what happens if you miss a payment. Good agencies have a process. Weak ones have a script.
Check that nobody suggests you stop paying creditors. This is the single clearest red flag in the entire category.
Confirm NFCC or FCAA membership on the organization’s own site, not just on the agency’s marketing page.
Agencies we have reviewed
These are the counseling organizations we have looked at in depth, with the third party ratings that were current when we last checked each one.
Means tested fees, and mortgage default counseling alongside cards
When counseling is the wrong tool
I would rather lose a reader than push them into the wrong program, so here is the honest boundary.
A debt management plan works when you can afford your debts at a lower interest rate but not at your current one. It does not reduce the principal. If your unsecured balances are so far beyond your income that a thirty to forty percent interest reduction still leaves you underwater, counseling will tell you that, and the realistic paths become settlement or bankruptcy.
If settlement turns out to be the honest answer for your numbers, two of the companies in our ranked list of debt settlement companies consistently score best in our testing. Beyond Finance suits people who want one predictable monthly payment, and Accredited Debt Relief charges nothing until a debt is actually settled. Both quote for free, and getting a second opinion costs you nothing but a phone call. If creditors have already filed against you, that is a different conversation again, and our rundown of debt consolidation lawyers and attorneys is the better starting point.
Everything else we publish on this topic lives in the debt relief section, including state by state program guides.
Start with the free conversation
A counseling session costs nothing, does not touch your credit score and carries no obligation. If you want to know which direction to point first, the quiz takes two minutes.
The 8 credit counseling agencies we track, ranked by reviews
These used to sit at the bottom of our settlement rankings, which was never the right home for them. A nonprofit putting you on a debt management plan and a settlement firm negotiating your balance down are different products with different risks. Scored the same way: live BBB, Google and Trustpilot ratings, equal weight per source, any source under 30 reviews excluded, ties broken by counted review volume.
Figures in brackets are review counts. Greyed-out sources fall below the 30-review minimum. InCharge edges GreenPath on the volume tiebreak, 2,707 counted reviews against 2,428.
Most of the agencies below are members of the NFCC, and the one readers ask about most has its own write-up: our Money Management International review. If you are still weighing counseling against the alternatives, take the 60-second quiz before you call anyone.
The ACCC is technically NOT a debt settlement company. They are a credit counseling agency that focuses on providing DMPs (aka Debt Management Plans) to help you better manage and repay your debt. The disadvantage is that DMPs don’t decrease your debt.
Our score: 4.99/5★★★★★
BBB: 4.98/5 ★★★★★ from 1,927 reviews
Google: 5.00/5 ★★★★★ from 4,569 reviews
Trustpilot: 3.6/5 ★★★★☆ from 3 reviews (below our 30-review minimum, not counted)
DebtHelper is yet another Florida-based debt counseling agency. Based on our review of their website, they don’t seem to offer debt settlement or consolidation programs. Instead, they focus on counseling, DMP’s and financial education. They put a special emphasis on credit cards, housing and student debts.
Consolidated Credit has a flat monthly fee for its debt relief program. They charge a one-time setup fee ranging from $50 to $75, and their monthly service fee is about $30. They don’t advertise any minimum debt.
Our score: 4.85/5★★★★★
BBB: 5.00/5 ★★★★★ from 2 reviews (below our 30-review minimum, not counted)
Money Management International is one of the fastest-growing debt relief companies, and have acquired many other smaller debt relief providers, such as Debt Advisors of America. They provide debt management plans at a unique monthly fee structure that is different from most of the other companies we reviewed.
Incharge is a Florida-based debt management company that offers credit counseling, debt consolidation and more. Unlike many companies reviewed on this page which require a minimum 10k debt to work with you, InCharge advertises a “no minimums”.
GFW works nationwide and can help settle your debt with multiple creditors, including banks, credit unions, retailers, medical providers, auto finance agencies, and collection agencies.
Founded in New Jersey, Navicore is a nonprofit that assists clients in terms of debt management plans, credit counseling, housing counseling and more. Similar to the ACCC, Navicore focuses strictly on providing advice and guidance. They don’t offer debt settlement, consolidation or any other debt relief program.
Our score: 4.45/5★★★★☆
BBB: 4.27/5 ★★★★☆ from 11 reviews (below our 30-review minimum, not counted)
Based in Ohio, Trinity Debt Management is a Christian debt management company that offers credit counseling, budgeting help, financial education, debt settlement and more. They don’t advertise their minimums and their fees.
Our score: 2.65/5★★★☆☆
BBB: no profile found
Google: 4.00/5 ★★★★☆ from 34 reviews
Trustpilot: 1.3/5 ★☆☆☆☆ from 181 reviews
Reviews counted: 215 across 2 sources
Flag: No active BBB profile
Certifications: N/A
If a repayment plan is not what you need, our debt settlement rankings cover the firms that negotiate balances down, and our tax relief company rankings cover IRS and back-tax problems.
Frequently asked questions
Is credit counseling really free?
The initial session is free at every established agency, and so are the educational materials. You pay only if you enroll in a debt management plan, which typically costs a one time setup fee of $35 to $75 and a monthly fee of roughly $25 to $50. If an agency wants payment before it has even looked at your budget, that is not how the reputable ones operate.
What is the difference between credit counseling and debt settlement?
Credit counseling lowers your monthly payment by getting creditors to reduce interest rates while you repay the full balance. Debt settlement tries to reduce the balance itself by negotiating a lump sum, which usually requires you to stop paying first. The CFPB describes counselors as usually nonprofit advisers and settlement firms as typically for-profit companies. Counseling protects your credit; settlement damages it in exchange for a smaller total.
Does credit counseling hurt your credit score?
The counseling session does not. The counselor pulls your reports as a soft inquiry, which has no effect. Enrolling in a debt management plan usually means closing the enrolled accounts, which causes a short term dip. The NFCC cites one member agency whose clients averaged a 106 point gain over three years on a plan. That figure comes from an interested party, but the pattern of a short dip followed by recovery is well established.
How long does a debt management plan take?
Three to five years in almost all cases. Some people finish early by paying more than the required amount, and there is no penalty for doing so. If an agency quotes you something dramatically shorter, ask exactly how, because the math rarely supports it.
What debts can go into a debt management plan?
Unsecured debts: credit cards, store cards, unsecured personal loans, some medical bills and certain collection accounts. Mortgages, car loans, federal student loans and tax debt do not qualify, because those creditors either hold collateral or have their own statutory programs.
Is a nonprofit credit counseling agency always better than a for-profit one?
No. Nonprofit is a tax classification, not a quality rating, and the CFPB only says counselors are “usually” nonprofit. What actually signals quality is accreditation: membership of the NFCC or the FCAA, and an operational audit by the Council on Accreditation. Check those on the accrediting body’s own website rather than trusting a badge on the agency’s homepage.
Do I have to close my credit cards?
The accounts you enroll, yes, in nearly every case. Creditors grant the reduced interest rate on the condition that the account stops being used. Cards you leave off the plan usually stay open, though some issuers close them anyway once they see a plan reported. Plan on losing access to the enrolled cards for the duration.
How are credit counseling agencies paid if the advice is free?
Partly by your monthly plan fee and partly by creditors, who return a small percentage of what the agency collects on their behalf. This arrangement is long standing and disclosed. It is worth asking about directly, not because the funding is improper but because an agency that gets cagey about a normal question will probably be cagey about the ones that matter.
Can credit counseling stop collection calls?
Often, once a plan is active and payments are landing. The CFPB notes that counselors can arrange payment plans that may stop collection efforts and late fees while you remain on the plan. It is not instant and it is not a legal shield. If you are already being sued, you need a lawyer, not a counselor.
What happens if I miss a payment on my plan?
One missed payment is usually recoverable if you call the agency before the due date passes. Repeated misses can cause creditors to withdraw the concessions, which puts your original interest rates back. This is the main reason I push people to be honest about their real monthly surplus during the counseling session rather than the optimistic one.
Sources: Consumer Financial Protection Bureau guidance on credit counseling and debt relief, National Foundation for Credit Counseling, and published agency fee schedules. Fee figures reflect the most recent published schedules at the time of writing and vary by state.
Sponsored. CuraDebt runs a free consultation and connects you with an independent tax resolution provider. We may earn a commission at no extra cost to you, and it does not affect the ranking below.
Before you sign anything: tax relief firms quote a flat fee per case, commonly $1,000 to $5,000 and up, and some price it as a percentage of what you owe. That number is negotiable. Get quotes from two or three firms and tell each one what the others offered.
Ten tax relief companies, scored on their live BBB, Google and Trustpilot ratings.
The 10 best tax relief companies of 2026, at a glance
Pulled fresh in November 2026. Ratings move, so check the live profiles before you hand anyone money. If your problem is really consumer debt rather than tax debt, you want our debt settlement rankings or the credit counseling guide instead.
Figures in brackets are review counts. Greyed-out sources fall below our 30-review minimum and are excluded from the score. Every firm above holds an A+ BBB grade except Tax Relief Advocates and Optima Tax Relief, where we scored the customer reviews only.
The fee is negotiable. Most people never ask.
Tax relief is quoted per case, not off a price list. Two firms looking at the same $45,000 IRS balance will quote you numbers that are thousands of dollars apart, and the one who quotes first is rarely the cheapest. Some price it as a percentage of what you owe instead, typically in the 10 to 25 percent range.
So before you hand anyone a retainer:
Call two or three, never one. Consultations are free. The second quote is the only leverage you will ever have.
Get the total in writing. Ask what the flat fee covers, what triggers an extra charge, and what happens if the IRS says no.
Say the other numbers out loud. Tell each firm what the others quoted. Discounting beats losing the case.
Ask who actually does the work. You want an enrolled agent, CPA or tax attorney on your file, not just a salesperson.
And know that you may not need any of them. The IRS publishes its own Offer in Compromise process, and the application fee is $205, waived if you are low income. The FTC warns that firms charging upfront for promised relief can leave people deeper in debt than they started.
I have been writing about consumer debt for more than twenty years, and tax debt is the corner of it where people get hurt worst. The marketing promises pennies on the dollar. The reality is that most of what these firms do, you could technically do yourself on the IRS website for free, and a meaningful share of callers would be better off doing exactly that. What you are really buying is someone who knows the forms, the thresholds and the negotiators.
So this list does one narrow, useful thing: it ranks the firms by what their actual customers say across three independent review platforms, with the figures printed so you can check them. No “editor’s choice”, no mystery scoring.
How we scored these companies
Three sources, equal weight, published figures. It is the same method we use on our settlement rankings, and it is deliberately dull:
Three sources. Live customer ratings from the Better Business Bureau, Google and Trustpilot.
Equal weight. Each counts for one third. Weighting by review volume just hands the ranking to whichever platform a firm has farmed hardest.
A 30-review minimum. Any source below 30 reviews is excluded. Fortress Tax Relief loses its Trustpilot score that way, on 16 reviews.
Volume breaks ties. TaxRise and Community Tax both land on 4.38. TaxRise ranks higher on 13,955 counted reviews against 1,875.
No paid placement. Nobody on this list pays us. The only sponsored link on this page is the CuraDebt consultation box, and it sits outside the ranking.
One caveat I want to put plainly, because the star ratings hide it: a glowing review usually reflects how the sales call felt, not whether the IRS actually accepted anything. Forgiven tax debt can also come back as taxable income in some situations. Read the BBB complaints, not just the averages.
The 10 best tax relief companies of 2026, reviewed
1. Precision Tax Relief (4.91/5)
Logo of Precision Tax Relief (credit: precisiontaxrelief.com)
A small Idaho firm that has quietly built the best review profile in this category. Flat fee quoted upfront, and the Trustpilot sample is unusually deep for a shop this size. The BBB sample is thin at 50 reviews, so weigh the 2,117 Trustpilot reviews more heavily.
Our score: 4.91/5★★★★★
BBB: 4.92/5 ★★★★★ from 50 reviews
Google: 4.9/5 ★★★★★ from 337 reviews
Trustpilot: 4.9/5 ★★★★★ from 2,117 reviews
Reviews counted: 2,504 across 3 sources
BBB grade: A+
2. Fortress Tax Relief (4.85/5)
Logo of Fortress Tax Relief (credit: taxfortress.com)
Attorney-led, based in Bend, Oregon, and it trades as Fortress Financial Services on its BBB profile. A perfect 5.00 BBB average, but on only 46 reviews, and its Trustpilot profile is too small to count. Strong signal, small sample.
Our score: 4.85/5★★★★★
BBB: 5.00/5 ★★★★★ from 46 reviews
Google: 4.7/5 ★★★★★ from 164 reviews
Trustpilot: 4.2/5 ★★★★☆ from 16 reviews (below our 30-review minimum, not counted)
Reviews counted: 210 across 2 sources
BBB grade: A+
Flag: Smallest sample on this page, 210 counted reviews
3. Larson Tax Relief (4.70/5)
A family-run Colorado firm that leans toward business tax problems, payroll tax in particular. Consistent across all three platforms, which is rarer here than you would think.
Our score: 4.70/5★★★★★
BBB: 4.89/5 ★★★★★ from 74 reviews
Google: 4.5/5 ★★★★★ from 256 reviews
Trustpilot: 4.7/5 ★★★★★ from 404 reviews
Reviews counted: 734 across 3 sources
BBB grade: A+
4. Anthem Tax Services (4.61/5)
Logo of Anthem Tax Services (credit: anthemtaxservices.com)
Long-running California firm with solid scores across the board. Worth knowing that it carries two separate BBB profiles and they disagree on accreditation status, so check which one you are reading.
Our score: 4.61/5★★★★★
BBB: 4.73/5 ★★★★★ from 223 reviews
Google: 4.5/5 ★★★★★ from 859 reviews
Trustpilot: 4.6/5 ★★★★★ from 368 reviews
Reviews counted: 1,450 across 3 sources
BBB grade: A+
Flag: Two BBB profiles exist and they disagree on accreditation
5. Five Star Tax Resolution (4.46/5)
Logo of Five Star Tax Resolution (credit: fivestartaxresolution.com)
Costa Mesa outfit with good BBB and Google scores and a thin Trustpilot presence. Its BBB accreditation is recent rather than long-standing. Read our full Five Star Tax Resolution review.
Our score: 4.46/5★★★★☆
BBB: 4.69/5 ★★★★★ from 84 reviews
Google: 4.7/5 ★★★★★ from 203 reviews
Trustpilot: 4.00/5 ★★★★☆ from 45 reviews
Reviews counted: 332 across 3 sources
BBB grade: A+
6. TaxRise (4.38/5)
Logo of TaxRise (credit: taxrise.com)
One of the biggest advertisers in the category, and the volume shows: nearly 14,000 counted reviews. The spread is the thing to notice, 4.7 on Google against 4.0 on Trustpilot, which usually means the post-sale experience is less uniform than the marketing.
Our score: 4.38/5★★★★☆
BBB: 4.44/5 ★★★★☆ from 2,304 reviews
Google: 4.7/5 ★★★★★ from 9,282 reviews
Trustpilot: 4.00/5 ★★★★☆ from 2,369 reviews
Reviews counted: 13,955 across 3 sources
BBB grade: A+
7. Community Tax (4.38/5)
Logo of Community Tax (credit: communitytax.com)
Jacksonville-headquartered, no minimum balance, and unusually consistent at roughly 4.4 on all three platforms. Not spectacular, but nothing hidden either.
Our score: 4.38/5★★★★☆
BBB: 4.34/5 ★★★★☆ from 153 reviews
Google: 4.4/5 ★★★★☆ from 844 reviews
Trustpilot: 4.4/5 ★★★★☆ from 878 reviews
Reviews counted: 1,875 across 3 sources
BBB grade: A+
8. Tax Relief Advocates (4.35/5)
Logo of Tax Relief Advocates
Heavy Google presence at 8,495 reviews and a 4.7 average there, pulled down by a weaker BBB customer score of 4.15 across 1,794 reviews. Read our full Tax Relief Advocates review.
Our score: 4.35/5★★★★☆
BBB: 4.15/5 ★★★★☆ from 1,794 reviews
Google: 4.7/5 ★★★★★ from 8,495 reviews
Trustpilot: 4.2/5 ★★★★☆ from 298 reviews
Reviews counted: 10,587 across 3 sources
9. Optima Tax Relief (4.29/5)
Logo of Optima Tax Relief (credit: optimataxrelief.com)
The most recognisable name in tax relief and the most reviewed, with over 13,000 counted. Also the lowest BBB customer average on this page at 4.08, which is the gap between brand awareness and satisfaction. Read our full Optima Tax Relief review.
Our score: 4.29/5★★★★☆
BBB: 4.08/5 ★★★★☆ from 2,006 reviews
Google: 4.3/5 ★★★★☆ from 5,745 reviews
Trustpilot: 4.5/5 ★★★★★ from 5,298 reviews
Reviews counted: 13,049 across 3 sources
10. Tax Defense Network (4.25/5)
Logo of Tax Defense Network (credit: taxdefensenetwork.com)
Also trades as MoneySolver. Lowest composite here, dragged down by a 4.1 Google average across 1,379 reviews.
Our score: 4.25/5★★★★☆
BBB: 4.35/5 ★★★★☆ from 849 reviews
Google: 4.1/5 ★★★★☆ from 1,379 reviews
Trustpilot: 4.3/5 ★★★★☆ from 618 reviews
Reviews counted: 2,846 across 3 sources
BBB grade: A+
Flag: Also trades as MoneySolver
Not sure tax relief is what you actually need?
Plenty of people who call a tax relief firm are really carrying consumer debt with a tax bill sitting on top of it. Those are different problems with different fixes, and hiring the wrong specialist is an expensive way to find that out. If credit cards are the bigger number, settlement, consolidation, counseling or bankruptcy may fit better.
Every firm on this page is selling access to processes the IRS already publishes. That does not make them worthless, but it does mean you should know what you are paying someone else to do:
Under roughly $10,000 owed? An IRS installment agreement is usually available directly and costs a fraction of a firm’s fee. Most firms will not take the case anyway.
Behind on filing? File the missing returns first. Almost nothing is negotiable until you are compliant, and firms will charge you to hear that.
Hoping for pennies on the dollar? An Offer in Compromise is a real programme with real acceptance criteria, not a marketing promise. Most applications are rejected.
Facing a lien, levy or wage garnishment? This is where professional help earns its money, and where speed matters most.
One more: if the tax bill is a symptom of a wider debt problem, start at our debt relief hub and work out the whole picture first. And if a firm pitches you on settling credit cards as well, note that CuraDebt is the one on this page we have reviewed in depth for that side of things.
Lien, levy or garnishment already in motion?
Once the IRS is actively collecting, the calculus changes. A tax attorney can act faster than a resolution firm and has standing a salesperson does not. The consultation is free and nationwide, and it costs you nothing to find out whether your case warrants one.
Sponsored. We may receive a fee if you request a consultation through this link, at no cost to you.
Frequently asked questions about tax relief companies
What is the best tax relief company in 2026?
By live customer reviews, Precision Tax Relief scores highest at 4.91 out of 5, with 4.92 on the BBB, 4.9 on Google and 4.9 on Trustpilot across 2,504 counted reviews. Fortress Tax Relief follows at 4.85 and Larson Tax Relief at 4.70. If you want high scores backed by a very large sample instead, TaxRise has close to 14,000 counted reviews at 4.38.
How much do tax relief companies charge?
Most quote a flat fee per case, commonly $1,000 to $5,000 and up depending on how much you owe and how complicated the case is. Some price it as 10 to 25 percent of the balance instead. There is no standard price list, which is precisely why you should get two or three quotes and negotiate. Ask what the fee covers, what costs extra, and what happens if the IRS rejects the application.
Are tax relief companies legitimate, or a scam?
Both exist. Legitimate firms employ enrolled agents, CPAs or tax attorneys and are upfront that outcomes depend on IRS criteria. The FTC warns that others charge large upfront fees for relief they cannot deliver. The practical tests: do they promise a specific outcome before reviewing your file, do they pressure you to pay today, and will they put the fee and scope in writing. A firm that fails any of those is one to walk away from.
Can I settle tax debt myself without paying a company?
Often, yes. The IRS publishes installment agreements, Offers in Compromise and currently-not-collectible status, and you can apply directly. The Offer in Compromise application fee is $205, waived for low income applicants. Hiring a firm makes most sense when there is a lien, levy or wage garnishment in play, when you have years of unfiled returns, or when the balance is large enough that a professional negotiating on your behalf changes the outcome.
What is the minimum tax debt for these companies to help?
It varies and it moves. Several firms will not take a case under roughly $10,000, some set the bar at $5,000, and a few have no stated minimum. Below those thresholds you are usually better served by an IRS installment agreement set up directly, because the fee would swallow the benefit.
Does the IRS really accept pennies on the dollar?
Sometimes, through an Offer in Compromise, but it is far rarer than the advertising implies and it is based on a formula, not negotiation skill. The IRS looks at your reasonable collection potential, meaning your assets plus future income against what you owe. If the formula says you could pay in full over time, no firm will get the balance cut, however it is marketed.
Is forgiven tax debt taxable?
Cancelled debt is generally treated as taxable income, with exceptions. That mainly bites on forgiven consumer debt rather than a reduced IRS balance, but it is the kind of detail that turns a win into an unpleasant surprise the following April. Ask any firm to explain the tax consequences of the specific outcome they are proposing.
How long does tax relief take?
Expect months, not weeks. A straightforward installment agreement can be set up quickly. An Offer in Compromise commonly takes six to twelve months to be decided, and longer if the IRS asks for more documentation. Any firm promising resolution in days is selling you the sales call, not the outcome.
How did you rank these tax relief companies?
Each company is scored on its live BBB, Google and Trustpilot customer ratings, with each source carrying equal weight. Any source with fewer than 30 reviews is excluded, which is why Fortress Tax Relief’s 16-review Trustpilot score does not count. Ties are broken by the number of counted reviews. No company on the ranking pays us, and all the underlying figures are published next to each entry.
Should I use a tax relief company or a tax attorney?
A tax attorney makes sense when there is a criminal exposure question, a complex business or payroll tax matter, or litigation. For the common cases, back taxes, liens, levies and payment plans, an enrolled agent at a reputable firm handles the same processes for less. The distinction worth asking about is who will actually work your file, not what the company calls itself.