Note: we are an independent blog. Our content doesn't constitute financial advice. We strive for accuracy, but please always cross-check inflation numbers directly with the BLS. We may receive compensation from some services and products reviewed on this site (learn more).
Select Page
Amine Rahal
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.
Logo of New Era Debt Solutions (credit: neweradebtsolutions.com)
New Era Debt Solutions (https://neweradebtsolutions.com/) is a well-established, legitimate debt settlement company (NOT a credit counselor) that’s been helping people get out of debt since 1999, which makes it one of the oldest debt settlement providers in America. Based in Camarillo, California, they operate nationwide (EXCEPT Maine, Oregon, and Iowa), and specialize in negotiating with creditors to settle unsecured debts, like credit card debt, personal loans and others for less than what you owe.
Check if You Qualify First
Considering debt settlement? New Era offers a free consultation to help you assess whether their program fits your situation. No commitment required.
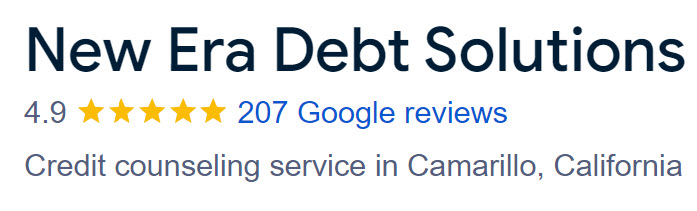
New Era Debt Solutions takes the #1 spot in our debt relief company rankings this year due to their combined score of 4.84/5 stars, at time of press, as you can see below. This objective score takes into account their ratings on multiple third-party review sites, like the BBB, Google Reviews, TrustPilot and others.
New Era Debt Solutions has a good profile on Google reviews
What Services Does New Era Debt Offer?
New Era primarily offers debt settlement services, meaning they work with your creditors to reduce the total amount you owe. This service is specifically for unsecured debt (like credit cards, medical bills, personal loans and certain other types of debt). Their service cannot help for things like mortgages or student loans.
New Era Debt aims to create a plan that helps you become debt-free in as little as 24 to 48 months. One of the standout aspects of New Era is that they don’t charge any upfront fees. You only pay them when they’ve successfully settled your debt and you have agreed with their plan.
New Era Debt vs Others
It’s important to note that New Era Debt Solutions is a debt settlement company, not a credit counseling nonprofit. Therefore, they don’t do Debt Management Plans (DMP’s) and instead they simply negotiate with your creditors to settle for a much lower debt. This means you will take a credit score hit, but much lesser than that of a bankruptcy’s. Their service is similar to companies like CuraDebt, TurboDebt, Accredited Debt Relief and others.
If you’re wondering how New Era Debt compares to other providers who may offer similar (but different) options on how to deal with your debt, see the table below:
Feature / Factor
New Era Debt Solutions
Family Credit Management (FCM)
Bankruptcy (Chapter 7)
Type of Program
Debt Settlement
Debt Management Plan (DMP)
Legal Debt Discharge
Typical Debt Reduction
30–60% of enrolled debt
Interest reduction only
Up to 100% (full discharge)
Upfront Fees
❌ None
✅ Usually $0–50 setup fee
✅ Court & lawyer fees (~$1,500–$2,000)
Ongoing Fees
14%–23% of enrolled debt (only if settled)
$25–$75/month (varies by state)
❌ None after filing
Impact on Credit Score
❌ Negative (missed payments + settlement)
⚠️ Neutral to slightly negative
❌ Severe (stays for 7–10 years)
Time to Completion
24–48 months
36–60 months
~6 months (Chapter 7)
Covered Debts
Unsecured (credit cards, personal loans)
Unsecured (credit cards, medical, etc.)
Most unsecured debts
Creditor Negotiation
✅ Negotiates balance reductions
✅ Negotiates lower interest rates
❌ No negotiation — legal discharge
Eligibility Requirements
Must have financial hardship
Verifiable income + willingness to pay
Must pass a means test
Credit Counseling Required?
❌ No
✅ Yes
✅ Yes (pre-filing requirement)
Legal Protection from Creditors?
❌ No (until settled)
❌ No (voluntary plan)
✅ Yes (automatic stay)
Best For…
Settling large unsecured debts without bankruptcy
Paying debts in full with lower interest
Wiping out debts with no repayment
NOTE: make sure you study all the options above to find the right method to tackle your debt. They all have their pros and cons, depending on your situation.
If you’re comparing debt relief options and want to understand how settlement might apply to your debt, you can use New Era’s free assessment tool to get a clearer picture.
In terms of reputation, New Era Debt Solutions has solid reviews across multiple platforms, as we covered earlier in the “company’s snapshot” section. They hold an A+ rating with the Better Business Bureau (BBB).
On Trustpilot, they’ve received mostly positive reviews, with customers praising them for professionalism and their ability to reduce large amounts of debt. Like any company, there are a few negative reviews, but those are often about the downsides of debt settlement itself (such as its impact on credit scores), rather than the company’s service.
Management Team
New Era’s CEO, Dan Smith, has a strong background in finance and a focus on ethical, transparent practices. The company is committed to not only helping clients get out of debt but also educating them on how to stay out of it in the future. They pride themselves on being a debt settlement company that actually does the work in-house—they do not outsource anything, so you’re always dealing with New Era directly.
Which States Do They Cover?
New Era Debt Solutions serves clients across the United States, except in the states of Maine, Oregon, and Iowa as we covered in the beginning of this article. This may change in the future, so it’s always a good idea to fill out their pre-qualification form to see if your address allows debt settlement and if New Era operates there.
What’s the Process Like?
When you sign up, you’ll first have a consultation to review your financial situation. After that, they’ll create a plan tailored to your debt and begin negotiating with your creditors. You’ll make monthly payments into an escrow account while New Era works to settle your debts for less than what you owe. It’s a fairly straightforward process, but as with any debt settlement plan, it’s important to know that your credit score will take a hit. While under negotiation, there are also risks like collection calls or lawsuits.
Is New Era Debt Solutions Right for You?
New Era Debt Solutions has been around for over 20 years, and their track record, coupled with strong reviews and no upfront fees, makes them a legitimate option if you’re considering debt settlement. They are especially appealing if you’re struggling with large amounts of unsecured debt and need an alternative to bankruptcy. That said, debt settlement isn’t for everyone—make sure to understand the pros and cons before diving in.
If you’re dealing with overwhelming debt due to this high-inflation economic landscape, and are looking for a company that can help you decrease and/or pay off your debt, and has a great reputation, New Era could be the right fit for you. Make sure you take advantage of their free consultation to ask which of their various debt relief options is best for you.
FAQ
Here’s a frequently asked questions (FAQ) section covering the most common questions new users have about New Era Debt Solutions:
1. How much does New Era Debt Solutions charge?
New Era charges between 14% and 23% of the initial enrolled debt amount. There are no upfront fees; they only get paid when they successfully negotiate a debt reduction. This is a contingency-based fee structure.
2. What types of debt does New Era handle?
They handle unsecured debts like credit card debt, personal loans, private student loans, medical bills, and some types of business debts. They do not handle secured debts like mortgages or car loans.
3. Will using New Era affect my credit score?
Yes, debt settlement, regardless of which company you choose to work with, will negatively impact your credit score. Settling a debt means paying less than the full amount owed, which creditors deem a negative event. However, the impact is less damaging than bankruptcy.
4. Is New Era Debt Solutions accredited and reputable?
Yes, New Era has BBB accreditation and has an A+ rating. They have generally positive reviews from clients on platforms like TrustPilot and the BBB website.
5. Where is New Era available?
New Era is accessible in 46 states as well as Washington D.C. and the Virgin Islands. They do NOT operate in Maine, Oregon, and Iowa.They collaborate with the Consumer First Legal Network to offer services in certain states where they may not directly operate.
6. What happens if a creditor refuses to settle?
If a creditor refuses to negotiate, they could potentially take legal action, which might result in lawsuits or wage garnishments. However, most creditors prefer to negotiate rather than pursue costly legal action.
7. How long does the debt settlement process take?
The typical debt settlement program with New Era takes around 28 months. The exact duration depends on the amount of debt, your monthly contributions, and how quickly creditors agree to settlements.
8. Can I cancel my program with New Era Debt Solutions?
Yes, clients can cancel their program with New Era at any time. However, any funds put towards fees or those that are in the dedicated account may be subject to the terms of the cancellation agreement.
Debt relief isn’t one-size-fits-all. If you’re considering settlement, it might be worth seeing if you qualify through a no-pressure consultation with New Era.
Amine Rahal
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.
Lauren Brown
Lauren has over 13 years of experience in wealth management and financial planning. She is a CFA charterholder and holds a Bachelor’s degree in Finance. Lauren has worked with several asset management firms, offering wealth advisory and portfolio management services to high-net-worth clients.
In the U.S., interest rate caps—especially when it comes to protecting consumers from predatory lending—are largely regulated at the state level. This means that the maximum interest rates lenders can charge vary depending on which state you live in and the type of loan we’re taking out. Let’s break down how this works across different states.
What Qualifies as a “Predatory Loan”?
First, let’s compare a traditional loan you would get from a bank versus a “predatory loan” you would get from an alternative lender:
Feature
Traditional Bank Loan
Predatory Loan
Interest Rate
Low to moderate (typically 3% to 12% APR)
Very high (can exceed 50% APR, sometimes 300%+)
Loan Terms
Fixed terms (usually 1 to 30 years)
Short terms (often 2 weeks to a few months)
Repayment Structure
Monthly payments, often with amortization
Lump-sum payment or frequent, high payments
Fees and Charges
Transparent, disclosed upfront
Hidden fees, high fees, or penalties
Borrower Qualification
Strict requirements (credit score, income, etc.)
Minimal qualification (often no credit check at all)
Regulatory Oversight
Highly regulated by federal and state laws
Often operates in regulatory gray areas
Purpose of Loan
Typically for major purchases (homes, cars, education)
Often for emergency or short-term needs
Impact on Credit Score
Positive impact if paid on time, reported to credit bureaus
Negative impact, often not reported positively to credit bureaus
Borrower Rights
Strong consumer protections, recourse available
Limited recourse, predatory practices common
Rollover/Renewal
Generally not allowed or unnecessary
Frequent rollovers, trapping borrowers in cycles
Lender’s Intent
Long-term relationship, repayment is expected
Profit from borrower’s inability to repay on time
Essentially, a predatory loan is a type of loan that takes advantage of borrowers in vulnerable and dire financial situations. These loans often come with excessively high interest rates, hidden fees, or deceptive terms that make it difficult for borrowers to repay the loan.
Federal Protections
Before diving into state specifics, it’s worth noting that there is a federal cap in place for certain groups. The Military Lending Act (MLA) caps interest rates at 36% APR for active-duty service members and their dependents on most consumer loans. This law provides a strong layer of protection, but it only applies to military members. You can learn more about the MLA on the Consumer Financial Protection Bureau (CFPB) website.
State-Level Interest Rate Caps
Interest rate caps for everyone else are set by state laws, and these can vary widely:
California
Payday Loans: In California, payday lenders can charge up to $15 per $100 borrowed, which can equate to an APR of over 400% depending on the term of the loan.
Installment Loans: For loans over $2,500, there’s no cap on interest rates.
Payday Loans: Colorado has one of the stricter caps, limiting payday loan interest rates to 36% APR. This was implemented after voters approved a 2018 ballot measure to curb high-interest payday loans.
All Loans: New York has a strict usury law that caps interest rates at 16% for most types of consumer loans. Charging above 25% is considered criminal usury.
More Info: For more on New York’s laws, the New York State Department of Financial Services is a good resource.
South Dakota
Payday Loans: Like Colorado, South Dakota caps payday loan rates at 36% APR. This cap was set after a successful 2016 ballot initiative aimed at protecting consumers from predatory lending practices.
More Info: Learn more on the South Dakota Division of Banking website.
Texas
Payday Loans: Texas doesn’t cap interest rates directly for payday loans, but it does regulate fees. This can still lead to APRs that exceed 400%, depending on the loan’s terms, which is extremely high.
More Info: The Texas Office of Consumer Credit Commissioner provides more information on lending laws in the state.
Illinois
All Loans: As of 2021, Illinois capped interest rates at 36% APR for all consumer loans, including payday loans, through the Predatory Loan Prevention Act.
All Loans: Utah has no cap on interest rates, making it one of the most lender-friendly states in the U.S. This means payday lenders and other high-interest lenders can charge extremely high rates. Beware of Utah-based lenders.
More Info: For more, see the Utah Department of Financial Institutions.
Know Your Rights & Do Your Due Diligence
These state-specific laws are crucial because they determine how much protection you have against predatory lending practices. In states with strict caps like New York or Colorado, consumers are generally safer from exorbitant interest rates. But in states like Utah or Texas, the lack of caps means consumers need to be extra cautious when taking out loans.
Predatory loans have put many American consumers in dire financial situations, exacerbating their debt and pushing them into bankruptcies. If you are dealing with high debt and are struggling to pay your bills, consider debt settlement instead of requesting another loan which will most likely put you deeper into debt.
Finding Out More
If you’re considering taking out a loan, it’s a good idea to first check what the interest rate caps are in your state. You can usually find this information through your state’s Department of Financial Services or a similar regulatory body. Additionally, theConsumer Financial Protection Bureau (CFPB) offers a wealth of resources on consumer rights and protections.
By understanding these caps, you can better protect yourself from predatory lending practices and make more informed financial decisions.
In the realm of economics, three terms often crop up in discussions about the health of an economy: inflation, recession, and depression. While they are interconnected in various ways, each term represents a distinct economic phenomenon with different implications for the economy and, by extension, for investors, businesses, and consumers. This article will delve into the definitions of inflation, recession, and depression and explore how they are linked. Let’s start by looking at a comparison table:
Inflation
Recession
Depression
Definition
General increase in prices.
Significant decline in economic activity, typically for two quarters or more.
Severe and prolonged downturn in economic activity.
Impact on Economy
Decreases purchasing power. Can stimulate economic activity when moderate, but leads to instability when too high.
Results in higher unemployment, decreased consumer spending, and economic slowdown.
Severe declines in employment and production, often causing significant economic hardship.
Common Causes
Excessive growth in the money supply, demand-pull, or cost-push factors.
Various, including financial crises, economic bubbles, or external shocks.
Often a severe or prolonged recession, but can also be caused by a financial crisis or large-scale economic dislocation.
Central Bank Response
May raise interest rates to slow economic activity and curb inflation.
May lower interest rates and increase government spending to stimulate economic activity.
Similar to recession, but response typically needs to be larger and more sustained. May involve significant fiscal policy responses as well.
Link to Other Two Terms
High inflation can lead to a recession. Recession can lead to low inflation or deflation.
Can turn into depression if severe and prolonged. Lower demand during a recession can lead to lower inflation.
Could lead to deflation due to lower demand. However, policy responses could potentially lead to inflation.
Inflation
Inflation is the rate at which the general level of prices for goods and services is rising, eroding purchasing power. In other words, as inflation increases, each unit of currency buys fewer goods and services. Inflation is updated monthly.
Moderate inflation is typical in a growing economy and can even stimulate economic activity. However, if it gets out of hand, it can lead to economic instability. The BLS uses the CPI to measure inflation.
The Federal Reserve, like most central banks, aims to control inflation by adjusting interest rates. Lower interest rates encourage spending and investment, which can boost economic activity and, potentially, inflation. Higher interest rates can slow economic activity and curb inflation.
Recession
A recession is typically defined as a significant decline in economic activity spread across the economy, lasting more than a few months. This is often seen in real GDP, real income, employment, industrial production, and wholesale-retail sales. Economists generally agree that two consecutive quarters of negative GDP growth indicate a recession.
Recessions can be caused by various factors, including financial crises, external shocks, and the bursting of economic bubbles. Policymakers often respond to recessions by lowering interest rates and increasing government spending, aiming to stimulate economic activity.
Depression
A depression represents a severe and prolonged downturn in economic activity. It’s more extended and more profound than a recession, characterized by significant declines in output, employment, and trade, often lasting several years. The most notable example is the Great Depression of the 1930s.
Depressions are rare, and economists don’t have a standardized definition like they do for a recession. However, they generally agree that depressions involve a substantial contraction in economic activity that lasts several years.
How Are They Linked?
Inflation, recession, and depression are intertwined in many ways:
Inflation and Recession: Too much inflation can lead to a recession. When prices rise too quickly (hyperinflation), consumers can struggle to afford goods and services, and businesses can find it challenging to plan for the future. If the central bank tries to combat high inflation by raising interest rates too quickly, it can cool the economy too much and lead to a recession.
Recession and Inflation: On the flip side, recessions can lead to lower inflation or even deflation (a general decrease in prices). In a recession, demand for goods and services falls, which can lead to lower prices.
Recession and Depression: If a recession is particularly severe and prolonged, it can turn into a depression. While there’s no strict dividing line, depressions involve higher unemployment, lower output, and more significant declines in standards of living than recessions.
Inflation and Depression: Inflation rates during a depression can vary. Sometimes, depressions can involve deflation, as demand for goods and services falls and businesses lower prices to try to entice customers. However, economic policy responses to a depression could lead to inflation. For example, if the government responds by increasing the money supply or government spending dramatically, it could eventually lead to increased inflation.
In summary, inflation, recession, and depression are all interconnected elements of economic cycles. By understanding these terms and their relationships, we can better grasp the complexities of economic health and make
FAQ
Q1: What causes inflation? A1: Inflation can be caused by various factors, including excessive growth in the money supply, demand-pull inflation where demand for goods and services outpaces supply, or cost-push inflation where the cost of raw materials or wages increase.
Q2: How can inflation be controlled? A2: Central banks often aim to control inflation by adjusting interest rates. By raising interest rates, central banks can decrease borrowing and spending, thus reducing inflation. Conversely, lowering interest rates can stimulate borrowing and spending, potentially leading to increased inflation.
Q3: What are the signs of a coming recession? A3: Common signs of a coming recession include a decline in the GDP, higher unemployment rates, lower consumer spending, decrease in business profits, and a volatile stock market.
Q4: How can a recession affect the average person? A4: During a recession, people might face job loss or reduced working hours. They may also see the value of their investments decrease, and it could become harder to get credit.
Q5: What’s the difference between a recession and a depression? A5: The main difference between a recession and a depression is the duration and severity of the economic downturn. A recession is a temporary decline in economic activity, typically lasting six months to a year. A depression, on the other hand, is a severe and prolonged economic downturn, often lasting several years.
Q6: How do governments respond to a depression? A6: In a depression, governments may enact expansive fiscal policies, such as increasing government spending, cutting taxes, or both, to stimulate the economy. Central banks may also adopt expansionary monetary policies, such as lowering interest rates or implementing quantitative easing.
Q7: Can a depression lead to inflation? A7: A depression could potentially lead to deflation due to lower demand. However, the economic policy responses to a depression, such as increasing the money supply or government spending, could eventually lead to increased inflation.
Q8: How does a recession affect inflation? A8: A recession typically leads to lower inflation or even deflation. This is because, in a recession, the demand for goods and services falls, which can lead to lower prices. However, the specific impact on inflation can vary depending on the nature and severity of the recession, and the policy responses to it.
Q9: What role do central banks play in managing the economy through these cycles? A9: Central banks play a crucial role in managing the economy through inflation, recession, and depression. They often use tools like interest rates and open market operations to influence the money supply, aiming to stabilize prices and maintain low unemployment rates.
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.
Amine Rahal
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.