Money Management International: Legit Debt Relief Company? Read Our 2026 Review
Money Management International (www.moneymanagement.org) is a U.S.-based nonprofit 501(c)(3) credit counseling agency offering services such as debt management plans, financial education, and broad support across credit-related challenges. Unlike for-profit debt settlement companies, MMI focuses on helping clients reduce interest rates and manage monthly payments over time with transparency and affordability. While this model suits those aiming to repay debts fully with guidance, consumers should also examine ** Compare every option in our rankings before you commit.
|
Not sure a debt management plan is your best move? Nonprofit counseling like MMI works brilliantly for some situations and not at all for others. Our free quiz compares DMPs, settlement, consolidation and bankruptcy against your actual numbers. Company Snapshot
Legitimacy, Ratings & ReviewsMMI is a highly reputable nonprofit credit counseling organization with multiple accreditations and top marks for transparency and client satisfaction.
Clients often praise MMI’s helpful staff, clear advice, flexible payment structures, and educational support. Services Offered by MMI
Pros 👍
Cons 👎
Debt Types They Can Help WithMMI primarily assists with unsecured debts, including:
They do not cover secured loans, federal student loans, or IRS obligations under standard programs, though they do offer some student loan counseling and specialized foreclosure/bankruptcy counseling. Final ThoughtsMoney Management International stands out as a trusted nonprofit offering affordable, structured debt support. They are a smart starting point if you want to repay your debt in full with lower interest and comprehensive guidance. If, however, you are looking for a settlement option where you pay less than you owe with no upfront fees, then we recommend Comparing your options? We ranked 24 debt relief companies side by side, nonprofits and settlement firms alike, with fees, minimums and ratings for each. Frequently Asked Questions About Money Management International1. Is Money Management International a legitimate company? 2. How does MMI’s debt management program work? 3. How much does it cost to enroll in a debt management plan with MMI? 4. What kinds of debt does MMI help with? 5. Will enrolling with MMI hurt my credit score? 6. How is MMI different from debt settlement companies? 7. Is MMI available nationwide? 8. How long will it take to complete a program with MMI? 9. What do clients say about MMI? 10. Is MMI the best option for debt relief? Money Management International FAQIs Money Management International legit?Very much so. MMI is a 501(c)(3) nonprofit with roughly 60 years of history, membership in the NFCC and FCAA, Council on Accreditation approval, and HUD certification for housing counseling. It is one of the largest nonprofit counseling agencies in the country.
How much does MMI charge?Most counseling and education is free. Debt management plans carry modest setup and monthly fees that vary by state, and MMI notes that reduced or waived fees are available for qualifying clients. You will get exact figures in your free initial session.
Is MMI a debt settlement company?No, and that matters. MMI is a nonprofit credit counselor: on a debt management plan you repay everything you owe at reduced interest rates. Settlement companies negotiate to pay less than you owe, with heavier credit damage and fees. Different tools for different situations.
Will an MMI debt management plan hurt my credit?Far less than settlement. Accounts are typically closed when they enter the plan, which can ding your score at first, but consistent on-time plan payments usually rebuild credit during the 3 to 5 year program.
What if a DMP is not enough for my debt?If your budget cannot cover full repayment even at reduced rates, look at settlement or bankruptcy. Take our free quiz to compare all four paths against your numbers, or browse our rankings of 24 debt relief companies.
Debt Clear USA – Trustworthy Company for Debt Relief? [2026 Review]
Debt Clear USA (www.debtclearusa.com) is a debt settlement company endorsed by Shark Tank’s Robert Herjavec that focuses on helping consumers resolve unsecured debt like credit cards, personal loans, and some medical bills. I’ve reviewed a lot of debt relief companies over the years, and my view here is pretty simple: Debt Clear USA appears to be a legitimate option worth considering, but debt settlement is not automatically the best path just because a company has good reviews. For many people, the smartest first move is to take a step back, compare all major options, and start with a neutral assessment like our debt relief quiz before signing up anywhere. Not sure if Debt Clear USA is right for you?Before you choose any debt relief company, I strongly recommend taking our quick quiz. It helps you compare whether debt settlement, consolidation, a debt management plan, or even bankruptcy may fit your situation better. Quick VerdictIf you already know you want debt settlement and you have at least around $10,000 in unsecured debt, Debt Clear USA looks like a reasonable company to put on your shortlist. It appears to operate as a direct settlement provider rather than just a lead-gen brand, and that matters. Still, I would not make a decision based on branding, celebrity endorsement, or review volume alone. I would compare it against other settlement companies like Accredited Debt Relief, New Era Debt Solutions, Freedom Debt Relief, National Debt Relief, Americor, and CuraDebt before moving forward. What Debt Clear USA Actually DoesDebt Clear USA mainly offers debt settlement, sometimes called debt negotiation. In plain English, that means the company tries to negotiate with your creditors so you can settle enrolled debts for less than the full balance owed. This usually applies to unsecured debts, not secured debts like mortgages or car loans. That can sound attractive, especially if your balances have snowballed and minimum payments no longer make a dent. But I always like to remind readers that debt settlement is not a magic reset button. It can damage your credit, creditors can still keep collecting while negotiations are happening, and forgiven debt may create tax issues in some cases. That is why I usually tell people to compare settlement against other solutions first, including the broader companies listed on our best debt settlement companies page and even specialist resources like our debt consolidation lawyers guide when their situation is messier than average. Debt Clear USA vs. simply choosing “any” debt settlement company
Company Snapshot Robert Herjavec from ABC’s Shark Tank is associated with the brand’s marketing and visibility.
Is Debt Clear USA legitimate?From what I can see, Debt Clear USA appears to be a legitimate debt settlement company rather than a fake or fly-by-night operation. The company has a visible public presence, strong customer-review visibility, and it presents itself as aligned with standard industry practices like charging after settlements rather than before. That said, I always tell readers that “legit” is only the first filter. A legitimate settlement company can still be the wrong choice for your case if your debt is manageable through a lower-risk option. This is where many consumers get tripped up. They search for the “best” company when the better question is, “Should I even be doing settlement at all?” If your credit is still decent, if you can still make payments, or if a lower-interest repayment path is available, settlement may be too aggressive. I’d compare Debt Clear USA against general alternatives like debt management, consolidation, and state-specific relief pages such as North Carolina debt relief, Florida debt relief, and Illinois debt solutions if you want more context around what other residents are considering. Ratings and review profileOne thing Debt Clear USA clearly has going for it is social proof. It has a strong public review footprint, and that matters because some smaller debt relief brands barely leave a trace online. Still, I never treat review averages as the whole story. In this space, you want to read for patterns: did clients say the process was explained clearly, were fees disclosed properly, did people feel informed, and were expectations realistic? That tells me more than a star average by itself. I would also pay close attention to how a company explains the unpleasant parts of debt settlement. If a rep makes it sound painless, instant, or guaranteed, that is a red flag. Good companies should be upfront that missed payments, credit-score damage, collections pressure, and legal risk can all be part of the process. That is not unique to Debt Clear USA. It is part of the settlement model itself. Want help choosing between settlement, consolidation, or bankruptcy?That decision matters more than the company name. Use our quiz to narrow down the path that actually fits your debt level, income, and urgency. Services offered by Debt Clear USA
What they do not seem to emphasize is a wide menu of alternatives. That is normal for a specialist. But as a consumer, it means you should bring your own comparison mindset. For example, if what you really need is a structured repayment plan instead of settlement, a company like Debt Clear USA may not be the best fit. I’d look at broader comparison resources too, including our reviews of JG Wentworth Debt Relief and TurboDebt. Who Debt Clear USA may be a good fit for
Who should probably look elsewhere first
👍 Debt Clear USA Pros
👎 Debt Clear USA Cons
What types of debt can they help with?Debt Clear USA mainly focuses on unsecured debt. That usually means:
If your issue is more specialized, you may want to read beyond general settlement reviews. For example, tax debt is a very different animal, which is why pages like Tax Relief Advocates and what a tax debt attorney does can be more relevant than a standard debt settlement review. Important things many reviews don’t explain clearly enoughThis is the section I think matters most. First, debt settlement usually means missed payments. That is how leverage gets created. Creditors are more likely to negotiate after accounts become seriously delinquent. This can lead to collections calls, credit-score damage, and extra stress along the way. Second, there is no guarantee every creditor will play nice. A settlement company can negotiate, but it cannot force every creditor to accept a reduced payoff. In some cases, a creditor may escalate collection efforts or sue. Third, forgiven debt can sometimes create a tax issue. In general, canceled debt may be treated as taxable income unless an exception applies. That does not mean everyone gets hit with a surprise tax bill, but it is something you should ask about before enrolling. Fourth, cheaper alternatives sometimes exist. I’ve seen many consumers jump straight to settlement because ads make it sound like the default solution. It isn’t. Sometimes the better answer is consolidation, counseling, a workout with creditors, or simply choosing a different company and strategy after comparing several options carefully. Best next step before signing up with any debt relief companyTake our debt relief quiz first. It is the fastest way to pressure-test whether settlement really makes sense for you, or whether a different path may save you money, stress, and credit damage. My overall opinionDebt Clear USA looks like a real company with enough public credibility to deserve consideration. I would not dismiss it. But I also would not treat it as an automatic yes. In this niche, the bigger question is not “Is this company legit?” but “Is debt settlement the right move for me at all?” If you are already behind, overwhelmed, and realistic about the tradeoffs, Debt Clear USA could be worth a consultation. If you still have decent credit or a realistic chance to repay what you owe under better terms, I’d explore other paths first. That is exactly why I recommend taking the quiz before choosing any provider. FAQ About Debt Clear USAIs Debt Clear USA a scam?From everything I could reasonably review, it does not appear to be a scam. It appears to be a real debt settlement company with a public footprint and meaningful review activity. That said, “not a scam” does not automatically mean it is the best option for your financial situation. How much debt do you usually need for Debt Clear USA?Many settlement companies work best when you have a fairly large amount of unsecured debt, often around $10,000 or more. If your debt is lower than that, the math may not work as well, and another solution could be more practical. Will Debt Clear USA hurt my credit?Debt settlement itself is not a credit-building strategy. In most cases, consumers enter settlement after they stop making regular payments, and that can seriously hurt credit in the short to medium term. This is one of the main tradeoffs you need to understand before enrolling. Can creditors still sue while you are in a debt settlement program?Yes. A settlement company can negotiate, but it cannot stop a creditor from taking legal action. Some creditors settle, some wait, and some may decide to escalate. That is one of the most important risks consumers should understand upfront. Are debt settlement fees charged upfront?Reputable settlement companies should not charge upfront fees before a debt is successfully settled. If a company seems evasive on this point, I would be cautious. Can settled debt become taxable?Sometimes, yes. In general, canceled debt may be taxable unless an exception applies, such as certain insolvency or bankruptcy situations. This is something I would specifically ask about before enrolling in any settlement program. What should I do before choosing Debt Clear USA?Compare the company against at least a few other serious options, review total expected fees, ask how long programs typically take, ask how lawsuits are handled, and make sure you compare settlement with alternatives like consolidation or counseling. I’d start with our debt relief quiz before making any commitment. Other helpful resources on our site: Debt relief hub, best debt settlement companies, best companies, New Era Debt Solutions review, CreditAssociates review, Pacific Debt Relief review, ClearOne Advantage review, and Family Credit Management review. Symple Lending Review (2026): Is It Legit, and Is It Even Debt Relief?
Symple Lending is not a debt relief company. That is the single most important thing to understand before you read another word, because a large share of the people searching its name think it is one. Symple Lending is a loan broker. It matches you with a personal or consolidation loan from a panel of partner lenders, and that loan is new debt used to pay off your old debt. For the right borrower that is a genuinely good trade. Swapping several credit cards at 26 percent for one fixed loan at 12 percent saves real money and simplifies your life. For the wrong borrower it is the worst thing you can do, because you clear your cards, keep the cards, and end up owing twice. Which of those you are comes down to your credit score and your spending discipline, and I will help you work that out below. Not sure whether a consolidation loan is the right move for you? Our two minute quiz compares consolidation, settlement, nonprofit counseling and bankruptcy against your actual numbers, with nothing to buy at the end. Find Your Best Debt Relief Option Already know you want a consolidation loan and want to see your rate? Symple Lending runs a soft credit check that does not affect your score. Symple Lending at a glance
Is Symple Lending legit?Yes. Symple Lending, LLC is a licensed lender under the Utah Department of Financial Institutions with NMLS ID 2508833, it is BBB accredited with an A+ rating, and it has close to 11,000 public reviews averaging 4.84 on a volume-weighted basis. For a company founded in 2022 that is an unusually clean record, and the complaint count backs it up.
The number that impressed me most is the complaint count: 46 BBB complaints in three years, 16 closed in the last twelve months. To put that in perspective, I have spent this month going through the files of tax and debt firms carrying 598 and 786 complaints over the same period. Symple Lending is operating at a fraction of that rate. Whatever else you conclude, the operational side of this business is not generating widespread anger. Two honest caveats on those reviews. First, a Trustpilot profile that is 95 percent five-star and only three years old is usually a company actively soliciting reviews at the point of funding, which is the happiest moment in the customer relationship. That is not misconduct, it is just selection: you are reading people who got approved. Second, brokers structurally attract fewer complaints than the lenders behind them, because the part that can go wrong later, servicing the loan, is somebody else’s job. Who is actually lending you the moneyThis is the part almost no other review covers, and it matters. Symple Lending does not fund your loan. It routes your application to a panel of partners, and the ones named in its own disclosures are:
Follow that first name and it gets interesting. Achieve is the company formerly known as Freedom Financial Network, founded in 2002 by Andrew Housser and Brad Stroh, which rebranded in September 2022. It is the same corporate family as Freedom Debt Relief, the debt settlement company we review separately. None of that is hidden and none of it is improper. But it is worth knowing that if you go to Symple Lending for a consolidation loan and to Freedom Debt Relief for settlement, you may end up dealing with the same corporate group through two very different doors. Ask which lender your offer is coming from before you accept it, and look that lender up on its own merits. What Symple Lending costsThe advertised range is 6.99 percent to 35.99 percent APR, fixed, on loans of 5,000 to 100,000 dollars over 24 to 84 months. That is a very wide spread and where you land in it is the whole ballgame. Here is the arithmetic that actually decides whether this is worth doing. Take a 20,000 dollar balance across cards averaging 24 percent APR:
Figures are illustrative and rounded, but the shape is the point. A consolidation loan only helps if the rate you are offered is meaningfully below what you are already paying. If your credit is bruised enough that the offer comes back near 30 percent, consolidation is not solving your problem, it is renaming it. Our walkthrough on paying off 20,000 dollars in credit card debt runs the full comparison. Consolidation loan vs debt settlement vs nonprofit planThese three get confused constantly and they are not interchangeable. The right one depends almost entirely on whether you can still qualify for credit.
The dividing line is simple. If a lender will still give you a good rate, consolidate. If no lender will, that is the market telling you the problem is bigger than your interest rate. At that point look at our ranking of debt relief companies or the wider debt relief guide instead. Pros and cons👍 What Symple Lending gets right
👎 Where Symple Lending falls short
Not sure whether you would even qualify at a rate worth taking? The quiz uses what you owe, what you earn and how far behind you are to tell you whether consolidation, settlement, a nonprofit plan or bankruptcy is the realistic route. Two minutes, no signup. Take the 2-minute debt relief quiz Credit still in decent shape? Check your Symple Lending rate with a soft pull that will not affect your score. Who should use Symple Lending, and who should notWorth applying if: your credit score is roughly 640 or better, your income is steady and documentable, your cards are charging you 20 percent or more, your total unsecured debt sits between 5,000 and 100,000 dollars, and you are current on your payments. That borrower gets a genuinely lower rate and a fixed end date, and both of those are worth having. Do not apply if: you are already behind, your score is below about 600, your debt-to-income ratio is above roughly 50 percent, or you honestly cannot promise yourself the cards will stay unused afterwards. I have been writing about consumer debt for over twenty years and the single most common story in my inbox is the person who consolidated, felt relief, and had the cards full again inside eighteen months. The loan did not cause that, but it did fund it. One practical safeguard: close or freeze the cards the same week the loan funds. Not later, that week. If you cannot bring yourself to do it, you are not ready to consolidate. What to check before you accept an offer
Rate shopping is also safer than most people think. Multiple loan enquiries inside a short window are generally treated as one event for scoring purposes, so getting three quotes costs you almost nothing. If high rates are what put you in this position, our piece on interest rate caps and predatory lending explains what protections actually exist, and the CFPB’s explainer on consolidating credit card debt is a five minute read worth doing first. How Symple compares to similar lendersSymple is not the only company running this model. If you are shopping around, three others I have reviewed use a near identical structure, and the differences show up in the paperwork rather than the pitch.
Final thoughtsSymple Lending is a legitimate, properly licensed loan broker with the cleanest complaint record of any company I have looked at this month. If you have decent credit and expensive cards, it is a reasonable place to shop for a consolidation loan, and the soft credit pull means looking costs you nothing. What it is not is debt relief. Nobody is going to reduce what you owe here. You will owe exactly the same principal to a different lender at, hopefully, a better rate. That is a refinancing decision, not a rescue, and the people who get burned are the ones who arrived looking for a rescue and were offered a refinance instead. So be honest with yourself about which one you actually need. If the answer is the second one, this is a good option. If it is the first, close this page and look at settlement or a nonprofit plan, because a loan will make things worse. For a comparable broker-style option, our Simple Path Financial review covers a firm with a very similar model. Frequently asked questions about Symple LendingIs Symple Lending legit?Yes. Symple Lending, LLC is a licensed lender under the Utah Department of Financial Institutions with NMLS ID 2508833, founded in 2022 and operating from Irvine, California. It is BBB accredited with an A+ rating and holds roughly 11,000 public reviews averaging 4.84 volume-weighted: 4.9 on Trustpilot from 9,707 reviews, 4.5 on Google from 962, and 4.08 on BBB from 333. Its complaint record is notably clean at 46 BBB complaints in three years. Is Symple Lending a debt relief company?No, and this is the most common misunderstanding about it. Symple Lending is a loan broker. It matches you with a personal or consolidation loan from partner lenders, which is new debt used to pay off your existing debt. Nobody reduces what you owe. Debt relief companies negotiate your balances down; Symple Lending refinances them. They are different products for different situations. Does Symple Lending actually lend the money?No. Symple Lending brokers your application to partner lenders. Its own disclosures name Achieve Personal Loans (NMLS #227977), Achieve Loans for HELOCs (NMLS #1810501) and ML Enterprise Inc. trading as Engine by MoneyLion (NMLS #1475872). Ask which lender your specific offer comes from, because that is the company that will hold and service your loan. What credit score do you need for Symple Lending?Symple Lending does not publish a minimum. Based on how the partner lenders price, a score around 640 is roughly where meaningful offers begin, and the advertised 6.99 percent floor goes to much stronger profiles. Below about 600 you are likely to be declined or offered a rate high enough that consolidating makes no financial sense. What are Symple Lending’s rates and loan amounts?Fixed APRs from 6.99 percent to 35.99 percent on loans of 5,000 to 100,000 dollars, with terms from 24 to 84 months depending on the product. That is a very wide range. The only rate that matters is the one you are actually offered, and it needs to be meaningfully below your current card APR for the loan to be worth taking. Does checking my rate with Symple Lending hurt my credit?No. Seeing your offers uses a soft credit pull, which has no effect on your score. A hard inquiry happens only if you proceed with a formal application, and that causes a small temporary dip. Rate shopping across several lenders within a short window is generally treated as a single inquiry for scoring purposes. Does Symple Lending charge an origination fee?No origination fee is published on its site. Consolidation loans in this market commonly carry one, typically deducted from your loan proceeds so you receive less than the face amount. Ask for the fee in dollars and confirm whether it comes out of your funds before you accept any offer. How fast does Symple Lending fund a loan?The company states funding in as little as 24 to 48 hours after approval. Actual speed depends on the partner lender, how quickly you return documents, and whether funds go to you or directly to your creditors. Direct payment to creditors is slower but removes the temptation to spend the money on something else. Is Symple Lending connected to Freedom Debt Relief?Indirectly, through a shared lending partner. Symple Lending routes loans to Achieve Personal Loans. Achieve is the company formerly known as Freedom Financial Network, founded in 2002 by Andrew Housser and Brad Stroh and rebranded in September 2022, and it is the same corporate family as Freedom Debt Relief. Symple Lending and Freedom Debt Relief are separate businesses offering different products, but you may end up dealing with the same corporate group through either door. Will a Symple Lending loan hurt my credit score?Short term there is a small dip from the hard inquiry and from opening a new account. Medium term most borrowers improve, because paying off revolving card balances sharply lowers your credit utilisation ratio, which is a major scoring factor. The risk is behavioural rather than mechanical: if you run the cards back up after clearing them, your score and your finances both end up worse. Should I consolidate or settle my debt?Consolidate if a lender will still offer you a rate meaningfully below what your cards charge, which generally means you are current on payments and your credit is intact. Settle if you are already behind and cannot realistically repay the full balance, accepting that settlement damages your credit for years. If no lender will approve you at a sensible rate, that is the market telling you the problem is larger than your interest rate. What states does Symple Lending operate in?Symple Lending does not publish a state exclusion list, and availability ultimately depends on which partner lender picks up your application, since each holds its own state licences. Confirm availability for your state during the application, and check that the lender making the offer is licensed where you live. Can I pay off a Symple Lending loan early?Yes. The company states there is no prepayment penalty, so paying ahead of schedule reduces your total interest. Confirm this in your specific loan agreement, because the term comes from the partner lender rather than from Symple Lending itself. Why does Symple Lending have so few complaints?46 BBB complaints in three years against nearly 11,000 public reviews is a genuinely low rate, and part of that reflects a company running a tidy operation. Part of it is structural, though: brokers attract fewer complaints than lenders, because the things that go wrong later, servicing, payment posting and collections, are handled by the partner lender rather than the broker. Simple Path Financial Review (2026): Costs, Loans and Comparison
Simple Path Financial (www.simplepathfinancial.com) is a California-based debt settlement company offering personal loans, debt consolidation, and other financial solutions to help consumers manage or eliminate unsecured debt. Founded in 2016 and headquartered in Irvine, California, the company has become a well-known name in the debt relief space, though it operates more as a lender and intermediary than a traditional debt settlement provider. Below is our full review and comparison with New Era Debt Solutions. Not sure whether a consolidation loan or debt settlement fits your situation? Our two minute quiz compares settlement, consolidation, nonprofit counseling and bankruptcy against your actual numbers, with nothing to buy at the end. Find Your Best Debt Relief Option Already sure you want your balances reduced rather than refinanced? New Era Debt Solutions charges no upfront fees.
Comparison Table (Simple Path Financial vs New Era Debt Solutions)
Company Snapshot
Who’s Behind It: Key Founders and LeadershipBased on public records, company profiles (e.g., LinkedIn, RocketReach, Forbes), and executive listings, here’s the core team. The company is led by co-founders with deep roots in debt resolution and financial services:
Additional Founding Details: Bradley W. Smith is the driving force, leveraging his Wall Street and debt relief expertise. No major funding rounds disclosed (private company, estimated annual revenue <$1M per SignalHire). The team emphasizes ethical practices, with no loans issued directly, only brokered matches. Simple Path is not the only broker working this way. Our Symple Lending review covers a very similar model, including which lenders actually fund the loans and what the real APR range looks like. Legitimacy, Ratings & Reviews
Simple Path Financial is a legitimate company that offers personal loans and debt consolidation solutions through its own lending services and partner network. Many customers praise its easy online process and helpful representatives, though others note that the rates can be high depending on credit score. It’s best suited for borrowers with stable income and fair to good credit who want to simplify their payments. Check If You Qualify with New Era Debt SolutionsIf you don’t qualify for a new loan or simply don’t want to borrow again, you can still get out of debt faster through negotiation. New Era Debt Solutions helps clients reduce what they owe without taking on new credit obligations. Simple Path Financial Pros 👍
Simple Path Financial Cons 👎
Debt Types They Help With
Check If You Qualify with New Era Debt SolutionsDebt settlement could be a better fit if you can’t qualify for a consolidation loan. New Era helps clients reduce debt balances directly with creditors, no borrowing required and no upfront fees. Other companies in the same laneSimple Path sits in a crowded segment, and the companies around it are easy to confuse. Two more I have gone through line by line: iMerge Financial, which has the best public star ratings of any firm I have checked recently but no licence number I could confirm, and Liberty First Lending, whose consent form is the most revealing document in the whole category. FAQ About Simple Path Financial1. Is Simple Path Financial legit or a scam? Yes, Simple Path Financial is a legitimate company headquartered in Irvine, California. It is accredited by the Better Business Bureau (BBB) with an A+ rating and thousands of positive client reviews. The company has been in business since 2016 and works with verified lending partners to provide loans and financial products. However, as with any loan service, customers should carefully review all terms, interest rates, and repayment schedules before signing. 2. Does Simple Path Financial affect your credit? Yes, applying for a loan can affect your credit in two ways:
If you take out a loan and make consistent, on-time payments, your credit score may improve over time. 3. What types of loans does Simple Path Financial offer? Simple Path Financial provides unsecured personal loans and debt consolidation loans. These can be used for:
They also partner with third-party lenders to expand loan options for borrowers across different credit ranges. 4. What are Simple Path Financial’s loan terms? Loan amounts typically range from $5,000 to $100,000, depending on credit profile and income. Terms usually span from 24 to 84 months (2 to 7 years), with fixed monthly payments. APRs vary between approximately 7.99% and 35.99%, depending on creditworthiness. 5. Does Simple Path Financial charge any fees? Some loans may include an origination fee, generally between 1% and 5% of the loan amount. There are no application fees or prepayment penalties, so borrowers can pay off their loans early without extra cost. Always check your loan disclosure documents before signing to confirm exact terms and fees. 6. How fast can I receive my loan funds? Once approved, many borrowers receive their funds within 1 to 3 business days. Simple Path offers electronic disbursement directly into your checking account. Processing time can vary based on verification of documents and bank details. 7. What credit score do you need to qualify? Most successful applicants have a credit score of at least 600 or higher. However, Simple Path partners with lenders who may approve loans for borrowers with fair credit, provided there’s sufficient income and a stable debt-to-income ratio. 8. Can you be denied a loan after pre-approval? Yes. Pre-qualification is not a guarantee of funding, it simply means you meet the preliminary criteria. Lenders may still decline your application after reviewing your credit report, income verification, or debt obligations. 9. What happens if you miss a payment? Missing payments can result in late fees, a drop in your credit score, and potential collection activity if the account remains delinquent. Borrowers facing financial hardship should contact Simple Path’s customer service immediately to explore payment deferral or restructuring options. 10. Is Simple Path Financial the same as a debt relief company? No. Simple Path Financial provides loans and does not negotiate or settle debts with creditors. Debt relief or debt settlement companies, like New Era Debt Solutions, work to reduce the total amount owed without requiring new loans. 11. Can I apply for a loan if I have bad credit? Yes, borrowers with less-than-perfect credit can apply, but they may be offered higher interest rates or smaller loan amounts. Simple Path’s lending partners evaluate multiple factors including income, employment, and debt-to-income ratio. 12. Is my information secure when I apply? Yes. Simple Path Financial uses industry-standard encryption and data protection measures to secure personal and financial information. Always ensure you’re applying via their official website to avoid phishing or impersonation scams. 13. How do I contact Simple Path Financial? 14. How does Simple Path compare to New Era Debt Solutions? 15. Can you combine Simple Path and New Era services? Liberty First Lending Review (2026): The 14 Companies On Their Consent Form Every few months a mailer lands on my desk from a company I have never heard of, telling me I am pre-qualified for a debt consolidation loan. I keep them, because they are a useful window into how this industry actually works. Liberty First Lending sends a lot of them. What I want to show you is not whether the company is a scam, because it is not, but what actually happens when you call the number on that letter. Before you call the number on that letter
Check What Actually Fits Your Situation Already decided? Accredited Debt Relief and Beyond Finance quote free. The short version
The fourteen companies on the consent formThis is the most useful fact in this review, and it is not on the mailer. Liberty First Lending’s application page discloses the parties your information goes to when you submit it. There are fourteen, and they are named: Americor Funding, Credit9, Monevo, Prosper, BestEgg, Upstart, Marcus by Goldman Sachs, Axos Bank, Figure, Even, debt.org, In-Charge, ratespecial.com and Advantage Law. Read that list again. Prosper, BestEgg, Upstart, Marcus and Axos are lenders, which is what you would expect from a loan application. But Americor and Credit9 are debt settlement and debt consolidation operations, and Advantage Law is a law firm. Those are different products with very different consequences for your credit. So when the complaint file fills with people saying they called about a loan and got pitched something else, the explanation is sitting on the company’s own form. This is not a rogue salesperson. It is the design. One BBB complainant put it more plainly than I could: they called the number on the Liberty First mailer and reported that the phone was answered by a company called Credit Nine. We could not verify common ownership between Liberty First, Americor and Credit9. All three sit at different Irvine addresses and none lists the others as a related business at BBB. What is verified is the referral relationship, because Liberty First discloses it itself. Our review of Americor covers where that path leads if you end up on it. 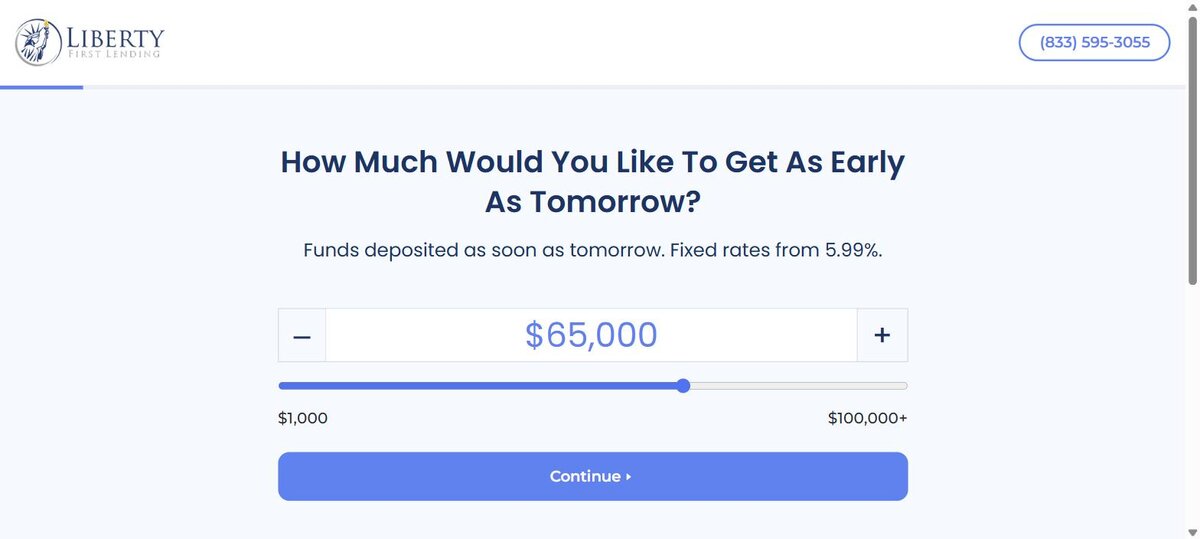 What it says it charges
Two things to notice. The company runs two marketing sites publishing different maximum loan amounts, $45,000 on one and $75,000 on the other, while the application form offers $100,000 or more as a selectable option. That is a transparency problem, not a rounding error. And that 4.9% origination fee is financed into the loan rather than deducted, which means you pay interest on the fee for the life of the term. On a $30,000 consolidation that is roughly $1,470 rolled into the balance and accruing. The site also concedes that lower interest rate loans and loan amounts above $35,000 may be brokered, alongside the flat statement that not all loans will be made through Liberty and loans may be brokered based on state. The reviews are real. So is the complaint file. Both matter.A 4.15 rating across 248 BBB reviews is not nothing, and I am not going to pretend otherwise. Plenty of people had a straightforward experience and said so. But look at what the complaints are about. They are almost entirely from people who were never customers. That is unusual, and it is the signature of a lead generation operation rather than a lending one. Theme one: the volume of contact
Theme two: the letter promises a loan, the call is something else
Theme three: where did they get my details
About those Google reviewsWorth knowing where the positive volume comes from. Liberty First’s Google review base was built through Birdeye, a paid review solicitation platform, which publishes the account as a marketing case study: zero Google reviews before adopting the platform, 272 at five stars afterwards. Solicited reviews are legal and extremely common. But a five star average generated by a vendor whose entire job is generating five star averages is not the same evidence as an organic rating, and it should not be weighed the same way. This is why I lean on complaint counts and regulator records rather than star averages, and why the older third party articles quoting a B plus BBB grade and 3.1 stars are simply out of date. The live figure is A plus and 4.15. Pros and cons
What that mailer actually meansHere is the thing I most want you to take away, and it applies to every letter of this kind, not just this one. Pre-qualified is a marketing term with no legal weight. It typically means a list broker ran a soft screen against credit bureau data and your profile matched. It is not an offer, no underwriter has looked at your file, and the rate on the letter is the best case rate for the strongest applicant, not a rate you have been given. The headline 5.99% here is the floor of a range that tops out at 29.99%. The second thing is that responding costs you something even if you walk away. Your details enter a distribution network. The complaint file for this company is the clearest possible illustration: the loudest and most repeated grievance is not about loan terms, it is about the phone not stopping afterwards. If you want to stop this class of mail at source, you can opt out of pre-screened credit offers for five years or permanently at OptOutPrescreen.com, the official site run by the consumer credit reporting industry. The Federal Trade Commission explains how prescreening works in its guide to prescreened offers. That single step will cut the volume more than any amount of asking to be removed from individual lists. Skip the phone tree Want the comparison without the calls? The quiz runs the same triage a good adviser would, across settlement, consolidation, nonprofit counselling and bankruptcy, using your real numbers. See Which Route Fits Your Numbers Ready to speak to someone? Accredited Debt Relief and Beyond Finance both quote free. Who this suits, and what I would do insteadLiberty First may genuinely help if you have good credit, want to compare several lenders quickly, and are relaxed about being contacted. Its partner network includes real lenders and a broker can save you filling in five applications. But you can reach the same lenders directly. Prosper, Upstart, BestEgg, Marcus and Axos all take applications on their own sites, and going direct means one company holds your details rather than fourteen. If the honest situation is that a consolidation loan will not solve it, because the balances are too large relative to income or your credit will not carry a decent rate, then the loan route is a detour. Our account of clearing over 100,000 dollars in card debt walks through what actually worked, and our CreditAssociates review covers a settlement provider with a longer track record than anything on this page. If the problem is interest rather than principal, a nonprofit debt management plan is almost always cheaper than a consolidation loan carrying a 4.9% origination fee. Money Management International is the nonprofit agency we have reviewed most closely. And if you are being sued or garnished, that is a lawyer question rather than a loan question, which our guide to debt consolidation attorneys covers. Frequently Asked QuestionsIs Liberty First Lending legit?Yes, it is a real registered company. Liberty First Lending, LLC operates from 18500 Von Karman Avenue, Suite 550, Irvine, California, started in February 2023, and has been BBB accredited since June 2023 with an A+ rating and 4.15 stars from 248 reviews. We found no regulatory action and zero CFPB complaints under its legal name. The important caveat is what it is: by its own description it provides lead referral services alongside loan brokerage, so submitting an application shares your details with fourteen named companies. Is Liberty First Lending a direct lender?Not reliably. Its own site states that not all loans will be made through Liberty and that loans may be brokered based on state, and it lists lead referral services among its offerings. It also concedes that lower rate loans and amounts above 35,000 dollars may be brokered. Treat it as a broker and lead generator that sometimes lends, rather than as a lender. Who does Liberty First Lending share my information with?Fourteen companies, named on its own application form: Americor Funding, Credit9, Monevo, Prosper, BestEgg, Upstart, Marcus by Goldman Sachs, Axos Bank, Figure, Even, debt.org, In-Charge, ratespecial.com and Advantage Law. Most are lenders. Americor and Credit9 are debt settlement and debt consolidation operations, and Advantage Law is a law firm, which is why some applicants are pitched a debt program rather than the loan they asked about. Is Liberty First Lending connected to Americor or Credit9?There is a confirmed referral relationship, because Liberty First names both on its own data sharing consent. We could not confirm common ownership. The three companies sit at different Irvine addresses, and none lists the others as a related business on BBB. One BBB complainant reported calling the number on a Liberty First mailer and having the phone answered by Credit Nine. Some third party articles assert an ownership link; we found no corporate record confirming it. What does Liberty First Lending charge?Its published range is 5.99% to 29.99% APR with a 4.9% origination fee financed into the loan, on terms up to 60 months. Because the fee is financed rather than deducted, you pay interest on it for the whole term. Loan amounts are stated as 2,500 to 45,000 dollars on one company site and 2,500 to 75,000 dollars on the other, and no minimum credit score is published. Does Liberty First Lending have an NMLS number?We could not find one. Neither of its marketing sites, its terms of use, nor its application form publishes an NMLS identifier. The only licensing claim it makes is Utah Registered Consumer Lender. A Utah consumer credit notification is a filing requirement rather than a substantive lending licence, so it is weaker evidence than an NMLS registration would be. Why won’t Liberty First Lending stop calling me?Sustained unsolicited contact is the single largest theme in its complaint file. One BBB complainant documented 112 calls and texts in under two months; others describe messages from rotating numbers and area codes. If you responded to a mailer or submitted the form, your details went to fourteen parties, so some of the contact may not be from Liberty at all. Send a written opt out, and cut the source by opting out of prescreened credit offers at OptOutPrescreen.com. Does responding to a pre-qualified mailer hurt my credit?The initial check is usually a soft pull that does not affect your score. A hard inquiry is run before funding, and that does show. The larger risk is not the score, it is that your information enters a distribution network, which is what generates the call volume people complain about. What is the catch with a 5.99% advertised rate?It is the floor of a range that reaches 29.99%, reserved for the strongest applicants, and the mailer does not commit anyone to it. Pre-qualified has no legal weight. It generally means a list broker matched your credit profile against a screen, not that an underwriter has reviewed your file or that any offer exists. What are better alternatives to Liberty First Lending?If your credit is decent, apply directly to the lenders in its own partner list, such as Prosper, Upstart, BestEgg, Marcus or Axos, so one company holds your data instead of fourteen. If a loan will not fix the problem, compare debt relief providers with longer track records. If the issue is the interest rate rather than the balance, a nonprofit debt management plan usually costs less than a consolidation loan carrying a 4.9% origination fee. Sources
Ratings, complaint counts and published rates were checked on 19 August 2026 and change over time. Confirm current figures before acting on them. Optima Tax Relief Review (2026): Fees, 786 Complaints and Is It Worth It?
Optima Tax Relief is the most heavily advertised tax resolution firm in America, and it is the one readers ask me about more than any other. Founded in 2011 and based at 6 Hutton Centre Drive in Santa Ana, California, it represents people who owe the IRS: installment agreements, Offers in Compromise, penalty abatement, wage garnishment and levy releases, unfiled returns and audit defense. It is BBB accredited with an A+ rating and holds close to 13,000 public reviews averaging 4.30 on a volume-weighted basis. It also carries 786 BBB complaints in three years, one of the highest counts in the category. Both of those are real, and the honest version of this review is about what explains the gap. Not sure whether a tax firm is what you need at all? Our two minute quiz compares settlement, consolidation, nonprofit counseling and bankruptcy against your actual numbers, with nothing to buy at the end. Find Your Best Debt Relief Option Certain your problem is IRS debt and want a consultation? Optima Tax Relief works in all 50 states and the first call is free. Optima Tax Relief at a glance
Is Optima Tax Relief legit?Yes. Optima Tax Relief is a real, long-established firm with a physical office, BBB accreditation, an A+ rating and nearly fifteen years of trading history. The question worth asking is not whether it exists but whether the outcome justifies the fee, and the public record is genuinely split on that.
The complaint number you should actually weigh786 BBB complaints in three years, with 219 closed in the last twelve months. That is the highest three-year count of any firm I have examined in this category, and it is roughly 30 percent above the next closest. Volume alone does not condemn a company, because Optima advertises harder and serves more clients than almost anyone else, so a bigger denominator produces a bigger numerator. But it is a large number by any reading and you should not skip past it. Reading through them, the pattern that recurs is not fraud. It is expectation. The most common story is a client who paid several thousand dollars and received an installment agreement, which is a legitimate resolution but also one the IRS grants routinely and which many people could have arranged themselves online for a setup fee of well under 200 dollars. The complaint is rarely “they did nothing”. It is “they did something I did not need to pay for”. There is also an ongoing class action alleging misconduct, negligence and consumer law violations, which Optima denies. I have not seen a judgment and I am not going to characterise unproven allegations as fact. If it matters to your decision, look up the current docket status yourself before you sign anything. What Optima Tax Relief costsOptima uses the standard two-phase model, and its entry price is meaningfully lower than most competitors:
The low investigation fee is a real advantage and also the thing to watch. It is priced to be an easy yes. Treat the investigation as a paid diagnostic, and when the resolution quote arrives, evaluate it as a completely fresh decision rather than as a continuation of one you already made. Owe on cards as well as the IRS? Most people who land here do. The quiz works out which debt to attack first and which route fits your numbers, in about two minutes with nothing to buy. Take the 2-minute debt relief quiz Being garnished or levied right now? Speed matters more than shopping around. Talk to Optima directly. The Offer in Compromise reality checkEvery tax relief advert is ultimately selling the Offer in Compromise, the programme that settles your debt for less than you owe. The IRS publishes the actual numbers. In fiscal year 2025 taxpayers submitted 38,797 offers and the IRS accepted 5,464, worth 98.1 million dollars. That is an acceptance rate of roughly 14 percent. So an OIC is real, but it is not the default outcome, and qualification turns on your income, allowable expenses and asset equity rather than on how much you need help. The IRS Offer in Compromise page sets out the tests and hosts a free pre-qualifier tool. Run it before you pay anyone, and treat any promise made on a first sales call, before your transcripts have been pulled, as a guess. Also worth knowing: filing an OIC costs a 205 dollar IRS application fee plus a non-refundable initial payment, and it pauses the clock on the collection statute while under review. A rejected offer can leave you worse off than a straightforward payment plan. Optima vs Tax Relief AdvocatesThese two dominate the category and readers compare them constantly. Here is where they actually differ.
Optima is cheaper to start with and has the longer track record. Tax Relief Advocates scores better on reviews and takes smaller cases. Neither gap is large enough to decide on its own. Get a written quote from both on identical facts and compare total cost and the exact refund cutoff. For a smaller boutique option, our Five Star Tax Resolution review covers that end of the market. Pros and cons👍 What Optima gets right
👎 Where Optima falls short
Free options to rule out firstI say this in every one of these reviews because it is where most of the regret comes from. Before paying a private firm, spend an hour on the following:
Who should hire Optima, and who should notWorth it if: you owe well above the 10,000 dollar minimum, you have multiple unfiled years, you are facing a garnishment or levy, your case involves a business, payroll taxes or a spouse, or you have tried the IRS yourself and hit a wall. Complexity is what you are paying for and Optima has the staff to handle it. Also worth it if you simply will not deal with the IRS yourself. That is a legitimate reason. Some people would rather pay several thousand dollars than spend a year on hold, and there is no shame in valuing your own peace of mind. Not worth it if: you owe between 10,000 and roughly 25,000 dollars, you have filed all your returns and you are not being levied. That profile almost always ends in an installment agreement, and you can obtain one online in ten minutes. After twenty years of reading these stories, this is the most common expensive mistake in the entire industry. And if your real problem is credit card debt rather than tax debt, a tax firm cannot help at all. Our ranking of debt relief companies covers that, and if bankruptcy has crossed your mind, read whether bankruptcy clears tax debt, because some older tax debt genuinely is dischargeable. What to ask before you pay the resolution fee
For heavier situations, our guide to choosing a tax debt lawyer or attorney explains when an attorney’s hourly rate beats a flat-fee firm, which is usually where criminal exposure or a large business liability is in play. Final thoughtsOptima Tax Relief is a legitimate, experienced firm that does competent work on complicated cases. It is also the most complained-about firm in its category, and the complaints cluster around one specific failure: people paying premium prices for an outcome the IRS would have given them cheaply. That makes the decision unusually clear. The value of Optima is proportional to the complexity of your case. Complicated, multi-year, business-involved, actively-being-collected: worth it. Straightforward balance, returns filed, nobody garnishing you: almost certainly not. Use the 295 dollar investigation as what it is, a cheap diagnostic. Then, when the resolution quote comes back, ask the one question that matters, which is whether you could get the same result yourself. If the honest answer is yes, take the 15-day refund and go do it. Frequently asked questions about Optima Tax ReliefIs Optima Tax Relief legit?Yes. Optima Tax Relief, LLC has operated since 2011 from Santa Ana, California, is BBB accredited with an A+ rating, and holds close to 13,000 public reviews averaging 4.30 volume-weighted: 4.5 on Trustpilot from 5,198 reviews, 4.2 on Google from 5,649, and 4.07 on BBB from 1,984. It is a real firm with credentialed staff. It also carries 786 BBB complaints over three years, the highest in its category, so legitimate does not mean trouble free. How much does Optima Tax Relief cost?The investigation phase costs 295 to 495 dollars, the lowest entry fee among the major tax resolution firms. The resolution phase starts at roughly 1,500 dollars and rises substantially with complexity, and it is quoted only after the investigation is complete. There is a 15-day money-back guarantee that covers the investigation fee only, not the resolution fee and not the outcome. What is the minimum debt for Optima Tax Relief?10,000 dollars in tax debt. If you owe less than that, or you owe between 10,000 and about 25,000 dollars with all returns filed and no active collection, you can almost certainly set up an IRS Online Payment Agreement yourself in about ten minutes for a fraction of any firm’s fee. Why does Optima Tax Relief have so many BBB complaints?786 complaints in three years, 219 closed in the last twelve months. Part of this is scale, since Optima advertises more heavily and serves more clients than most competitors. But the recurring theme is specific: clients who paid several thousand dollars and received an installment agreement, which is a legitimate resolution that the IRS grants routinely and that they could often have arranged themselves. Very few complaints allege fraud. Most allege paying for something they did not need. Is there a lawsuit against Optima Tax Relief?There is an ongoing class action alleging misconduct, negligence and violations of consumer laws, which Optima denies. We have not seen a judgment and are not treating unproven allegations as established fact. If this matters to your decision, check the current docket status yourself before signing, and search the CFPB consumer complaint database for the exact legal entity name. Does Optima Tax Relief have a money-back guarantee?A limited one. The guarantee runs for 15 days and applies to the investigation phase fee only. It does not cover the resolution fee, and it does not guarantee any outcome. Understand exactly when the window closes before you move from the investigation to the resolution phase, because that boundary is where most refund disputes happen. Will Optima Tax Relief settle my tax debt for less?Possibly, but the odds are lower than advertising implies. The Offer in Compromise is the programme that reduces what you owe, and in fiscal year 2025 the IRS accepted 5,464 of 38,797 offers, roughly 14 percent. Qualification depends on your income, allowable expenses and asset equity rather than on need. The IRS provides a free pre-qualifier tool, and anyone promising an OIC before pulling your transcripts is guessing. Optima Tax Relief vs Tax Relief Advocates: which is better?Close, with different strengths. Optima has been trading since 2011 versus 2017, and its investigation fee is lower at 295 to 495 dollars against 595 to 795. Tax Relief Advocates scores better on reviews, 4.60 volume-weighted against Optima’s 4.30, has fewer complaints (598 against 786) and accepts smaller cases from 5,000 dollars. Get a written quote from both on identical facts and compare the total cost and the exact refund cutoff. Can Optima Tax Relief stop a wage garnishment or bank levy?Yes. Levy and garnishment releases are usually granted once an acceptable collection alternative is in place, and this is among the fastest genuine wins in tax resolution. If the IRS has levied your bank account you have 21 days before the funds are remitted, so this is the one scenario where acting immediately matters more than comparing providers. Does Optima Tax Relief handle state tax debt?Yes, alongside federal. State revenue agencies run their own programmes and timelines, and several have collection powers more aggressive than the IRS. Confirm during the consultation that your specific state work is included in the quoted resolution fee rather than billed separately. Does Optima Tax Relief file unfiled tax returns?Yes, and for many clients this comes first, because the IRS will not agree to any resolution while you are non-compliant. Ask specifically whether back return preparation sits inside the quoted resolution fee or is billed separately per year, because separate billing is common and it is a frequent source of unexpected cost. How long does Optima Tax Relief take?It varies enormously by case. An installment agreement on a compliant account can complete in weeks. An Offer in Compromise with several unfiled years realistically takes a year or more, and the IRS review period alone is lengthy. Ask for a written estimate for your specific case, and be sceptical of any promise of a quick resolution on a complicated file. What credentials does Optima Tax Relief have?Optima employs enrolled agents, certified public accountants and tax attorneys. Only those three credentials can represent you before the IRS under a Form 2848 power of attorney. Before signing, ask which specific credentialed professional will sign your 2848 and get their name, because the salesperson you speak to first usually is not that person. Are there free alternatives to Optima Tax Relief?Yes, and they should be your first stop. The IRS Online Payment Agreement lets you arrange a plan yourself if you owe under 50,000 dollars. First-time penalty abatement often takes one phone call. The Taxpayer Advocate Service helps free of charge in hardship or stalled cases. Low Income Taxpayer Clinics provide free or nominal-cost representation, including in Tax Court, for qualifying incomes. Will hiring Optima Tax Relief affect my credit score?No. The IRS does not report tax debt to the credit bureaus, and the major bureaus removed tax liens from consumer credit reports years ago, so neither the debt nor hiring a representative touches your score. What does hurt you financially is an active levy or wage garnishment, which takes money from your account and paycheck directly.  CURRENT CPI DATA
All CPI data was provided by the Bureau of Labor Statistics on October 14, 2026 for the month of September 2026. See CPI Release Schedule.
Do NOT miss any inflation update.  Sign up to receive CPI Inflation Calculator's monthly alerts, and you'll be the first to know when inflation changes. You can unsubscribe at any time. Your information will never be shared or sold to a 3rd party. Wait! Do NOT miss future inflation updates.  Sign up to receive our free inflation alerts (one per month). It's free. Your information will never be shared or sold to a 3rd party.
You can unsubscribe at any time. |