Note: we are an independent blog. Our content doesn't constitute financial advice. We strive for accuracy, but please always cross-check inflation numbers directly with the BLS. We may receive compensation from some services and products reviewed on this site (learn more).
Select Page
Amine Rahal
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.
Every few months a mailer lands on my desk from a company I have never heard of, telling me I am pre-qualified for a debt consolidation loan. I keep them, because they are a useful window into how this industry actually works. Liberty First Lending sends a lot of them. What I want to show you is not whether the company is a scam, because it is not, but what actually happens when you call the number on that letter.
Before you call the number on that letter
Compares a consolidation loan against settlement, nonprofit counselling and bankruptcy
Uses your real balances, income and credit
Two minutes, no Social Security number
Your phone number is not passed to a network of lenders and debt firms
18500 Von Karman Avenue, Suite 550, Irvine, California
Started
February 2023, so it is three years old
Named principals
Sam Winkler, Member. Vernon Song, CFO.
What it actually is
Its own site says personal loan services, personal loan brokerage services and lead referral services
BBB
Accredited since June 2023, A+, ★★★★☆4.15 out of 5 from 248 reviews
BBB complaints
25 closed in three years, 4 in the last twelve months
Licensing
Utah Registered Consumer Lender. No NMLS number published anywhere on its sites.
CFPB complaints
Zero under this exact legal name
The fourteen companies on the consent form
This is the most useful fact in this review, and it is not on the mailer.
Liberty First Lending’s application page discloses the parties your information goes to when you submit it. There are fourteen, and they are named: Americor Funding, Credit9, Monevo, Prosper, BestEgg, Upstart, Marcus by Goldman Sachs, Axos Bank, Figure, Even, debt.org, In-Charge, ratespecial.com and Advantage Law.
Read that list again. Prosper, BestEgg, Upstart, Marcus and Axos are lenders, which is what you would expect from a loan application.
But Americor and Credit9 are debt settlement and debt consolidation operations, and Advantage Law is a law firm. Those are different products with very different consequences for your credit.
So when the complaint file fills with people saying they called about a loan and got pitched something else, the explanation is sitting on the company’s own form. This is not a rogue salesperson. It is the design.
One BBB complainant put it more plainly than I could: they called the number on the Liberty First mailer and reported that the phone was answered by a company called Credit Nine. We could not verify common ownership between Liberty First, Americor and Credit9.
All three sit at different Irvine addresses and none lists the others as a related business at BBB. What is verified is the referral relationship, because Liberty First discloses it itself. Our review of Americor covers where that path leads if you end up on it.
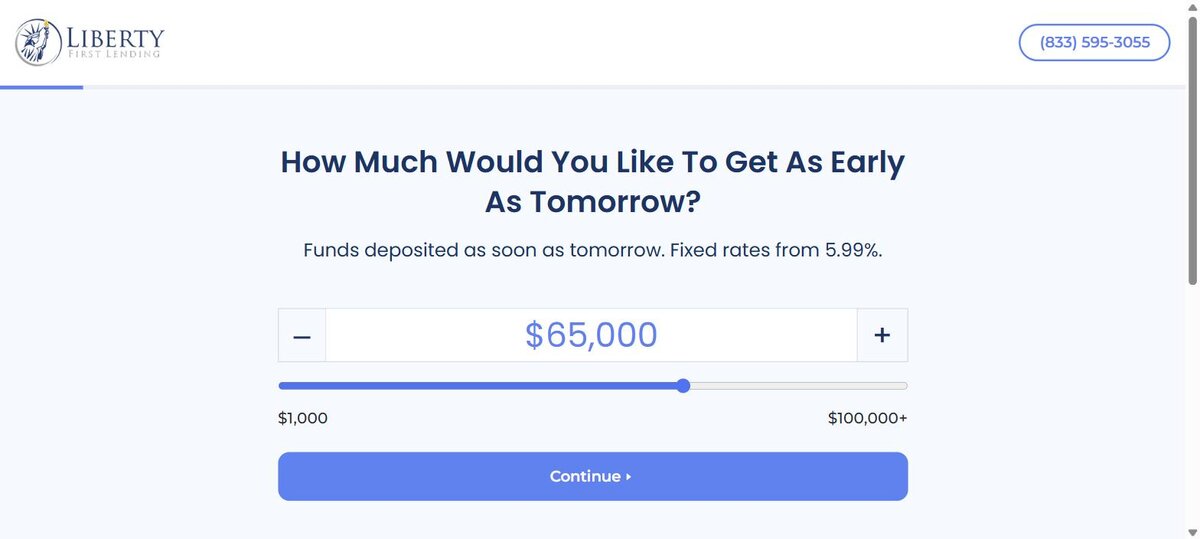
Liberty First Lending’s application funnel opens with a slider running to $100,000 or more, while its two marketing sites publish maximums of $45,000 and $75,000.
What it says it charges
APR range
5.99% to 29.99%
Loan amounts
$2,500 to $45,000 on one of its sites, $2,500 to $75,000 on the other
Origination fee
4.9%, financed into the loan
Term
Up to 60 months
Minimum credit score
None published
Credit pull
Soft at application, hard inquiry before funding
Restriction
The loan must be used to directly pay off qualifying existing debt
Two things to notice. The company runs two marketing sites publishing different maximum loan amounts, $45,000 on one and $75,000 on the other, while the application form offers $100,000 or more as a selectable option.
That is a transparency problem, not a rounding error.
And that 4.9% origination fee is financed into the loan rather than deducted, which means you pay interest on the fee for the life of the term. On a $30,000 consolidation that is roughly $1,470 rolled into the balance and accruing.
The site also concedes that lower interest rate loans and loan amounts above $35,000 may be brokered, alongside the flat statement that not all loans will be made through Liberty and loans may be brokered based on state.
The reviews are real. So is the complaint file. Both matter.
A 4.15 rating across 248 BBB reviews is not nothing, and I am not going to pretend otherwise. Plenty of people had a straightforward experience and said so.
But look at what the complaints are about. They are almost entirely from people who were never customers. That is unusual, and it is the signature of a lead generation operation rather than a lending one.
Theme one: the volume of contact
Since 11/27/24 Liberty First Lending has called and texted over 112 times and has left voicemails in excess causing my voicemail box to fill. (23 January 2025)
For months this place has been texting and calling me from various numbers and area codes spam messages, with my full NAME in all caps. (25 December 2024)
I keep getting unsolicited and unwanted phone calls from this company.
I have repeatedly asked to be removed from their call list. (20 March 2026)
Theme two: the letter promises a loan, the call is something else
Liberty First Lending advertises their business as a debt consolidation loan company and do the classic bait and switch. (24 January 2025)
Their MAILING DOES STATE you are pre-qualified FOR A LOAN. FAKE, FALSE MISLEADING! (three star review, 13 September 2024)
Theme three: where did they get my details
I never have consented for this company to get my information, nor for any other company to run my credit and give it to scam companies like this. (25 November 2024)
About those Google reviews
Worth knowing where the positive volume comes from. Liberty First’s Google review base was built through Birdeye, a paid review solicitation platform, which publishes the account as a marketing case study: zero Google reviews before adopting the platform, 272 at five stars afterwards.
Solicited reviews are legal and extremely common. But a five star average generated by a vendor whose entire job is generating five star averages is not the same evidence as an organic rating, and it should not be weighed the same way.
This is why I lean on complaint counts and regulator records rather than star averages, and why the older third party articles quoting a B plus BBB grade and 3.1 stars are simply out of date. The live figure is A plus and 4.15.
Pros and cons
👍 Publishes an APR range, origination fee and sample payments, which many lead generators never do
👍 Discloses the fourteen parties it shares your data with, on the form, before you submit
👍 BBB accredited with an A+ and a 4.15 customer rating across 248 reviews
👍 Zero CFPB complaints under its legal name, and no regulatory action we could find
👎It is a lead generator, not a lender, and the mailer does not lead with that
👎 Two of the fourteen recipients are debt settlement operations and one is a law firm
👎 Sustained unsolicited contact is the dominant complaint, in one case 112 calls and texts in under two months
👎 No NMLS number published, and a Utah consumer lender registration is a notification filing rather than a substantive licence
👎 Conflicting maximum loan amounts across its own two sites, and a privacy policy link that returns a 404
👎 Three years old, with no consumer finance operating history before 2023
What that mailer actually means
Here is the thing I most want you to take away, and it applies to every letter of this kind, not just this one.
Pre-qualified is a marketing term with no legal weight. It typically means a list broker ran a soft screen against credit bureau data and your profile matched.
It is not an offer, no underwriter has looked at your file, and the rate on the letter is the best case rate for the strongest applicant, not a rate you have been given. The headline 5.99% here is the floor of a range that tops out at 29.99%.
The second thing is that responding costs you something even if you walk away. Your details enter a distribution network. The complaint file for this company is the clearest possible illustration: the loudest and most repeated grievance is not about loan terms, it is about the phone not stopping afterwards.
If you want to stop this class of mail at source, you can opt out of pre-screened credit offers for five years or permanently at OptOutPrescreen.com, the official site run by the consumer credit reporting industry.
The Federal Trade Commission explains how prescreening works in its guide to prescreened offers. That single step will cut the volume more than any amount of asking to be removed from individual lists.
Skip the phone tree
Want the comparison without the calls?
The quiz runs the same triage a good adviser would, across settlement, consolidation, nonprofit counselling and bankruptcy, using your real numbers.
Liberty First may genuinely help if you have good credit, want to compare several lenders quickly, and are relaxed about being contacted. Its partner network includes real lenders and a broker can save you filling in five applications.
But you can reach the same lenders directly. Prosper, Upstart, BestEgg, Marcus and Axos all take applications on their own sites, and going direct means one company holds your details rather than fourteen.
If the honest situation is that a consolidation loan will not solve it, because the balances are too large relative to income or your credit will not carry a decent rate, then the loan route is a detour. Our account of clearing over 100,000 dollars in card debt walks through what actually worked, and our CreditAssociates review covers a settlement provider with a longer track record than anything on this page.
If the problem is interest rather than principal, a nonprofit debt management plan is almost always cheaper than a consolidation loan carrying a 4.9% origination fee. Money Management International is the nonprofit agency we have reviewed most closely. And if you are being sued or garnished, that is a lawyer question rather than a loan question, which our guide to debt consolidation attorneys covers.
Frequently Asked Questions
Is Liberty First Lending legit?
Yes, it is a real registered company. Liberty First Lending, LLC operates from 18500 Von Karman Avenue, Suite 550, Irvine, California, started in February 2023, and has been BBB accredited since June 2023 with an A+ rating and 4.15 stars from 248 reviews. We found no regulatory action and zero CFPB complaints under its legal name. The important caveat is what it is: by its own description it provides lead referral services alongside loan brokerage, so submitting an application shares your details with fourteen named companies.
Is Liberty First Lending a direct lender?
Not reliably. Its own site states that not all loans will be made through Liberty and that loans may be brokered based on state, and it lists lead referral services among its offerings. It also concedes that lower rate loans and amounts above 35,000 dollars may be brokered. Treat it as a broker and lead generator that sometimes lends, rather than as a lender.
Who does Liberty First Lending share my information with?
Fourteen companies, named on its own application form: Americor Funding, Credit9, Monevo, Prosper, BestEgg, Upstart, Marcus by Goldman Sachs, Axos Bank, Figure, Even, debt.org, In-Charge, ratespecial.com and Advantage Law. Most are lenders. Americor and Credit9 are debt settlement and debt consolidation operations, and Advantage Law is a law firm, which is why some applicants are pitched a debt program rather than the loan they asked about.
Is Liberty First Lending connected to Americor or Credit9?
There is a confirmed referral relationship, because Liberty First names both on its own data sharing consent. We could not confirm common ownership. The three companies sit at different Irvine addresses, and none lists the others as a related business on BBB. One BBB complainant reported calling the number on a Liberty First mailer and having the phone answered by Credit Nine. Some third party articles assert an ownership link; we found no corporate record confirming it.
What does Liberty First Lending charge?
Its published range is 5.99% to 29.99% APR with a 4.9% origination fee financed into the loan, on terms up to 60 months. Because the fee is financed rather than deducted, you pay interest on it for the whole term. Loan amounts are stated as 2,500 to 45,000 dollars on one company site and 2,500 to 75,000 dollars on the other, and no minimum credit score is published.
Does Liberty First Lending have an NMLS number?
We could not find one. Neither of its marketing sites, its terms of use, nor its application form publishes an NMLS identifier. The only licensing claim it makes is Utah Registered Consumer Lender. A Utah consumer credit notification is a filing requirement rather than a substantive lending licence, so it is weaker evidence than an NMLS registration would be.
Why won’t Liberty First Lending stop calling me?
Sustained unsolicited contact is the single largest theme in its complaint file. One BBB complainant documented 112 calls and texts in under two months; others describe messages from rotating numbers and area codes. If you responded to a mailer or submitted the form, your details went to fourteen parties, so some of the contact may not be from Liberty at all. Send a written opt out, and cut the source by opting out of prescreened credit offers at OptOutPrescreen.com.
Does responding to a pre-qualified mailer hurt my credit?
The initial check is usually a soft pull that does not affect your score. A hard inquiry is run before funding, and that does show. The larger risk is not the score, it is that your information enters a distribution network, which is what generates the call volume people complain about.
What is the catch with a 5.99% advertised rate?
It is the floor of a range that reaches 29.99%, reserved for the strongest applicants, and the mailer does not commit anyone to it. Pre-qualified has no legal weight. It generally means a list broker matched your credit profile against a screen, not that an underwriter has reviewed your file or that any offer exists.
What are better alternatives to Liberty First Lending?
If your credit is decent, apply directly to the lenders in its own partner list, such as Prosper, Upstart, BestEgg, Marcus or Axos, so one company holds your data instead of fourteen. If a loan will not fix the problem, compare debt relief providers with longer track records. If the issue is the interest rate rather than the balance, a nonprofit debt management plan usually costs less than a consolidation loan carrying a 4.9% origination fee.
I have been reviewing consumer lenders for the better part of twenty years, and I have a rule of thumb that has never let me down: when a company’s marketing is louder than its licensing, read the regulator filings before you read the website. West Capital Lending is a case study in exactly that.
It holds an A+ from the Better Business Bureau, and it has also paid state regulators more than half a million dollars since 2023 for letting unlicensed people originate loans and pull consumer credit reports. Both of those things are true at once, and the second one is the one almost nobody mentions.
Before you borrow against your home
Is a HELOC actually the right tool for this debt?
Our two minute quiz weighs consolidation, settlement, nonprofit counselling and bankruptcy against your real numbers. No Social Security number needed.
A mortgage broker, not a direct lender. Its flagship Digital HELOC is a white-labeled Figure Lending product, per its own disclosure.
BBB
Accredited since 2021, A+ letter rating, but ★★★☆☆3.41 out of 5 from 71 customer reviews
BBB complaints
52 closed in three years, 33 of them in the last twelve months
Regulatory fines
$464,417.50 (2023, four states) and $78,000 (Washington, July 2026)
CFPB complaints
36 since September 2024
What West Capital Lending actually is
This matters more than it sounds. West Capital Lending markets itself hard on a product it calls the Digital HELOC, with five minute approvals and funding in as few as five days. Read the disclosure at the bottom of its own landing pages and you find this sentence: West Capital Lending are using a white label service provided by Figure Lending. In other words, the product is Figure’s. West Capital is the front end.
That is not inherently a problem. Brokers serve a real purpose, and plenty of borrowers get a good outcome through one. But it changes what you are shopping for. If the underlying product is Figure’s, you can price it directly and compare. The company’s Connecticut disclosure is blunter still: Mortgage Broker only, not a mortgage lender or mortgage correspondent lender.
The company also runs a call-centre origination model, which is the operational detail that explains most of what follows.
The regulatory record, which is the real story
Two multistate actions, both for the same underlying problem: unlicensed people doing licensed work.
2023: $464,417.50 across four states
Hawaii, Oregon, Idaho and Texas settled jointly with the company in May 2023. The allegations, in the regulators’ own counts: 25 instances of paying commissions to unlicensed mortgage loan originators, 600 instances of allowing unlicensed originators to pull consumer credit reports for credit decisions, and 575 instances of paying originator commissions to entities rather than to licensed individuals.
The instance counts by state were Idaho 429, Oregon 393, Hawaii 270 and Texas 87.
The total penalty was $464,417.50. One hundred thousand was paid immediately and the remainder was held in abeyance for a year, to be abated on compliance. Co-founder Eric Hines signed it.
In July 2026 the Washington Department of Financial Institutions issued a consent order carrying a $75,000 fine plus a $3,000 investigation fee. The examination covered May 2022 through March 2024.
The findings run long:
Unlicensed individuals assisting borrowers
Applications accepted before the state licence was obtained
Six unlicensed managers supervising licensed loan officers
34 missing supervisory plans and an inadequate surety bond
Late and inaccurate annual and financial reports
Rate lock disclosure failures and incomplete closing disclosures
Loan originator compensation based on company profit
Two details are worth being precise about. Washington’s advertising findings cited specific phrases the company used, including lowest interest rates and closing costs possible and most competitive rates. And although the September 2025 statement of charges sought licence revocation and a five year prohibition, the final consent order did not revoke the licence.
West Capital remains licensed in Washington. The order carries no admission of wrongdoing, and the company’s public statement said it was able to work with Washington to reach a mutually acceptable agreement.
There is an irony here that I could not let pass. In March 2026 West Capital sued a competitor, loanDepot, alleging its production manager compensation structure violated the loan originator compensation rule. Washington had cited West Capital for compensating originators based on company profit the year before.
What the reviews and complaints actually say
Here is where the A+ badge stops being useful.
A BBB letter grade measures responsiveness to complaints, not customer satisfaction. Look at the two numbers side by side:
Source
Rating
Volume
BBB letter grade
A+, accredited since 2021
n/a
BBB customer reviews
★★★☆☆3.41 / 5
71 reviews
ConsumerAffairs
★★☆☆☆1.7 / 5, 78 percent one star
18 reviews
CFPB complaints
36 filed, 3 answered late, 5 with no response recorded
Sep 2024 to Aug 2026
Theme one: the calls and texts
This is by far the loudest theme, and the specific detail that recurs is rotating numbers. From the BBB complaint file:
I received a text from one of their loan officers about getting me a loan. I never initiated this conversation. I typed STOP to unsubscribe from their texts.
I then proceeded to get 4 more text messages from different loan officers. (19 September 2025)
This company called me every day the past four days, and they called five times yesterday. They also texted me. They changed their number each time. (14 November 2024)
I have blocked their number on my phone but somehow they continue to call me daily and leave a voicemail claiming that I contacted them first. (29 December 2024)
One complainant noted they were on the federal do not call list. If you value a quiet phone, that is a real cost of submitting your details here.
Theme two: terms changing at the table
Bait and switch on what my monthly payment would be with escrow and not including escrow, and approving me for the refinance with escrow just to take my appraisal money and did not deliver results. (1 December 2025)
Loan officer assured me of those terms and that is the main reason why I signed. The payment goes up by $600. (2 November 2024)
Note that four of the 36 CFPB complaints are filed under improper use of your credit report, which lines up uncomfortably with the 2023 finding about 600 unlicensed credit pulls.
West Capital Lending markets purchase, refinance and cash out products directly to consumers. The Figure Lending white label disclosure for its Digital HELOC sits further down the same site, in the small print.
The HELOC terms it publishes
Credit where it is due: unlike a lot of this sector, West Capital does publish real numbers. From its own disclosure pages:
APR range
7.05% to 15.60%
Origination fee
Up to 4.99% of the initial draw
Minimum draw
$15,000 in most states, $25,001 in Alaska, $35,000 in Texas
Other fees
Valuation $180 if an automated valuation is unavailable, manual notarisation $380, recording $0 to $315, recording taxes $0 to $1,400 per $100,000 borrowed
Speed
Funding in as few as five days, approval possible in five minutes but subject to verification
Minimum credit score
Not published
One inconsistency worth catching before you rely on a headline. One company page caps the loan at $400,000. Another headlines Unlock Up to $750K while its own fine print on the same page still says the maximum may be lower than $400,000.
Get your number in writing.
That 4.99% origination fee also deserves a moment. On a $50,000 draw that is nearly $2,500 before you have paid a cent of interest, and it is charged on the draw rather than the credit line. It is not out of line for this product category, but it is the number people skip.
Pros and cons
👍 Publishes an actual APR range, fee schedule and per state minimums, which much of this sector does not
👍 Genuinely fast when it works, with remote online notarisation and funding in about five days
👍 BBB accredited since 2021 and it does answer complaints rather than ignore them
👍 Wide product range including HELOC, cash out refinance, FHA, VA, non-QM and reverse
👎Fined twice for unlicensed activity, $464,417.50 in 2023 and $78,000 in 2026
👎 Customer rating of 3.41 out of 5 sits far below the A+ badge, and 33 of 52 complaints landed in the last year alone
👎 Persistent calls and texts from rotating numbers after opt out requests
👎 It is a broker, and the flagship HELOC is a white labeled Figure product you could price directly
👎 Repeated complaints about payment terms changing between the quote and the signing table
The bigger question: should you use home equity for consumer debt at all?
This is the part I care about more than any single company. A HELOC converts unsecured debt into secured debt. Your credit card company can sue you and garnish wages.
Your mortgage lender can take the house. Trading a 24% credit card rate for a 9% HELOC looks obviously correct on a spreadsheet and it is genuinely right for some households, particularly ones with stable income, real equity, and a spending problem that has already been fixed.
It goes wrong in a specific and predictable way: the cards get cleared, the balances creep back within eighteen months, and now there is both a HELOC payment and a card balance. I have watched that happen more times than I can count.
West Capital may work for you if you have substantial home equity, a firm handle on why the debt happened, and the patience to hold a broker to written terms. Get every number in writing before the appraisal fee leaves your account, and check the licence for your specific state at NMLS Consumer Access rather than trusting a marketing page.
Look elsewhere if you are rate shopping casually and do not want months of calls, if your equity is thin, or if you want to deal with the party actually making the credit decision.
In that last case you can approach Figure directly, since that is whose product this is.
For unsecured alternatives, our ranked list of debt relief companies shows who we rate and the third party numbers behind each one. If your balances are manageable and the real problem is interest rather than principal, a nonprofit debt management plan through an agency affiliated with the National Foundation for Credit Counseling is usually cheaper than anything on this page.
Frequently Asked Questions
Is West Capital Lending legitimate?
Yes, it is a real licensed company: West Capital Lending, Inc., NMLS #1566096, operating from Irvine, California since October 2016 and BBB accredited since 2021. Legitimate is not the same as trouble free. It has paid two state regulatory penalties for unlicensed activity, $464,417.50 across Hawaii, Oregon, Idaho and Texas in 2023 and $78,000 to Washington in July 2026, and it holds a 3.41 out of 5 customer rating on BBB across 71 reviews.
Is West Capital Lending a direct lender or a broker?
A broker. Its Connecticut disclosure states plainly that it is a mortgage broker only, not a mortgage lender or mortgage correspondent lender. Its flagship Digital HELOC is a white labeled product provided by Figure Lending, which the company discloses on its own landing pages. That means you can price the same underlying product directly with Figure and compare.
Why does West Capital Lending have an A+ from BBB but only 3.41 stars?
Because they measure different things. The letter grade reflects how a business responds to complaints filed through BBB, along with factors like time in business and accreditation. The star rating reflects what customers say. When those two diverge sharply, as they do here, the star rating and the complaint volume are the more useful signals. Fifty two complaints closed in three years, 33 of them in the last twelve months, is a rising trend rather than a settled one.
What was West Capital Lending fined for?
Both actions came down to unlicensed people doing licensed work. The 2023 multistate settlement with Hawaii, Oregon, Idaho and Texas alleged 25 instances of paying commissions to unlicensed loan originators, 600 instances of unlicensed originators pulling consumer credit reports for credit decisions, and 575 instances of paying originator commissions to entities rather than licensed individuals. Washington’s July 2026 consent order cited unlicensed staff, applications accepted before licensure, unlicensed managers supervising licensed officers, disclosure failures and prohibited advertising claims.
Did West Capital Lending lose its licence in Washington?
No. Washington’s September 2025 statement of charges sought revocation and a five year prohibition, but the final consent order issued in July 2026 did not revoke the licence. The company paid $75,000 plus a $3,000 investigation fee and remains licensed in the state. The order contains no admission of wrongdoing.
What does a West Capital Lending HELOC cost?
Its published range is 7.05% to 15.60% APR with an origination fee of up to 4.99% of the initial draw. Minimum draws are $15,000 in most states, $25,001 in Alaska and $35,000 in Texas. Additional costs include a $180 valuation fee where an automated valuation is unavailable, $380 for manual notarisation, recording fees of $0 to $315, and recording taxes of $0 to $1,400 per $100,000 borrowed. No minimum credit score is published.
Why do I keep getting calls and texts from West Capital Lending?
This is the single most common complaint against the company, and the recurring detail is that the number changes. Complainants describe replying STOP and then receiving messages from different loan officers, calls from rotating numbers after blocking, and contact despite being on do not call lists. If you submit your details to a call centre origination model, expect sustained outbound contact. If it continues after a written opt out, you can file with the BBB and the CFPB, and TCPA rules may apply.
Should I use a HELOC to pay off credit card debt?
Sometimes, but understand the trade. You are converting unsecured debt into debt secured by your home. A card issuer can sue you; a mortgage holder can foreclose. It tends to work for households with stable income, real equity and a spending pattern that has already changed. It tends to fail when the balances rebuild within a year or two and you end up carrying both the HELOC and fresh card debt. If your income is variable, unsecured routes are safer even though the interest rate looks worse.
What are the alternatives to West Capital Lending?
If you want home equity, price the product directly with Figure, since that is the underwriter behind the Digital HELOC, and get quotes from at least two other brokers. If you want to leave the house out of it, unsecured debt relief providers work on credit cards and personal loans only. If your problem is the interest rate rather than the balance, a nonprofit debt management plan is usually the cheapest route of all. Our debt relief quiz maps which of these fits your numbers.
How do I check whether West Capital Lending is licensed in my state?
Search NMLS #1566096 at NMLS Consumer Access, the free public database run by the Conference of State Bank Supervisors. Do not rely on a count of states quoted on a marketing page. We found third party sources claiming anywhere from 31 to 49 states for this company, which is exactly why the regulator database is the only source worth using.
Tax Relief Advocates, which now trades as TRA at tra.com, is an Irvine, California tax resolution firm founded in 2017. It represents people who owe the IRS and cannot pay: it negotiates installment agreements, files Offers in Compromise, requests penalty abatement, gets wage garnishments and bank levies lifted, and catches up unfiled returns. It is a real, BBB-accredited company with an A+ rating and nearly 10,000 third-party reviews. It is also, by volume, one of the most complained-about firms in its category, with 598 BBB complaints in three years.
Both of those things are true at once, and that is the whole story of this company. TRA is legitimate. Whether it is worth what it charges you depends almost entirely on whether your case is one the IRS would have resolved anyway.
Not sure whether a tax firm is even the right answer? Our two minute quiz compares settlement, consolidation, nonprofit counseling and bankruptcy against your actual numbers, with nothing to buy at the end.
Already sure your problem is IRS debt and want a direct consultation? Tax Relief Advocates covers all 50 states and the first call is free.
Tax Relief Advocates at a glance
Company
Tax Relief Advocates, trading as TRA
Founded
2017
Headquarters
16808 Armstrong Ave, Suite 215, Irvine, CA 92606
Phone
800-556-5014
Coverage
All 50 states, federal and state tax debt
Minimum tax debt
Around 5,000 dollars, occasionally as low as 3,000
Investigation fee
Roughly 595 to 795 dollars, refundable during the investigation phase only
Resolution fee
Roughly 2,500 to 5,000 dollars depending on complexity
Typical timeline
Six weeks to eighteen months
BBB
A+, accredited. 598 complaints in three years, 274 closed in the last twelve months
Guarantee
Refund of the investigation fee only if projected savings do not exceed it. No outcome guarantee.
Is Tax Relief Advocates legit? What the ratings actually say
Yes, TRA is a legitimate business. It has a physical office, an accredited BBB profile, a large public review footprint and nearly a decade of operating history. The interesting question is not legitimacy, it is consistency, and the numbers below tell that story better than any adjective I could use.
Source
Rating
Reviews
Notes
Google
★★★★★4.7
7,763
Enormous sample, heavily weighted toward named case managers
BBB customer reviews
★★★★★4.15
1,728
A+ rated and accredited, but see the complaint volume below
A 4.60 weighted average is a strong number. Now hold it next to this one: 598 formal BBB complaints in three years, 274 of them closed in the last twelve months alone. Very few companies carry a 4.7 Google rating and a complaint file that thick at the same time.
Having read through both sides, the pattern is not hard to spot. The five-star reviews almost always name a person: a case manager who returned calls, explained the process and got something done. The one-star reviews almost always describe a process: months of silence, returns that were supposed to be filed and were not, and a refund request that went nowhere after the investigation phase closed. Twenty-plus years of reading company reviews has taught me that when the praise is personal and the criticism is procedural, you are looking at a firm whose outcome depends heavily on which employee you happen to land with.
What Tax Relief Advocates costs
TRA does not publish prices, which is standard in tax resolution and still annoying. Based on figures reported consistently across independent reviews, here is the shape of it:
Investigation phase: roughly 595 to 795 dollars. TRA pulls your IRS transcripts, confirms what you owe and tells you which programs you qualify for.
Resolution phase: roughly 2,500 to 5,000 dollars. This is the actual representation work and it is quoted after the investigation.
Refund window: the investigation fee only, and only if projected savings do not exceed what you paid. Once you sign the full service agreement, that door closes.
That last point is the single most important sentence in this review, and it is the source of most of those BBB complaints. Understand exactly when your refund right ends before you sign anything. Ask for it in writing.
For context on the other end of the market, our guide to choosing a tax debt lawyer or attorney covers when a licensed attorney is worth the higher hourly rate, which is usually when there is a criminal exposure question or a large business liability involved.
What TRA can actually do for you
Tax resolution is not magic. Every option TRA can pursue is a program the IRS already publishes and that you can apply for yourself. What you are buying is representation, paperwork accuracy and someone to absorb the phone calls. That is worth real money to a lot of people. It is not worth 5,000 dollars to everyone.
Your problem
What TRA pursues
Realistic outcome
Wage garnishment
Levy release, then a collection alternative
Often the fastest genuine win. Garnishments can be released in days once a plan is in place.
Bank levy
Levy release, hardship claim
Time critical. You have 21 days before the bank sends the money.
Federal tax lien
Withdrawal, discharge or subordination
Achievable, usually tied to entering a direct debit installment agreement.
Cannot pay the balance
Installment agreement
Very likely. Under 50,000 dollars you can often set this up yourself online in ten minutes.
Genuinely cannot pay at all
Currently Not Collectible status
Underrated and often the right answer. Collections pause while your finances are underwater.
Want the debt reduced
Offer in Compromise
The long shot. See the acceptance rate below.
Penalties ballooning the balance
Penalty abatement
Good odds with first-time abatement or documented reasonable cause.
Years of unfiled returns
Back return preparation
Necessary first step. Nothing else can happen until you are compliant.
A spouse’s tax mess
Innocent spouse relief
Narrow but real, and worth professional help because the filing is technical.
Audit notice
Audit representation
Legitimate value. Do not attend an audit interview alone if the numbers are complicated.
The Offer in Compromise reality check
Every tax relief advert you have ever heard is really selling the Offer in Compromise, the program that lets you settle for less than you owe. Here is what the IRS itself reports for fiscal year 2025: taxpayers submitted 38,797 offers and the IRS accepted 5,464 of them, worth 98.1 million dollars. That is an acceptance rate of about 14 percent.
Read that number carefully, because it cuts both ways. It means an OIC is not a fantasy, roughly one in seven gets through. It also means that if a salesperson tells you on a first call that you are a strong candidate, before anyone has pulled your transcripts or looked at your asset equity, they are guessing. The IRS Offer in Compromise page spells out the qualification tests and there is a free official pre-qualifier tool on the same site. Run it before you pay anybody.
Two things almost nobody mentions on a sales call: the OIC application carries a 205 dollar IRS fee plus a non-refundable initial payment, and filing one extends the statute of limitations on your debt while it is under review. An offer that gets rejected can leave you worse off than an installment agreement you could have set up for free.
Free and low-cost alternatives to rule out first
I say this in every tax resolution review and I will keep saying it. Before you pay a private firm several thousand dollars, spend an hour on these:
IRS Online Payment Agreement. If you owe under 50,000 dollars you can usually set up a payment plan yourself at irs.gov in about ten minutes. Setup fees are modest and far below any firm’s retainer.
The Taxpayer Advocate Service. An independent organization inside the IRS that helps for free when you are facing genuine hardship or the system has stalled on you.
Low Income Taxpayer Clinics. Free or nominal-cost representation, including in Tax Court, if your income is below the threshold. The LITC directory lists them by state.
First-time penalty abatement. A single phone call to the IRS can wipe penalties if you have a clean three-year history. You do not need a representative for this.
If none of those fit, or you are being garnished right now, or you have five years of unfiled returns and no idea where to start, that is exactly when a firm like TRA earns its fee.
Still weighing tax debt against everything else you owe? Most people arriving here have both. The quiz sorts which problem to attack first and which route fits your numbers, in about two minutes.
Being garnished or levied right now? That is the one case where speed beats shopping around. Talk to TRA directly.
TaxRise vs Tax Relief Advocates
This comparison comes up constantly, and for good reason: both firms are headquartered in Irvine, California, both advertise heavily, and both have Google profiles sitting at 4.7 stars with thousands of reviews. On the public numbers they are close to indistinguishable.
Tax Relief Advocates (TRA)
TaxRise
Google rating
★★★★★ 4.7 (7,763)
★★★★★ 4.7 (9,288)
Location
16808 Armstrong Ave, Irvine, CA
19900 MacArthur Blvd, Irvine, CA
BBB accredited
Yes, A+
No BBB business profile resolved when we checked
Founded
2017
2017
Model
Two-phase: investigation then resolution
Two-phase, same structure
My practical advice: stop trying to pick a winner on reputation, because the reputations are effectively tied. Get a written quote from both, on the same case facts, and compare three things only. What does the investigation cost, what is the total quoted resolution fee, and exactly when does your refund right expire. The firm that answers all three in writing without a follow-up call is the one to use. The same applies to the third big name in this market: our Optima Tax Relief review covers a firm that has been trading since 2011 with a cheaper investigation fee but a heavier complaint file. If you want a smaller alternative, our Five Star Tax Resolution review looks at a boutique firm in the same space.
Pros and cons
👍 What TRA gets right
BBB accredited with an A+ rating, which is not universal in this industry.
Nearly 10,000 third-party reviews averaging 4.60 volume-weighted. That is a lot of people willing to say something positive in public.
Full service range. Garnishment and levy releases, liens, installment agreements, Currently Not Collectible, OIC, penalty abatement, unfiled returns, innocent spouse, audit defense.
Nationwide, federal and state. Many smaller firms handle federal only.
Money-back window on the investigation fee if projected savings do not clear the cost.
Genuinely fast on emergencies. Levy and garnishment releases are where this firm’s reviews are most consistently good.
👎 Where TRA falls short
598 BBB complaints in three years. That is the number that should slow you down, not the star rating.
No published pricing. You cannot compare without giving up your phone number.
The refund window closes at signing, and a large share of complaints are about exactly that boundary.
Outcome quality varies by case manager, which is what the review split is really telling you.
Communication gaps are the most repeated complaint theme: long silences during multi-month cases.
Nothing here is exclusive. Every program TRA pursues is one you can apply for yourself for free.
Who should hire TRA, and who should not
Worth the money if: you are being garnished or levied, you have several years of unfiled returns, you owe more than about 25,000 dollars, your situation involves a business or a spouse, or you have already tried dealing with the IRS yourself and got nowhere. In those cases the fee buys you time, accuracy and someone who knows which form unlocks which outcome.
Not worth the money if: you owe under about 10,000 dollars and you are otherwise compliant. At that level the IRS will almost certainly give you a payment plan online, in ten minutes, for a fraction of any firm’s retainer. Paying 3,000 dollars to be handed a 200 dollar solution is the most common bad outcome in this entire industry, and it is the one I get the most reader mail about.
One more distinction people get wrong. Tax debt and credit card debt are separate problems with separate solutions. The IRS has collection powers no credit card issuer has, which is why tax debt goes first. But if the real weight on you is unsecured consumer debt, a tax firm cannot help with it at all. Our ranking of debt relief companies covers that side, and both New Era Debt Solutions and TurboDebt are reviewed in detail. If bankruptcy has crossed your mind, read whether bankruptcy clears tax debt first, because the answer is more nuanced than most people expect.
What to ask before you pay the retainer
What is the total cost, investigation plus resolution, in one number? Not a range.
Exactly when does my refund right end? Get the sentence in writing.
Which specific resolution are you pursuing for me, and why that one? If the answer is “we will see after the investigation”, that is fine, but then do not accept an OIC promise on the sales call.
Who is my case manager and how do I reach them? Name and direct contact.
How often will I get an update, and in what form? Communication gaps drive most of the complaints.
Are you filing my unfiled returns, and is that inside the quoted fee? Return preparation is often billed separately.
Who signs my Form 2848 power of attorney? Ask for their credential: enrolled agent, CPA or attorney.
Final thoughts
Tax Relief Advocates is a real firm doing real work, and the volume of positive reviews is too large to dismiss. It is also carrying a complaint load that you should not dismiss either. Those two facts are not contradictory, they are what a high-volume, high-turnover sales operation looks like from the outside.
My honest read: if the IRS is actively taking money from you, call them today, because speed is worth more than shopping around. If the IRS is not actively taking money from you, spend one hour at irs.gov first. Most of the people who write to me regretting a tax relief purchase are in that second group, and almost none of the ones in the first group regret it.
And whatever you decide, get the refund boundary in writing. That single sentence is the difference between the reviews on the good side of TRA’s file and the reviews on the bad side.
Frequently asked questions about Tax Relief Advocates
Is Tax Relief Advocates legit?
Yes. Tax Relief Advocates, which trades as TRA, is a BBB-accredited company with an A+ rating, founded in 2017 and headquartered at 16808 Armstrong Ave in Irvine, California. It holds a 4.7 rating from 7,763 Google reviews and 4.15 from 1,728 BBB customer reviews. It also has 598 BBB complaints filed in the last three years, so legitimate does not mean problem free. Judge it on the complaint volume and the refund terms, not the star rating alone.
How much does Tax Relief Advocates charge?
TRA does not publish prices. Independent reviews consistently report an investigation fee of roughly 595 to 795 dollars, followed by a resolution fee of roughly 2,500 to 5,000 dollars depending on case complexity. The investigation fee is refundable only during the investigation phase, and only if projected savings do not exceed what you paid. Once you sign the full service agreement, the refund right ends.
What is the minimum tax debt for Tax Relief Advocates?
TRA typically works with people who owe 5,000 dollars or more, and in some cases will consider accounts as low as 3,000 dollars. If you owe less than about 10,000 dollars and you are otherwise compliant, an IRS Online Payment Agreement set up yourself is almost always the better financial decision.
Does Tax Relief Advocates have a money-back guarantee?
Partially. TRA will refund the investigation fee if the savings it projects do not exceed that fee. There is no guarantee of any particular outcome, and TRA’s own disclaimer states it does not guarantee debts will be resolved for a specific amount, percentage or timeframe. The refund window closes when you sign the full service agreement.
Why does Tax Relief Advocates have so many BBB complaints?
BBB records 598 complaints against TRA in the last three years, 274 of them closed in the last twelve months. Reading through them, the dominant themes are communication gaps during multi-month cases, returns that clients believed were being filed and were not, and refund disputes after the investigation phase closed. Very few allege outright fraud. Most describe a process breaking down rather than a scam.
Is TaxRise better than Tax Relief Advocates?
On public numbers they are close to tied. Both were founded in 2017, both are headquartered in Irvine, California, and both hold 4.7 Google ratings across thousands of reviews (TRA 7,763, TaxRise 9,288). TRA is BBB accredited with an A+ rating; no BBB business profile resolved for TaxRise when we checked. Rather than choosing on reputation, get a written quote from both on the same case facts and compare total cost and the exact refund cutoff.
Can Tax Relief Advocates stop a wage garnishment?
Yes, and this is where the firm’s reviews are most consistently positive. A garnishment or levy release is usually granted once an acceptable collection alternative is in place, and that can happen within days. If the IRS has levied your bank account you have 21 days before the bank remits the funds, so this is the one situation where acting immediately matters more than shopping around.
What is an Offer in Compromise and will I qualify?
An Offer in Compromise lets you settle your federal tax debt for less than you owe. In fiscal year 2025 taxpayers submitted 38,797 offers and the IRS accepted 5,464, an acceptance rate of about 14 percent. Qualification depends on your income, expenses and asset equity, not on how badly you need relief. The IRS publishes a free pre-qualifier tool. Anyone promising you an OIC before pulling your transcripts is guessing.
Can Tax Relief Advocates help with state tax debt?
Yes. TRA handles state tax liabilities alongside federal ones. State revenue agencies have their own programs, timelines and collection powers, and in some states those powers are more aggressive than the IRS. Confirm during the consultation that your specific state is included in the quoted fee.
Does Tax Relief Advocates file unfiled tax returns?
Yes, and for many clients this is the first step, because the IRS will not agree to any resolution until you are filing compliant. Ask specifically whether back return preparation is inside your quoted resolution fee or billed separately, because it is often billed separately and it is a common source of surprise costs.
Are there free alternatives to Tax Relief Advocates?
Yes, and you should rule them out first. The IRS Online Payment Agreement lets you set up a plan yourself if you owe under 50,000 dollars. The Taxpayer Advocate Service helps free of charge in hardship cases. Low Income Taxpayer Clinics provide free or nominal-cost representation, including in Tax Court, if your income qualifies. First-time penalty abatement can often be secured with one phone call.
Is Tax Relief Advocates the same company as TRA?
Yes. Tax Relief Advocates now markets itself as TRA and operates at tra.com. The legal entity, the Irvine office and the phone number are unchanged. If you see both names in search results, they refer to the same company.
How long does Tax Relief Advocates take to resolve a case?
TRA estimates six weeks to eighteen months. The range is that wide because the work varies enormously: an installment agreement on a compliant account can be done in weeks, while an Offer in Compromise on a case with several unfiled returns realistically takes a year or more. Get a written estimate for your specific case, and treat any promise of a fast resolution on a complicated file with suspicion.
Will hiring a tax relief firm hurt my credit?
No. The IRS does not report tax debt to the credit bureaus, and the major credit bureaus removed tax liens from consumer credit reports years ago. Hiring a representative has no credit impact at all. What can affect you financially is a levy or garnishment, which hits your bank account and paycheck directly rather than your credit file.
What credentials do Tax Relief Advocates staff hold?
TRA states that it employs certified public accountants, enrolled agents, attorneys and tax consultants. Only an enrolled agent, CPA or attorney can represent you before the IRS under a Form 2848 power of attorney. Before you sign, ask which credentialed professional will actually be signing your 2848, and get the name.
Optima Tax Relief is the most heavily advertised tax resolution firm in America, and it is the one readers ask me about more than any other. Founded in 2011 and based at 6 Hutton Centre Drive in Santa Ana, California, it represents people who owe the IRS: installment agreements, Offers in Compromise, penalty abatement, wage garnishment and levy releases, unfiled returns and audit defense.
It is BBB accredited with an A+ rating and holds close to 13,000 public reviews averaging 4.30 on a volume-weighted basis. It also carries 786 BBB complaints in three years, one of the highest counts in the category. Both of those are real, and the honest version of this review is about what explains the gap.
Not sure whether a tax firm is what you need at all? Our two minute quiz compares settlement, consolidation, nonprofit counseling and bankruptcy against your actual numbers, with nothing to buy at the end.
Certain your problem is IRS debt and want a consultation? Optima Tax Relief works in all 50 states and the first call is free.
Optima Tax Relief at a glance
Company
Optima Tax Relief, LLC
Founded
2011
Headquarters
6 Hutton Centre Dr, Suite 300, Santa Ana, CA 92707
Coverage
All 50 states, federal and state tax debt
Minimum tax debt
10,000 dollars
Investigation fee
295 to 495 dollars
Resolution fee
Roughly 1,500 dollars upward, scaling with complexity
Money-back guarantee
15 days, and it applies to the investigation phase fee only
BBB
A+, accredited. 786 complaints in three years, 219 closed in the last twelve months
Services
Installment agreements, Offer in Compromise, Currently Not Collectible, penalty abatement, levy and garnishment release, lien help, unfiled returns, innocent spouse, audit representation, payroll tax
Yes. Optima Tax Relief is a real, long-established firm with a physical office, BBB accreditation, an A+ rating and nearly fifteen years of trading history. The question worth asking is not whether it exists but whether the outcome justifies the fee, and the public record is genuinely split on that.
Source
Rating
Reviews
Notes
Trustpilot
★★★★★4.5
5,198
76 percent five-star, 10 percent one-star
Google
★★★★★4.2
5,649
Large sample, listed as a tax attorney practice
BBB (A+, accredited)
★★★★★4.07
1,984
Sits alongside a very high complaint count
Volume-weighted average
★★★★★4.30
12,831
How we score every company in our rankings
The complaint number you should actually weigh
786 BBB complaints in three years, with 219 closed in the last twelve months. That is the highest three-year count of any firm I have examined in this category, and it is roughly 30 percent above the next closest. Volume alone does not condemn a company, because Optima advertises harder and serves more clients than almost anyone else, so a bigger denominator produces a bigger numerator. But it is a large number by any reading and you should not skip past it.
Reading through them, the pattern that recurs is not fraud. It is expectation. The most common story is a client who paid several thousand dollars and received an installment agreement, which is a legitimate resolution but also one the IRS grants routinely and which many people could have arranged themselves online for a setup fee of well under 200 dollars. The complaint is rarely “they did nothing”. It is “they did something I did not need to pay for”.
There is also an ongoing class action alleging misconduct, negligence and consumer law violations, which Optima denies. I have not seen a judgment and I am not going to characterise unproven allegations as fact. If it matters to your decision, look up the current docket status yourself before you sign anything.
What Optima Tax Relief costs
Optima uses the standard two-phase model, and its entry price is meaningfully lower than most competitors:
Investigation phase: 295 to 495 dollars. Optima pulls your IRS transcripts, establishes exactly what you owe and identifies which programs you qualify for. This is the cheapest phase-one fee among the large firms.
Resolution phase: from roughly 1,500 dollars, rising substantially with complexity. Multi-year, multi-entity or payroll tax cases run far higher.
15-day money-back guarantee, which covers the investigation fee only. It does not cover the resolution fee and it does not survive past that window.
Minimum tax debt of 10,000 dollars.
The low investigation fee is a real advantage and also the thing to watch. It is priced to be an easy yes. Treat the investigation as a paid diagnostic, and when the resolution quote arrives, evaluate it as a completely fresh decision rather than as a continuation of one you already made.
Owe on cards as well as the IRS? Most people who land here do. The quiz works out which debt to attack first and which route fits your numbers, in about two minutes with nothing to buy.
Being garnished or levied right now? Speed matters more than shopping around. Talk to Optima directly.
The Offer in Compromise reality check
Every tax relief advert is ultimately selling the Offer in Compromise, the programme that settles your debt for less than you owe. The IRS publishes the actual numbers. In fiscal year 2025 taxpayers submitted 38,797 offers and the IRS accepted 5,464, worth 98.1 million dollars. That is an acceptance rate of roughly 14 percent.
So an OIC is real, but it is not the default outcome, and qualification turns on your income, allowable expenses and asset equity rather than on how much you need help. The IRS Offer in Compromise page sets out the tests and hosts a free pre-qualifier tool. Run it before you pay anyone, and treat any promise made on a first sales call, before your transcripts have been pulled, as a guess.
Also worth knowing: filing an OIC costs a 205 dollar IRS application fee plus a non-refundable initial payment, and it pauses the clock on the collection statute while under review. A rejected offer can leave you worse off than a straightforward payment plan.
Optima vs Tax Relief Advocates
These two dominate the category and readers compare them constantly. Here is where they actually differ.
Optima Tax Relief
Tax Relief Advocates
Founded
2011
2017
Google rating
★★★★★ 4.2 (5,649)
★★★★★ 4.7 (7,763)
Trustpilot
★★★★★ 4.5 (5,198)
★★★★★ 3.2 (18)
BBB customer rating
★★★★★ 4.07 (1,984)
★★★★★ 4.15 (1,728)
Volume-weighted
4.30 across 12,831
4.60 across 9,509
BBB complaints, 3 years
786
598
Investigation fee
295 to 495 dollars
595 to 795 dollars
Minimum debt
10,000 dollars
5,000 dollars
Refund window
15 days, investigation fee only
Investigation phase only
Optima is cheaper to start with and has the longer track record. Tax Relief Advocates scores better on reviews and takes smaller cases. Neither gap is large enough to decide on its own. Get a written quote from both on identical facts and compare total cost and the exact refund cutoff. For a smaller boutique option, our Five Star Tax Resolution review covers that end of the market.
Pros and cons
👍 What Optima gets right
Fifteen years of operating history, the longest of the major firms.
The lowest investigation fee in the category, 295 to 495 dollars, which makes the diagnostic step genuinely affordable.
Nearly 13,000 public reviews averaging 4.30 volume-weighted, including 4.5 on Trustpilot across more than 5,000 reviews.
Complete service range, including payroll tax and audit representation that smaller firms decline.
BBB accredited with an A+ rating and a documented complaint response process.
Credentialed staff. Enrolled agents, CPAs and tax attorneys who can sign a Form 2848 and represent you directly.
👎 Where Optima falls short
786 BBB complaints in three years, the highest count in the category by a clear margin.
Recurring theme of paying thousands for a standard payment plan that the IRS grants routinely and cheaply.
No published resolution pricing. You only learn the real cost after paying for the investigation.
The guarantee is narrow. 15 days, investigation fee only, nothing on outcome.
10,000 dollar minimum shuts out smaller balances, which is arguably a kindness.
An unresolved class action alleging misconduct and consumer law violations, which Optima denies.
Free options to rule out first
I say this in every one of these reviews because it is where most of the regret comes from. Before paying a private firm, spend an hour on the following:
IRS Online Payment Agreement. Under 50,000 dollars you can usually set this up yourself at irs.gov in about ten minutes for a modest setup fee. This is the single most important item on the list, because it is exactly what a large share of the complaints describe paying thousands to obtain.
First-time penalty abatement. One phone call can remove penalties if you have a clean three-year compliance history.
The Taxpayer Advocate Service. Free help from an independent office inside the IRS when you face genuine hardship or your case has stalled.
Low Income Taxpayer Clinics. Free or near-free representation, including in Tax Court, if your income qualifies. The LITC directory lists them state by state.
Who should hire Optima, and who should not
Worth it if: you owe well above the 10,000 dollar minimum, you have multiple unfiled years, you are facing a garnishment or levy, your case involves a business, payroll taxes or a spouse, or you have tried the IRS yourself and hit a wall. Complexity is what you are paying for and Optima has the staff to handle it.
Also worth it if you simply will not deal with the IRS yourself. That is a legitimate reason. Some people would rather pay several thousand dollars than spend a year on hold, and there is no shame in valuing your own peace of mind.
Not worth it if: you owe between 10,000 and roughly 25,000 dollars, you have filed all your returns and you are not being levied. That profile almost always ends in an installment agreement, and you can obtain one online in ten minutes. After twenty years of reading these stories, this is the most common expensive mistake in the entire industry.
And if your real problem is credit card debt rather than tax debt, a tax firm cannot help at all. Our ranking of debt relief companies covers that, and if bankruptcy has crossed your mind, read whether bankruptcy clears tax debt, because some older tax debt genuinely is dischargeable.
What to ask before you pay the resolution fee
What is the total resolution cost as a single number? Not a range, not “it depends”.
Which specific resolution are you pursuing and why that one?
Could I obtain this same outcome myself through the IRS? Ask it plainly and listen to the answer.
Who is my case manager and how do I reach them directly?
How often will I receive updates? Silence during long cases drives most complaints.
Is back return preparation included or billed separately?
Which credentialed professional signs my Form 2848? Get the name and credential.
For heavier situations, our guide to choosing a tax debt lawyer or attorney explains when an attorney’s hourly rate beats a flat-fee firm, which is usually where criminal exposure or a large business liability is in play.
Final thoughts
Optima Tax Relief is a legitimate, experienced firm that does competent work on complicated cases. It is also the most complained-about firm in its category, and the complaints cluster around one specific failure: people paying premium prices for an outcome the IRS would have given them cheaply.
That makes the decision unusually clear. The value of Optima is proportional to the complexity of your case. Complicated, multi-year, business-involved, actively-being-collected: worth it. Straightforward balance, returns filed, nobody garnishing you: almost certainly not.
Use the 295 dollar investigation as what it is, a cheap diagnostic. Then, when the resolution quote comes back, ask the one question that matters, which is whether you could get the same result yourself. If the honest answer is yes, take the 15-day refund and go do it.
Frequently asked questions about Optima Tax Relief
Is Optima Tax Relief legit?
Yes. Optima Tax Relief, LLC has operated since 2011 from Santa Ana, California, is BBB accredited with an A+ rating, and holds close to 13,000 public reviews averaging 4.30 volume-weighted: 4.5 on Trustpilot from 5,198 reviews, 4.2 on Google from 5,649, and 4.07 on BBB from 1,984. It is a real firm with credentialed staff. It also carries 786 BBB complaints over three years, the highest in its category, so legitimate does not mean trouble free.
How much does Optima Tax Relief cost?
The investigation phase costs 295 to 495 dollars, the lowest entry fee among the major tax resolution firms. The resolution phase starts at roughly 1,500 dollars and rises substantially with complexity, and it is quoted only after the investigation is complete. There is a 15-day money-back guarantee that covers the investigation fee only, not the resolution fee and not the outcome.
What is the minimum debt for Optima Tax Relief?
10,000 dollars in tax debt. If you owe less than that, or you owe between 10,000 and about 25,000 dollars with all returns filed and no active collection, you can almost certainly set up an IRS Online Payment Agreement yourself in about ten minutes for a fraction of any firm’s fee.
Why does Optima Tax Relief have so many BBB complaints?
786 complaints in three years, 219 closed in the last twelve months. Part of this is scale, since Optima advertises more heavily and serves more clients than most competitors. But the recurring theme is specific: clients who paid several thousand dollars and received an installment agreement, which is a legitimate resolution that the IRS grants routinely and that they could often have arranged themselves. Very few complaints allege fraud. Most allege paying for something they did not need.
Is there a lawsuit against Optima Tax Relief?
There is an ongoing class action alleging misconduct, negligence and violations of consumer laws, which Optima denies. We have not seen a judgment and are not treating unproven allegations as established fact. If this matters to your decision, check the current docket status yourself before signing, and search the CFPB consumer complaint database for the exact legal entity name.
Does Optima Tax Relief have a money-back guarantee?
A limited one. The guarantee runs for 15 days and applies to the investigation phase fee only. It does not cover the resolution fee, and it does not guarantee any outcome. Understand exactly when the window closes before you move from the investigation to the resolution phase, because that boundary is where most refund disputes happen.
Will Optima Tax Relief settle my tax debt for less?
Possibly, but the odds are lower than advertising implies. The Offer in Compromise is the programme that reduces what you owe, and in fiscal year 2025 the IRS accepted 5,464 of 38,797 offers, roughly 14 percent. Qualification depends on your income, allowable expenses and asset equity rather than on need. The IRS provides a free pre-qualifier tool, and anyone promising an OIC before pulling your transcripts is guessing.
Optima Tax Relief vs Tax Relief Advocates: which is better?
Close, with different strengths. Optima has been trading since 2011 versus 2017, and its investigation fee is lower at 295 to 495 dollars against 595 to 795. Tax Relief Advocates scores better on reviews, 4.60 volume-weighted against Optima’s 4.30, has fewer complaints (598 against 786) and accepts smaller cases from 5,000 dollars. Get a written quote from both on identical facts and compare the total cost and the exact refund cutoff.
Can Optima Tax Relief stop a wage garnishment or bank levy?
Yes. Levy and garnishment releases are usually granted once an acceptable collection alternative is in place, and this is among the fastest genuine wins in tax resolution. If the IRS has levied your bank account you have 21 days before the funds are remitted, so this is the one scenario where acting immediately matters more than comparing providers.
Does Optima Tax Relief handle state tax debt?
Yes, alongside federal. State revenue agencies run their own programmes and timelines, and several have collection powers more aggressive than the IRS. Confirm during the consultation that your specific state work is included in the quoted resolution fee rather than billed separately.
Does Optima Tax Relief file unfiled tax returns?
Yes, and for many clients this comes first, because the IRS will not agree to any resolution while you are non-compliant. Ask specifically whether back return preparation sits inside the quoted resolution fee or is billed separately per year, because separate billing is common and it is a frequent source of unexpected cost.
How long does Optima Tax Relief take?
It varies enormously by case. An installment agreement on a compliant account can complete in weeks. An Offer in Compromise with several unfiled years realistically takes a year or more, and the IRS review period alone is lengthy. Ask for a written estimate for your specific case, and be sceptical of any promise of a quick resolution on a complicated file.
What credentials does Optima Tax Relief have?
Optima employs enrolled agents, certified public accountants and tax attorneys. Only those three credentials can represent you before the IRS under a Form 2848 power of attorney. Before signing, ask which specific credentialed professional will sign your 2848 and get their name, because the salesperson you speak to first usually is not that person.
Are there free alternatives to Optima Tax Relief?
Yes, and they should be your first stop. The IRS Online Payment Agreement lets you arrange a plan yourself if you owe under 50,000 dollars. First-time penalty abatement often takes one phone call. The Taxpayer Advocate Service helps free of charge in hardship or stalled cases. Low Income Taxpayer Clinics provide free or nominal-cost representation, including in Tax Court, for qualifying incomes.
Will hiring Optima Tax Relief affect my credit score?
No. The IRS does not report tax debt to the credit bureaus, and the major bureaus removed tax liens from consumer credit reports years ago, so neither the debt nor hiring a representative touches your score. What does hurt you financially is an active levy or wage garnishment, which takes money from your account and paycheck directly.
Family Credit Management is one of the few companies in this industry I have never had to write a warning about. That is not a small thing. I have been covering debt relief for more than twenty years, and the overwhelming majority of the mail I get is from people who signed with a for-profit settlement firm and only understood the fee structure afterward. Family Credit is a different animal: a 501(c)(3) nonprofit that has been doing this for over thirty years, and whose core product costs most people about $28 a month.
Not sure whether a nonprofit debt management plan or settlement fits your situation? Our two minute quiz compares settlement, consolidation, nonprofit counseling and bankruptcy against your actual numbers, with nothing to buy at the end.
Want to speak to a nonprofit counselor directly? The NFCC will refer you to a member agency and the first session is free.
Quick answer: is Family Credit Management legit?
Yes, and it is legitimate in a stronger sense than most companies that get asked this question. Family Credit Management is a registered 501(c)(3) nonprofit, a member of the National Foundation for Credit Counseling, holds an A+ rating with the Better Business Bureau, is ISO certified, is licensed by state banking departments, and is audited annually. It says it has served more than one million consumers and helped repay over $1 billion in debt.
Its credit counseling and budget review sessions are free. You are not paying to find out whether you qualify.
Family Credit Management at a glance
Organization type
501(c)(3) nonprofit
Experience
Over 30 years
Main product
Debt Management Program (DMP)
Average monthly fee
$28 in 2025, on a sliding scale
Average setup fee
$39 one time, on a sliding scale
Counseling cost
Free, always
Accreditation
NFCC member, BBB A+, ISO certified, annually audited, licensed by state banking departments
Track record
Over 1 million consumers served, $1 billion or more repaid
What it actually costs, and why that number matters so much
Here is the comparison that should decide this for most people.
A for-profit debt settlement company typically charges 15% to 25% of your enrolled debt. On a $30,000 balance that is $4,500 to $7,500, and the fee is calculated on what you brought in, not on what you saved. Family Credit’s Debt Management Program charged an average of $28 a month plus a $39 setup fee in 2025. Over a four year plan that is roughly $1,383 in total.
On $30,000 of credit card debt
Approximate cost
Family Credit DMP, 48 months at $28 plus $39 setup
about $1,383
For-profit settlement at 22% of enrolled debt
about $6,600
Difference in fees alone
about $5,217
The tradeoff is real and I am not going to hide it. On a DMP you repay the full principal. Settlement aims to reduce what you owe. So the honest framing is not “the DMP is cheaper” in every sense, it is: a DMP costs far less in fees, protects your credit, and repays everything, while settlement may reduce the balance but costs several thousand in fees and damages your credit for years. Which one wins depends entirely on whether you can realistically repay the principal at a reduced interest rate.
What Family Credit Management actually offers
This is where a lot of coverage elsewhere gets it wrong. Family Credit is usually filed under “debt settlement companies.” That is a mislabel. Settlement is one of four things it does, and it is not the main one.
Debt Management Program. The flagship. Your unsecured debts get consolidated into one monthly payment, and the agency negotiates reduced interest rates with your creditors. You repay the full principal, usually over three to five years.
Debt Settlement. Offered for accounts that are already significantly past due or charged off. This is the exception, not the default.
DualTrack hybrid plan. Combines management and settlement, for people whose accounts are in mixed condition. Some current, some long past due.
Priority Repayment Plan. For situations where certain obligations need to be cleared ahead of others.
Credit counseling and budget review. Free, and available whether or not you enroll in anything.
That DualTrack option is genuinely uncommon and worth knowing about. Most agencies make you pick a lane. If half your accounts are current and half are six months delinquent, being forced to choose one strategy for all of them is a bad fit, and this is one of the few places that will not make you do it.
Ratings and reviews from third party sources
Source
Rating
Detail
ConsumerAffairs
★★★★★5.0 / 5
318 verified reviews, 284 of them five star
Better Business Bureau
★★★★★A+ rating
Long standing, low complaint volume
NFCC
Member agency
Held to NFCC standards, audited annually
A word of caution on that 5.0. Any rating that near perfect deserves a raised eyebrow, and I would not treat 318 reviews as a large sample for an agency that claims a million clients. What makes me comfortable here is not the score itself, it is that the score is consistent with the structure. A nonprofit charging $28 a month simply has fewer ways to disappoint you than a company charging $6,600 up front against uncertain results. Fewer promises, fewer broken ones.
The themes in the positive reviews are what you would expect: fast responses, successful interest rate reductions, staff described as patient rather than salesy. The complaints that do appear are mostly about slow starts and unclear timelines at the beginning of a plan.
The pros and cons
👍 What works
Genuinely nonprofit, a registered 501(c)(3) rather than a for-profit wearing nonprofit language.
Fees are a rounding error next to settlement pricing. Around $28 a month against thousands.
Free counseling with no obligation, so the diagnostic costs you nothing.
You repay the principal, which keeps your credit in far better shape than settlement does.
NFCC membership plus annual audits, which is real external accountability.
The DualTrack option handles mixed situations that most agencies cannot.
Over thirty years of operating history.
👎 What does not
You repay everything you owe. A DMP reduces interest, not principal.
You need enough income to sustain the monthly payment for three to five years. If the budget does not close, a DMP cannot fix it.
Credit cards get closed when they enter the plan, which reduces your available credit and can dent your score.
Creditor participation is not guaranteed. Most banks work with NFCC agencies, but not every account will be accepted.
Review volume is modest relative to the company’s claimed scale, so the ratings are thinner evidence than they look.
State availability depends on banking department licensing, so confirm your state directly.
Not the answer for secured debt such as mortgages and auto loans, or for federal tax debt.
Who this suits, and who it does not
A debt management plan is probably right for you if your problem is the interest rate rather than the principal, you have steady income, your accounts are mostly current or only recently late, and you want to get out of debt without torching your credit.
Look elsewhere if the math does not work even at a much lower interest rate, your accounts are deeply charged off, or your income is too unstable to commit to a fixed payment for several years. In those cases settlement or bankruptcy may genuinely be the more honest answer.
The mistake I see most often is people arriving at debt settlement without ever having had a free counseling session. Settlement gets advertised heavily because there is real money in it. Nonprofit counseling is barely advertised at all because there is not. That asymmetry, not the relative merits, is why so many people have never heard of the cheaper option. If you want the wider context on how the nonprofit side of this industry is organised, start with our review of the NFCC and what member agencies are held to.
Here is the case that stuck with me. A reader once sent me his settlement quote and his DMP quote side by side, on almost the same balance. The settlement projection looked better on the headline number, and he was ready to sign it. What he had not noticed was that the fee sat on the enrolled balance, the timeline assumed every creditor would cooperate, and none of it protected him from being sued in the meantime. The DMP quote was unglamorous and cost a few hundred dollars a year. He took the DMP, finished it, and kept a credit score he could use afterward. Neither document was dishonest. One was just much easier to misread than the other.
Percentage-of-debt fees, $10,000 minimum, tax debt help
If you want the whole field scored on third party ratings rather than marketing claims, our ranked comparison of debt relief companies puts nonprofit agencies and for-profit firms on the same table so the pricing gap is visible at a glance.
Not sure whether a DMP, settlement or something else fits? A free counseling session with an NFCC member agency will give you a straight answer based on your actual budget, with nothing to buy at the end of it.
You can also go directly to Family Credit Management, or take our debt relief quiz to narrow the options in about two minutes.
What to ask on your first call
What will my monthly fee actually be? The sliding scale means the average is not necessarily your number. Ask for yours.
Which of my creditors have you already confirmed will participate? Not all will, and you want that list before you commit.
What happens to my accounts when they enter the plan? Expect them to be closed, and understand what that does to your utilization ratio.
What is my realistic payoff date? If it is longer than five years, the plan may not be the right structure.
What are my alternatives if I do not qualify? A good counselor will tell you honestly, including when bankruptcy is the better route.
Before that call, it is worth knowing what the regulators say. The CFPB’s explainer on debt settlement is blunt about the risks on the for-profit side and points to nonprofit counseling as the safer first stop, and the FTC’s guide to getting out of debt walks through how credit counseling and DMPs are supposed to work so you can spot an agency that deviates from the norm.
The bottom line
Family Credit Management is the kind of organisation I wish more people found before they found the alternatives. It is a real nonprofit with three decades behind it, external accountability through the NFCC, free counseling, and a fee structure that costs a fraction of what the for-profit settlement industry charges. For someone whose problem is a punishing interest rate rather than an unpayable principal, that combination is close to ideal.
It is not a miracle. You will repay what you borrowed, you will need steady income for several years, and your cards will close. If your balance is genuinely beyond reach no matter the interest rate, a DMP will not save you and you should look at settlement or bankruptcy instead. But start here, because the counseling is free and the diagnostic is honest. The worst outcome is that you learn a DMP does not fit, which is exactly the thing you would otherwise pay thousands to find out later.
Frequently Asked Questions About Family Credit Management
Is Family Credit Management legit?
Yes. Family Credit Management is a registered 501(c)(3) nonprofit with over 30 years of operating history, a member agency of the National Foundation for Credit Counseling, ISO certified, licensed by state banking departments, audited annually, and rated A+ by the Better Business Bureau. Its credit counseling and budget reviews are free.
Is Family Credit Management a nonprofit?
Yes, it is a registered 501(c)(3) nonprofit. That is a meaningful distinction in this industry, where some for-profit companies use nonprofit sounding language without holding the status. Nonprofit status also means annual audits and external accountability through the NFCC.
How much does Family Credit Management charge?
Credit counseling and budget reviews are free. For the Debt Management Program, the 2025 average monthly fee was $28 and the average one time enrollment fee was $39. Fees are set on a sliding scale based on your circumstances and state rules, and they are built into your monthly payment.
How does a debt management plan differ from debt settlement?
A debt management plan consolidates your unsecured debts into one monthly payment and lowers your interest rates while you repay the full principal, usually over three to five years. Debt settlement tries to reduce the principal itself, but requires you to stop paying creditors, damages your credit, and typically costs 15% to 25% of your enrolled debt in fees.
Will Family Credit Management hurt my credit score?
Far less than debt settlement will. On a debt management plan you keep making payments, so your accounts stay current. The main short term effect is that enrolled credit cards get closed, which lowers your available credit and can nudge your utilization ratio up. Most people see their score recover and then improve as balances fall.
What services does Family Credit Management offer?
Four main programs: a Debt Management Program (the flagship), debt settlement for accounts that are already significantly past due or charged off, a DualTrack hybrid plan that combines both for mixed situations, and a Priority Repayment Plan. Free credit counseling and budget reviews are available whether or not you enroll.
What is the DualTrack plan?
DualTrack combines debt management and debt settlement in a single plan. It is designed for people whose accounts are in mixed condition, where some are current and suit a management plan while others are long past due and suit settlement. Most agencies make you choose one approach for everything, so this flexibility is uncommon.
Does Family Credit Management work in my state?
Availability depends on licensing with individual state banking departments, so it varies. The company describes itself as licensed by state banking departments across the U.S., but you should confirm your specific state directly during the free consultation rather than relying on any published list.
What debts can a debt management plan cover?
Unsecured debts, primarily credit cards, along with some personal loans, collections and medical bills. Debt management plans cannot help with secured debts such as mortgages and auto loans, and they do not cover federal tax debt or federal student loans.
Do all creditors have to accept a debt management plan?
No. Creditor participation is voluntary. Most major banks work routinely with NFCC member agencies and agree to reduced interest rates, but not every account will be accepted. Ask which of your specific creditors have been confirmed before you enroll.
How long does a Family Credit Management debt management plan take?
Most plans run three to five years. The exact length depends on your total balance, the interest rate reductions your creditors agree to, and how much you can pay each month. The FTC notes that a successful plan can take 48 months or more, so treat it as a multi year commitment.
Is Family Credit Management better than a for-profit debt settlement company?
For most people whose problem is the interest rate rather than an unpayable principal, yes. The fee difference is substantial: roughly $1,383 over a four year plan versus around $6,600 for settlement on a $30,000 balance. You also keep your credit intact. Settlement makes more sense when the principal is genuinely beyond reach and your credit is already damaged.
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.
Amine Rahal
Amine is an entrepreneur, investor and financial writer that covers the US economy, inflation, alternative investments, cryptocurrencies and more. He has been involved in the space for over a decade.