Drowning in credit card debt? A Mariner loan is one way to consolidate, but it is rarely the cheapest at these rates. We ranked 24 debt relief companies side by side so you can compare real fees before signing anything.
Compare 23 Debt Relief Companies
Mariner Finance Products & Services
Mariner Finance offers a variety of lending solutions tailored to individuals who may not qualify through traditional banks. Their services include:
- Personal Loans: Unsecured and secured loans for debt consolidation, medical bills, or unexpected expenses.
- Home Loans: Limited home equity loan options in select states.
- Auto Loans: Financing for new or used vehicles and refinancing options.
- Retail Financing: Loans offered in partnership with select retailers for big-ticket purchases.
Loan amounts typically range from $1,000 to $25,000 depending on your state and credit profile.
Mariner Finance Locations
Mariner Finance operates over 450 branch locations across 27 states, including:
You can visit their website to locate a branch near you. Note that online loan applications are available in select states as well.
Mariner Finance vs. Competitors
Mariner Finance caters primarily to borrowers with fair to poor credit. While this makes them more accessible, their interest rates can be much higher than traditional banks or credit unions.
Compared to online lenders like Upstart, Avant, or LendingClub—which often offer faster approvals and lower APRs—Mariner’s in-branch model may feel outdated and more time-consuming.
For those already struggling with debt, applying for another loan may not be the best move. That’s where debt relief can be a better option.
The Mariner Finance Lawsuit You Should Know About
In 2022, attorneys general from several states sued Mariner Finance, alleging the company packed loans with add-on products customers did not knowingly agree to and pushed unnecessary refinancing. A federal court declined to dismiss the case, and more states joined the suit in 2024.
That does not make Mariner a scam. It is a licensed lender operating branches in 28 states. But it does mean two things for you: read every line item on your loan agreement (decline add-ons you did not ask for), and know that loans outside the $1,500 to $12,000 range require an in-person branch visit.
Should You Choose Mariner Finance?
If you’ve exhausted your other options and need quick access to funds despite a low credit score, Mariner Finance can be a decent short-term solution. However, the high interest rates and potential fees make it less appealing than alternative forms of debt relief for those dealing with ongoing financial hardship.
As always, it’s smart to compare lenders, check your credit score, and speak with a financial advisor before committing.
Frequently Asked Questions About Mariner Finance
1. Is Mariner Finance a legitimate lender?
Yes, Mariner Finance is a licensed and regulated consumer finance company with over 450 branches across 27 U.S. states. They specialize in offering personal loans to borrowers with a wide range of credit profiles.
2. What credit score do I need to get approved?
There’s no official minimum credit score, but Mariner often works with individuals who have fair or poor credit. Applicants with scores around 580 or higher may still qualify, especially if applying in person or using collateral.
3. How much can I borrow from Mariner Finance?
Loan amounts typically range from $1,000 to $25,000, though exact limits depend on the state you live in, your credit history, and whether the loan is secured or unsecured.
4. What interest rates does Mariner Finance charge?
APR ranges from approximately 18% to 36%. The rate you receive depends on your credit profile, income, and loan type. Rates are generally higher than those from traditional banks.
5. How fast is the approval and funding process?
Some borrowers get approved the same day they apply, especially if they visit a local branch. Once approved, funds are usually deposited within 1 to 3 business days.
6. Are there any fees?
Mariner may charge an origination fee, late payment fees, and NSF (non-sufficient funds) fees. Terms vary by state, so it’s important to review your loan agreement carefully.
7. Can I pay off my loan early?
Yes. Mariner Finance does not charge prepayment penalties, so paying off your loan early can help you save on interest.
8. Can I apply online?
Yes, you can apply online in most states. However, depending on your credit and state regulations, you might need to visit a local branch to finalize your application.
9. Where are Mariner Finance branches located?
They operate in over 25 states, including Texas, Florida, Maryland, Virginia, and Georgia. You can find the nearest branch using the locator on their website.
Not sold on a high-interest loan? You have options that do not involve borrowing at up to 35.99% APR. Our free quiz compares them against your actual numbers in about two minutes.
Mariner Finance FAQ
Is Mariner Finance legit?
Yes, Mariner Finance is a licensed lender founded decades ago with hundreds of physical branches across 28 states. Legit does not mean cheap though. APRs run 16.00% to 35.99%, and the company faces an ongoing multistate lawsuit over add-on product sales, so read your agreement carefully.
What is the Mariner Finance lawsuit about?
Several state attorneys general sued Mariner in 2022, alleging customers were charged for add-on products they did not knowingly buy and pushed into unnecessary refinancing. More states joined in 2024. If you take a Mariner loan, decline any add-on you did not specifically request.
What credit score do you need for Mariner Finance?
Mariner does not publish a minimum score and regularly approves borrowers with bad credit or past bankruptcy. The trade-off is price: weaker credit generally lands near the top of the 16.00% to 35.99% APR range.
What are Mariner Finance interest rates in 2026?
APRs range from 16.00% to 35.99% on loans of $1,000 to $25,000 with terms of one to five years. Origination fees vary by state, and loans outside the $1,500 to $12,000 range require a branch visit.
What are the alternatives to a Mariner Finance loan?
If you are borrowing to deal with existing debt, compare a debt management plan through a nonprofit credit counselor, debt settlement if your situation is severe, or a lower-APR consolidation loan if your credit allows. Our free quiz sorts out which fits your numbers.
by Amine Rahal | Jul 11, 2026 | Debt Relief
Credit: CuraDebt.com
Quick Answer: Is CuraDebt Legit?
Yes. CuraDebt is a legitimate debt relief company operating since 1996 — one of the oldest in the industry — headquartered in Hollywood, Florida, and accredited by the AADR and IAPDA. What sets them apart: they handle both consumer debt settlement and tax/IRS debt relief under one roof, and they act as a matching platform that can route you to the program that fits your situation. No upfront fees for settlement, per FTC rules. Main limitations: not available in every state, and like all debt settlement, the process can hurt your credit score while negotiations are underway.
CuraDebt (https://www.curadebt.com/) is a debt relief company that has been in business since 1996 (according to their website), making it one of the oldest in the industry. They offer debt settlement and relief services for various types of unsecured debt, including credit card debt, personal loans, medical bills, and tax debt. Based on our review, CuraDebt has generated a lot of positive reviews for its debt relief services, particularly for its ability to help clients reduce their debt through negotiations with creditors. Where applicable, CuraDebt also operates as a referral and matching platform: if you don’t qualify for their settlement program, they may route you toward tax relief, business debt assistance, or other debt-management options instead of simply turning you away.
Want to see what CuraDebt can offer for your situation?
Their initial consultation is free, with no upfront fees for settlement. Every case is different — fees, terms, and program details are disclosed during the consultation before you commit to anything.
See Available Options →
CuraDebt is an affiliate partner — we may earn a commission if you use them, at no extra cost to you. This doesn’t affect our ratings.
Who is CuraDebt?
As we said earlier, CuraDebt is a debt settlement company that specializes in negotiating with creditors on behalf of consumers to reduce their overall debt. They work with individuals who are struggling to manage their credit card debt, tax debt, medical bills, or other unsecured debts.
| Headquarters |
Hollywood, Florida |
| Founded |
1996 (in Irvine, California) |
| States NOT Covered |
Connecticut, Georgia, Illinois, Kansas, Maine, Nevada, New Hampshire, Oregon, South Carolina, Vermont, West Virginia, and Puerto Rico |
| Website |
https://www.curadebt.com/ |
| Phone |
1-877-850-3328 Ext. 400 |
| Minimum Debt |
Generally $10,000 in unsecured debt for the settlement program (historically they’ve advertised lower minimums, and smaller cases may be routed to other programs — ask during the consultation) |
| Minimum Age |
21+ years old |
| Income Requirement |
No minimum, but must have verifiable regular income and be experiencing genuine financial hardship |
Company Legitimacy, Ratings & Reviews
As we covered earlier, this company has been operating in the debt settlement space since 1996, which makes it one of the oldest in the industry. In our view, the company’s longevity speaks volumes about its professionalism and customer service.
| Platform |
Rating |
Review Count |
| BBB (A+ Rating) |
4.7/5 |
~23 reviews |
| Google Reviews |
4.8/5 |
~271 reviews |
| TrustPilot |
3.3/5 |
~12 reviews |
| Yelp |
4.6/5 |
~12 reviews |
| Volume-Weighted Average |
4.73/5 |
~306 (BBB + Google + TrustPilot) |
Accreditations: Member of the American Association for Debt Resolution (AADR); Certified by the International Association of Professional Debt Arbitrators (IAPDA)
Two honest notes on the numbers. First, CuraDebt’s total review base is small compared to national giants — a few hundred reviews versus tens of thousands for the biggest settlement brands — so the averages carry less statistical weight. Second, the Trustpilot score (3.3/5) lags the other platforms, though it’s based on only about a dozen reviews. You can see exactly how CuraDebt stacks up against 21 competitors in our volume-weighted ranking of the best debt settlement companies, where they currently sit at #12.
CuraDebt BBB
CuraDebt Investopedia Rating
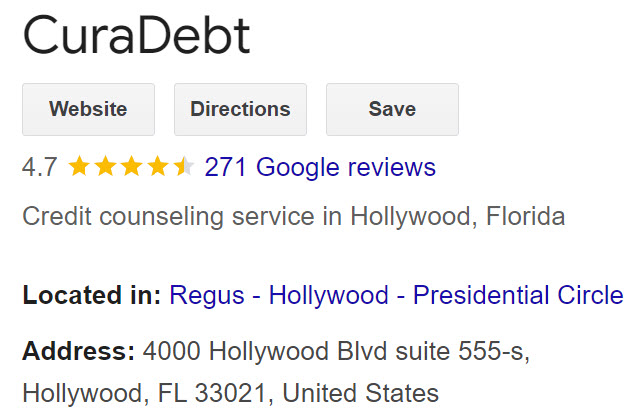
CuraDebt Google Rating
CuraDebt Key Services & Features
💬 Debt Settlement & Negotiation
Their core program: negotiating with creditors to settle unsecured debts for less than the full balance. No fees until a settlement is reached and accepted.
🏛️ Tax Debt Relief
A rarity among settlement companies: their team includes tax professionals who can work with the IRS on back taxes, penalties, and liens.
🏢 Business & MCA Debt
Assistance with business debt and merchant cash advance obligations — another niche most consumer settlement firms don’t touch.
🔀 Free Counseling & Matching
A free consultation reviews your situation and routes you to the program that fits — including consolidation through partner lenders (watch the rates if you choose this path!).
- Fee structure: No upfront fees for settlement; a fee is charged only after a debt is successfully settled and you accept the offer. Exact fees vary by program and individual circumstances and are fully disclosed during the consultation — industry sources generally cite the 15–25% of enrolled debt range for settlement programs. Get your exact fee in writing before enrolling.
- Strategy: Utilizes various strategies, such as creditor violations (e.g., FDCPA, TCPA) to negotiate better terms for clients
- Limitations: services are not available in all U.S. states (see the excluded list above).
One of the key advantages of CuraDebt is that it does not charge upfront fees for settlement, meaning you only pay once a debt settlement has been successfully negotiated — this is required by FTC rules. CuraDebt is also known for its ability to identify creditor violations, which can sometimes lead to additional savings or settlements for the client.
⚠️ Know the Trade-Offs Before You Enroll
Debt settlement can negatively impact your credit score, as the process often involves stopping payments to creditors while negotiations are underway — and creditors can pursue collections or lawsuits during that window. Forgiven debt can also create a tax bill. And no company can guarantee a specific savings percentage: outcomes depend on your creditors, your hardship, and your ability to fund the settlement account. If someone quotes you a guaranteed result before reviewing your file, treat it as a red flag — at any company. Our complete debt relief guide walks through all the alternatives, including lower-risk options like nonprofit credit counseling.
Customer Support Review
They seem to have responsive customer support through their live chat feature. We tested it ourselves: we asked their support team to explain their services, and an agent named Genesis walked us through the model clearly — you make monthly deposits into a dedicated account instead of paying creditors directly, and as the balance accumulates, CuraDebt negotiates settlements with each creditor. When an offer comes in, they contact you to present it, and the funds only move once you accept. The agent cited typical savings figures during the chat, but treat any savings numbers you hear during sales conversations as marketing estimates, not promises — your actual results depend entirely on your creditors and your situation.
How CuraDebt Compares to Other Debt Relief Companies
CuraDebt’s superpower is breadth: consumer settlement, tax debt, and business/MCA debt under one roof. Pure-play settlement firms like New Era Debt Solutions and Pacific Debt Relief don’t touch IRS debt, and neither do the big national brands like Accredited Debt Relief, Beyond Finance, or National Debt Relief. Meanwhile, dedicated tax firms like Tax Relief Advocates and Five Star Tax Resolution don’t negotiate credit card debt. If your debt problem spans both worlds, CuraDebt is one of the very few single-consultation options.
The trade-off is scale: companies like TurboDebt and Freedom Debt Relief carry review bases in the tens of thousands, while CuraDebt’s footprint is a few hundred reviews. Longevity partially offsets that — very few companies in this industry have survived since 1996.
Not sure settlement is even your best move?
Depending on your numbers, consolidation, nonprofit counseling, or even bankruptcy may fit better than settlement. Our 60-second quiz compares all of them honestly before you talk to any company.
Take the Free Debt Relief Quiz →
🔑 Key Takeaways
- CuraDebt is legitimate and one of the industry’s oldest firms: operating since 1996, BBB A+, AADR member, IAPDA certified.
- Unique breadth: consumer debt settlement, tax/IRS debt relief, and business/MCA debt help under one roof.
- No upfront fees for settlement; exact fees vary by program and are disclosed during the free consultation — get them in writing.
- Settlement generally requires ~$10,000 in unsecured debt and genuine hardship; smaller or different cases may be routed to other programs.
- Not available in CT, GA, IL, KS, ME, NV, NH, OR, SC, VT, WV, or Puerto Rico.
- Settlement hurts your credit while underway — compare it against counseling and consolidation before enrolling.
Final Thoughts
CuraDebt earns its place on our radar through longevity, breadth, and a results-based fee model. It’s a particularly strong consideration if your debt picture includes tax debt or business debt alongside credit cards — almost nobody else handles all three. If you’re a straightforward credit-card-settlement case with a large balance, also compare the bigger-volume providers in our full ranking before deciding. And if your debt is still manageable, this first-person guide on how to reduce debt in 2026 or our bankruptcy vs. debt relief comparison may help you avoid a formal program altogether.
Ready to explore your options with CuraDebt?
The consultation is free, and they’ll tell you which of their programs (if any) fits your situation — settlement, tax relief, or an alternative path.
Explore Options with CuraDebt →
CuraDebt is an affiliate partner — we may earn a commission if you use them, at no extra cost to you. This doesn’t affect our ratings.
Frequently Asked Questions About CuraDebt
What types of debt does CuraDebt handle?
CuraDebt specializes in settling unsecured debts, including credit card debt, personal loans, medical bills, and private student loans — plus tax debts and business/MCA debt, which most settlement companies won’t touch. They do not typically handle secured debts like mortgages or auto loans, although it’s worth asking during the free consultation.
How does the CuraDebt debt settlement process work?
The process begins with a free consultation to assess your debt situation and see if you qualify. If you enroll, you make monthly deposits into a dedicated savings account instead of paying creditors directly. As funds accumulate, CuraDebt negotiates with each creditor to reduce what you owe; when an offer comes in, they present it to you, and the money moves only after you accept. The typical timeframe is 24 to 48 months.
Does CuraDebt charge upfront fees?
No. CuraDebt does not charge upfront fees for debt settlement — this is required by FTC rules. Fees are charged only after a settlement is successfully reached and you accept it. Exact fees vary by program and individual circumstances and are disclosed during the consultation; industry settlement fees generally run 15–25% of enrolled debt. Get your specific fee structure in writing before enrolling.
Will using CuraDebt affect my credit score?
Yes. Participating in a debt settlement program can negatively impact your credit score, since the process often involves stopping payments to creditors while negotiations are underway. The goal is to settle debts for less than what’s owed, which may improve your overall financial situation long-term, and the credit impact is generally less severe than bankruptcy — but the short-term damage is real. Weigh it against alternatives like counseling and consolidation first.
How long does the CuraDebt settlement process take?
The debt settlement process with CuraDebt typically takes between 24 and 48 months, depending on the amount of debt and how quickly you can accumulate funds in your dedicated savings account for settlements. Larger balances and slower funding stretch the timeline.
Is CuraDebt available in all U.S. states?
No. As of 2026, CuraDebt’s services are not available in Connecticut, Georgia, Illinois, Kansas, Maine, Nevada, New Hampshire, Oregon, South Carolina, Vermont, West Virginia, or Puerto Rico. If you live in an excluded state, you’ll need an alternative — our state guides, like
Georgia debt relief options and
debt solutions for Illinois, cover providers and programs that do operate there.
Does CuraDebt offer tax debt relief?
Yes. CuraDebt offers tax debt relief services, with tax professionals who can work with the IRS on your behalf to resolve back taxes, penalties, and liens. This is one of their biggest differentiators — most debt settlement companies won’t touch IRS debt at all, forcing you to hire a separate tax firm.
What are the qualifications to use CuraDebt’s services?
For the debt settlement program, you generally need at least $10,000 in unsecured debt, must be at least 21 years old, have verifiable regular income, and be experiencing a financial hardship that makes full repayment difficult. There is no maximum debt limit. CuraDebt has historically advertised lower minimums, and cases that don’t fit settlement may be routed to their tax relief, business debt, or other programs — so it’s worth doing the free consultation even if you’re near the threshold.
What happens if I don’t qualify for CuraDebt’s settlement program?
You won’t simply be turned away. CuraDebt operates partly as a matching platform: depending on your situation, they may point you toward tax relief services, business/MCA debt assistance, or alternative debt-management options. That said, always compare any recommendation against the full menu of options yourself — our
free debt relief quiz gives you an independent read on whether settlement, consolidation, counseling, or bankruptcy fits your numbers.
What should I expect during the free consultation?
During the free consultation, a CuraDebt counselor reviews your financial situation and discusses your options for debt relief. They should explain the potential savings, timeline, risks, and fees involved — all program details are disclosed before any commitment. Come prepared with your balances, creditors, and monthly budget, and ask for everything in writing before you decide.
How do I get started with CuraDebt?
by Amine Rahal | Jul 8, 2026 | Debt Relief

Quick Answer: Is Five Star Tax Resolution Legit?
Yes. Five Star Tax Resolution is a legitimate, BBB-accredited (A+) tax relief firm founded in 2007 and headquartered in Pasadena, California, serving all 50 states. They put licensed tax attorneys, CPAs, and IRS Enrolled Agents on your case, require a minimum of $10,000 in tax debt, and offer a money-back guarantee if they can’t resolve your case. The trade-offs: premium pricing (fees start around $3,500 and average about $7,500 per Forbes) and a small third-party review footprint compared to bigger competitors.
When readers ask me about tax relief companies, I look for the same basics every time: who is actually doing the work? What services do they offer? How much do they charge? What are their reviews and ratings? Five Star Tax Resolution is a firm in the “tax problem solving” space, and my goal here is to explain how to evaluate them, what to expect from the process, and the questions I would ask before signing anything. Tax debt sits in its own corner of the debt relief world, with different rules, different negotiators, and different scams to avoid.
Is tax debt your only problem — or part of a bigger one?
If credit cards, personal loans, or medical bills are piling up alongside your IRS balance, a tax firm alone won’t fix it. Take our 60-second quiz to see which type of debt relief actually fits your full situation.
Take the Free Debt Relief Quiz →
Company Snapshot
| Official Name |
Five Star Tax Resolution Inc. |
| Headquarters |
Pasadena, California |
| Founded |
2007 |
| Service Area |
All 50 states |
| Minimum Tax Debt |
$10,000 |
| Fees |
Flat fee by phase; reported starting around $3,500, average ~$7,500 (Forbes) |
| Guarantee |
Full refund if they can’t resolve your case (per their BBB profile) |
| Team Credentials |
Tax attorneys, CPAs, IRS Enrolled Agents; NATP, NAEA, CTEC affiliations |
Legitimacy, Ratings & Reviews
Five Star Tax Resolution is a legitimate, BBB-accredited firm. Their consultations are free, they quote binding flat-rate fees, and unusually for this industry, they back the work with a money-back guarantee. Here is where their third-party ratings stand:
| Platform |
Rating |
Review Count |
| BBB (A+ Accredited) |
~4.76/5 |
Small base |
| TrustPilot |
~4.0–4.4/5 |
~23 reviews |
| Accreditations |
BBB, NATP; team certs from NAEA and CTEC |
My honest read: the ratings are good, but the review footprint is tiny for a firm operating since 2007. Compare that to a company like Tax Relief Advocates, which carries thousands of reviews across BBB and Google. A small review base isn’t disqualifying, but it means each individual review tells you less, and it makes the free consultation and written engagement letter more important, not less. One industry reviewer also noted the firm works with a reputation management company, which may partly explain the scarcity of negative feedback online. Take the star averages with a grain of salt and judge them on the specifics they put in writing for your case.
What Five Star Tax Resolution Does
Like other popular tax resolution firms (such as Tax Relief Advocates who you probably hear continuously on radio ads), the core menu typically includes:
🛡️ Protection & Relief
Wage garnishment releases, bank levy releases, and revenue officer assistance when collections are already active.
📋 Compliance Cleanup
Filing or amending missing returns — the IRS won’t negotiate anything until you’re current.
💰 Payment Solutions
Installment agreements, Currently Not Collectible status for genuine hardship, and Offers in Compromise when you qualify.
⚖️ Representation
Penalty abatement requests, audit defense, and payroll tax problem representation before the IRS.
The real differentiator is not the list. It is the quality of the people doing the work and how they communicate with you from week to week.
Five Star Tax Resolution VS Your Other Options
Let’s compare some of the most popular options when it comes to dealing with high tax debt:
| Feature |
Five Star Tax Resolution
Pro Service |
DIY with IRS
Lowest Cost |
Local CPA / EA
Hands-On |
Big National Firm
High Volume |
| Who handles your case |
Named EA/CPA/attorney as lead; dedicated case manager |
You handle calls, forms, deadlines |
Licensed practitioner; often the person you meet runs the file |
Varies; large teams, work may be distributed |
| Typical services |
Transcripts, filings, levy/garnishment relief, Installment Agreement, CNC, OIC, penalty abatement, audit defense |
Online payment plans, amended/late filings, hardship requests, phone appeals |
Same as left, plus ongoing bookkeeping/tax prep if needed |
Full menu; strong at processing volume quickly |
| Estimated fees |
Flat fee by phase; reported ~$3,500 to $7,500+ — premium end, backed by money-back guarantee |
$0 fee to IRS for basic plans; your time is the cost |
Hourly or fixed; varies by market and complexity |
Wide range; can be higher for sales-driven models |
| Best for |
Balances with active collections, missing returns, need for structured representation |
Smaller balances, straightforward plans, comfortable self-advocates |
Personalized attention, local meetings, combined tax prep + resolution |
Multi-year, multi-state, high-volume processing needs |
| Pros |
Dedicated licensed rep; transparent plan; money-back guarantee; secure document portal |
Cheapest; fastest for simple cases; full control |
Direct access to practitioner; can pair with ongoing planning/tax filing |
Extended hours; deep process staff; national footprint |
| Cons |
Premium pricing; small review footprint; outcome depends on your financials and compliance |
Steeper learning curve; time on hold; easier to miss deadlines |
Availability/pricing vary; some cases exceed a solo practice’s bandwidth |
Communication can feel impersonal; sales pressure at some firms |
| Speed to action |
Quick transcript pull and protection steps once onboarded; cases reportedly run 1 week to ~120 days |
Depends on your time and IRS phone queues |
Generally prompt, especially for local emergencies |
Intake is fast; negotiations can be assembly-line style |
| Communication |
Scheduled updates via portal/phone/email; single point of contact |
You manage all IRS communication |
Direct line to practitioner; in-person possible |
Ticket-based; multiple contacts over the life of the case |
| Transparency |
Written plan and flat fee by scope; clear what’s included |
Full control, but you must learn the rules and forms |
Usually straightforward; ask for engagement letter and deliverables |
Varies by brand; ask about cancellations and refund terms |
| Bottom line |
Balanced choice for guided, professional resolution without losing visibility into your case |
Best if the balance is small and you’re comfortable managing forms and deadlines |
Great for personalized attention and ongoing tax planning if the case fits their capacity |
Useful for complex, high-volume needs; evaluate communication quality before committing |
One more comparison worth making: if your debt problem is mostly credit cards and personal loans with some tax debt mixed in, a hybrid provider may serve you better than a pure tax firm. CuraDebt is one of the few companies we’ve reviewed that handles both consumer debt settlement and tax/IRS cases under one roof, and our full ranking of debt relief companies tags each provider by type so you can see who does what at a glance.
Does a Tax Lawyer or Attorney Help?
If you are planning to work with Five Star Tax Resolution, ask exactly who will represent you in front of the IRS. A solid tax lawyer or attorney firm will center the case around licensed professionals such as:
- Enrolled Agents (EAs) who deal with the IRS every day
- CPAs with tax controversy experience
- Tax attorneys when legal complexity or litigation risk is present
I prefer firms that name the lead practitioner on my file and give me direct contact details. If you only interact with sales staff and cannot meet the EA, CPA, or attorney assigned to you, that is a yellow flag. The same logic applies if you’re weighing legal help for consumer debts — our guide to debt consolidation lawyers and attorneys uses the exact same screening criteria.
Now, on their website, it shows Victor A. Latham as the Senior Tax Attorney. Ask if you are going to receive his services if you work with them.

Victor Latham, Senior Tax Attorney.
The Process You Should Expect
- Discovery and transcripts
The firm should pull your IRS transcripts with a signed authorization, confirm balances and deadlines, and give you a written game plan.
- Compliance first
The IRS will not negotiate until all required returns are filed. Expect a push to get current on filings and withholding or estimated payments.
- Financial analysis
A proper analysis uses IRS Collection Financial Standards to model what you can afford. This drives your eligibility for an installment plan, hardship status, or an Offer in Compromise.
- Resolution submission
The firm files the chosen path, responds to IRS notices, and handles back-and-forth until you have a written agreement or determination.
- Follow-through
Good firms set reminders for future filings and estimated payments so you do not default your agreement.
Pricing and How to Think About It
Most tax resolution work is quoted as a flat fee based on complexity. Typical industry ranges for individual cases are often $2,000 to $6,000+, with payroll tax and multi-year or audit cases costing more. Five Star sits at the premium end of that range: Forbes reports their fees start around $3,500, with average cases running about $7,500 — roughly double what some leading competitors charge. The counterweights are the binding flat-rate quote, payment plans, and the money-back guarantee if they can’t resolve your case. Many firms phase the work:
- Investigation phase to pull transcripts and map options
- Resolution phase to prepare and negotiate your case
- Compliance or monitoring phase if needed
What I ask for:
- A written engagement letter with scope, deliverables, timelines, and total cost
- Clarity on refund policies and what happens if you disengage
- A list of what is not included so there are no surprises
⚠️ Red Flag: Guaranteed Offers in Compromise
Be wary of anyone — at any firm — who guarantees an Offer in Compromise or quotes a fee before pulling transcripts and doing a real financial analysis. Only the IRS decides who qualifies, and the FTC has taken enforcement action against multiple tax relief firms for deceptive claims. Before paying anyone, run your numbers through the IRS’s own free Offer in Compromise Pre-Qualifier. If a salesperson promises “pennies on the dollar” before seeing your transcripts, walk away.
Strengths I Look For With a Firm Like This
- Clear point of contact and updates on a set cadence
- Licensed staff who will be the ones speaking to the IRS
- Education first mindset with realistic expectations
- Document portal and secure ways to share sensitive files
- Written plan that matches IRS standards rather than sales talking points
Potential Drawbacks to Weigh
- Upfront cost can feel high if the balance is small or the fix is simple — and Five Star’s fees run above industry average
- Outcome uncertainty because the IRS decision depends on your true financials and compliance history
- Time to resolution can stretch for months, especially for offers or complex payroll cases
- Small review footprint means less independent evidence than bigger firms provide
✅ Five Star Might Be a Good Fit If…
- You owe a meaningful balance ($10,000+) and are facing active collections
- You have missing returns and need both filing and negotiation help
- Your situation involves payroll tax or a prior defaulted agreement
- You want a licensed professional to speak to the IRS for you — and value the money-back guarantee enough to pay premium fees
🚫 You Might Not Need a Firm If…
- You owe a small balance and can set up a standard online payment plan yourself
- You are fully compliant and simply need a short-term extension or more time to pay
- You are comfortable using the IRS’s self-service tools and calling the agency directly
Questions I Would Ask Five Star Tax Resolution
- Who will be my licensed representative and how do I reach them directly
- Can I see a written scope of work and a total flat fee by phase
- What are realistic outcomes for my case using IRS standards
- How often will you update me and through which channel
- What happens if the IRS rejects the first proposal
- What exactly triggers your money-back guarantee — and can I get the refund terms in writing
- How will you help me stay compliant so I do not default the agreement
Documents to Gather Before You Talk
- All IRS and state notices
- Last two years of filed returns and any unfiled years list
- Recent pay stubs, bank statements, and a monthly expense breakdown
- Proof of extraordinary expenses that might matter for financial standards
- Any existing installment agreements or prior IRS correspondence
Not sure a tax firm is even the right move?
Depending on your full debt picture, settlement, consolidation, counseling, or even bankruptcy may make more sense than paying a resolution firm. Our quiz compares them all honestly, in about a minute.
Find Your Best Debt Relief Option →
🔑 Key Takeaways
- Five Star Tax Resolution is legitimate: BBB A+ accredited, founded 2007, licensed attorneys/CPAs/EAs on staff, serving all 50 states.
- Premium pricing: fees reportedly start ~$3,500 and average ~$7,500 — but they offer a binding flat-rate quote and money-back guarantee.
- $10,000 minimum tax debt; consultations are free.
- Their third-party review base is small — put extra weight on the written engagement letter, not the star averages.
- If your tax debt is small and you’re compliant, try the IRS’s free self-service tools before paying any firm.
Bottom Line
Five Star Tax Resolution offers the standard suite of tax relief services, which isn’t the same as debt settlement companies who focus on credit card debt — providers like Americor or JG Wentworth explicitly do not touch IRS debt. The value you get will depend on the caliber of the licensed professional who handles your file and the firm’s willingness to set realistic expectations. If you decide to interview them, go in with transcripts, a clear picture of your finances, and the questions above. A good firm will welcome that level of preparation, give you a sober assessment, and put everything in writing.
I always recommend speaking with more than one provider and comparing fees, scope, and who will actually represent you. If your balance and case are straightforward, consider whether you can resolve it directly with the IRS. If your situation is complex or urgent, a strong practitioner can be worth the cost by protecting your rights, preventing costly mistakes, and saving you time. And if the tax bill is just one piece of a wider debt problem, our bankruptcy vs. debt relief comparison and this first-person guide on how to reduce debt in 2026 will help you see the whole board before you commit to anything.
👉 Take the Free Debt Relief Quiz 👉 Read Our Complete Debt Relief Guide
Frequently Asked Questions About Five Star Tax Resolution
Is Five Star Tax Resolution a legitimate company?
Yes. Five Star Tax Resolution is a legitimate, BBB-accredited tax relief firm founded in 2007 and headquartered in Pasadena, California. They employ licensed tax attorneys, CPAs, and IRS Enrolled Agents — all federally authorized to represent taxpayers before the IRS — and hold affiliations with the NATP, NAEA, and CTEC. Legitimate doesn’t automatically mean right for you, though: compare fees, scope, and who will actually handle your file before signing.
How much does Five Star Tax Resolution cost?
Five Star doesn’t publish pricing, but Forbes reports fees starting around $3,500 with average cases running about $7,500 — the premium end of the industry, where typical individual cases run $2,000 to $6,000+. They provide a binding flat-rate quote after a free consultation, accept payment plans, and back the work with a money-back guarantee if they can’t resolve your case. Always get the total fee, scope, and refund terms in a written engagement letter.
What is the minimum tax debt Five Star requires?
Five Star Tax Resolution requires a minimum of $10,000 in tax debt, which is standard for the industry. If you owe less than that, you’re usually better off using the IRS’s free self-service tools: online installment agreements, penalty abatement requests, and the Offer in Compromise Pre-Qualifier all cost nothing but your time.
Does Five Star Tax Resolution offer a money-back guarantee?
Yes. According to their BBB profile, Five Star’s policy is to provide a full refund if they cannot resolve your case — a rarity in this industry. That said, “resolve” can be defined loosely, so ask exactly what triggers the guarantee and get the refund conditions in writing before you pay anything.
How long does Five Star take to resolve a tax case?
Reported timelines range from about one week to 120 days depending on complexity, with the negotiation phase typically running two to three months. Offers in Compromise and multi-year payroll cases take longer. You can speed things up by submitting requested documents quickly and staying current on filings while the case is open.
Can Five Star guarantee my tax debt will be reduced?
No — and to their credit, they don’t claim to. Only the IRS or your state tax agency decides whether you qualify for an Offer in Compromise, penalty abatement, or hardship status, based on your actual financials and compliance history. Any firm that guarantees a specific reduction before pulling your transcripts is showing you a red flag, not a feature.
Is Five Star Tax Resolution the same as a debt settlement company?
No. Tax resolution firms like Five Star negotiate with the IRS and state tax agencies under formal programs (installment agreements, Offers in Compromise, penalty abatement). Debt settlement companies negotiate with private creditors over credit cards, personal loans, and medical bills — and most won’t touch tax debt at all. Our
ranked list of debt relief companies tags each provider by type;
CuraDebt is one of the few that handles both.
Can I resolve my IRS tax debt without hiring a firm?
Often, yes. If your balance is modest and your returns are filed, the IRS lets you set up payment plans online for free, request penalty relief by phone, and check Offer in Compromise eligibility with their free Pre-Qualifier tool. A firm earns its fee when collections are already active (garnishments, levies), returns are missing, payroll tax is involved, or you simply want a licensed professional handling every IRS conversation for you.
What if I have credit card debt on top of my tax debt?
You’ll likely need two different strategies, because tax firms don’t negotiate consumer debt and most settlement companies don’t touch the IRS. Start by mapping your full picture: our
free debt relief quiz compares settlement, consolidation, counseling, and bankruptcy based on your numbers, and our
complete debt relief guide explains how each path treats tax debt differently.
Is Five Star Tax Resolution available in my state?
Yes — Five Star serves clients in all 50 states, handling both IRS and state tax agency matters. Keep in mind that state tax rules and consumer debt protections vary considerably; if you’re weighing your broader options locally, our state guides such as
California debt relief programs (Five Star’s home state) cover the state-specific landscape.